
Access all our platforms from a single account.

SAP earnings: buying lower or selling higher, and being paid to wait

Summary: SAP reports on 21 October 2026 after a 57% rise since July. One investor wants to buy lower, another already owns the shares. How can each name a price and be paid to wait?
Before a results release, options cost more than usual. That premium is what the seller of an option is paid for.
SAP is expected to publish its third-quarter 2026 results on Wednesday 21 October 2026 at 22:05, after the Xetra close (Source: SAP investor relations, as of 15 October 2026). Since its last report in July, the share price has risen about 57%, to EUR 201.55 (Source: Saxo, as of 15 October 2026, 16:43 CEST). Past performance is not indicative of future results.
Results days are rarely quiet for SAP. Over the last eight reports, the shares typically moved about 4.4% the next day. The biggest moves went both ways: up 10.6% in April 2025, and down 16.1% in January 2026, when growth in SAP’s cloud business disappointed (Source: Saxo price data; SAP Q4 2025 quarterly statement). Past performance is not indicative of future results. For investors already holding SAP, or considering a position, options can add structure to a view they already have.
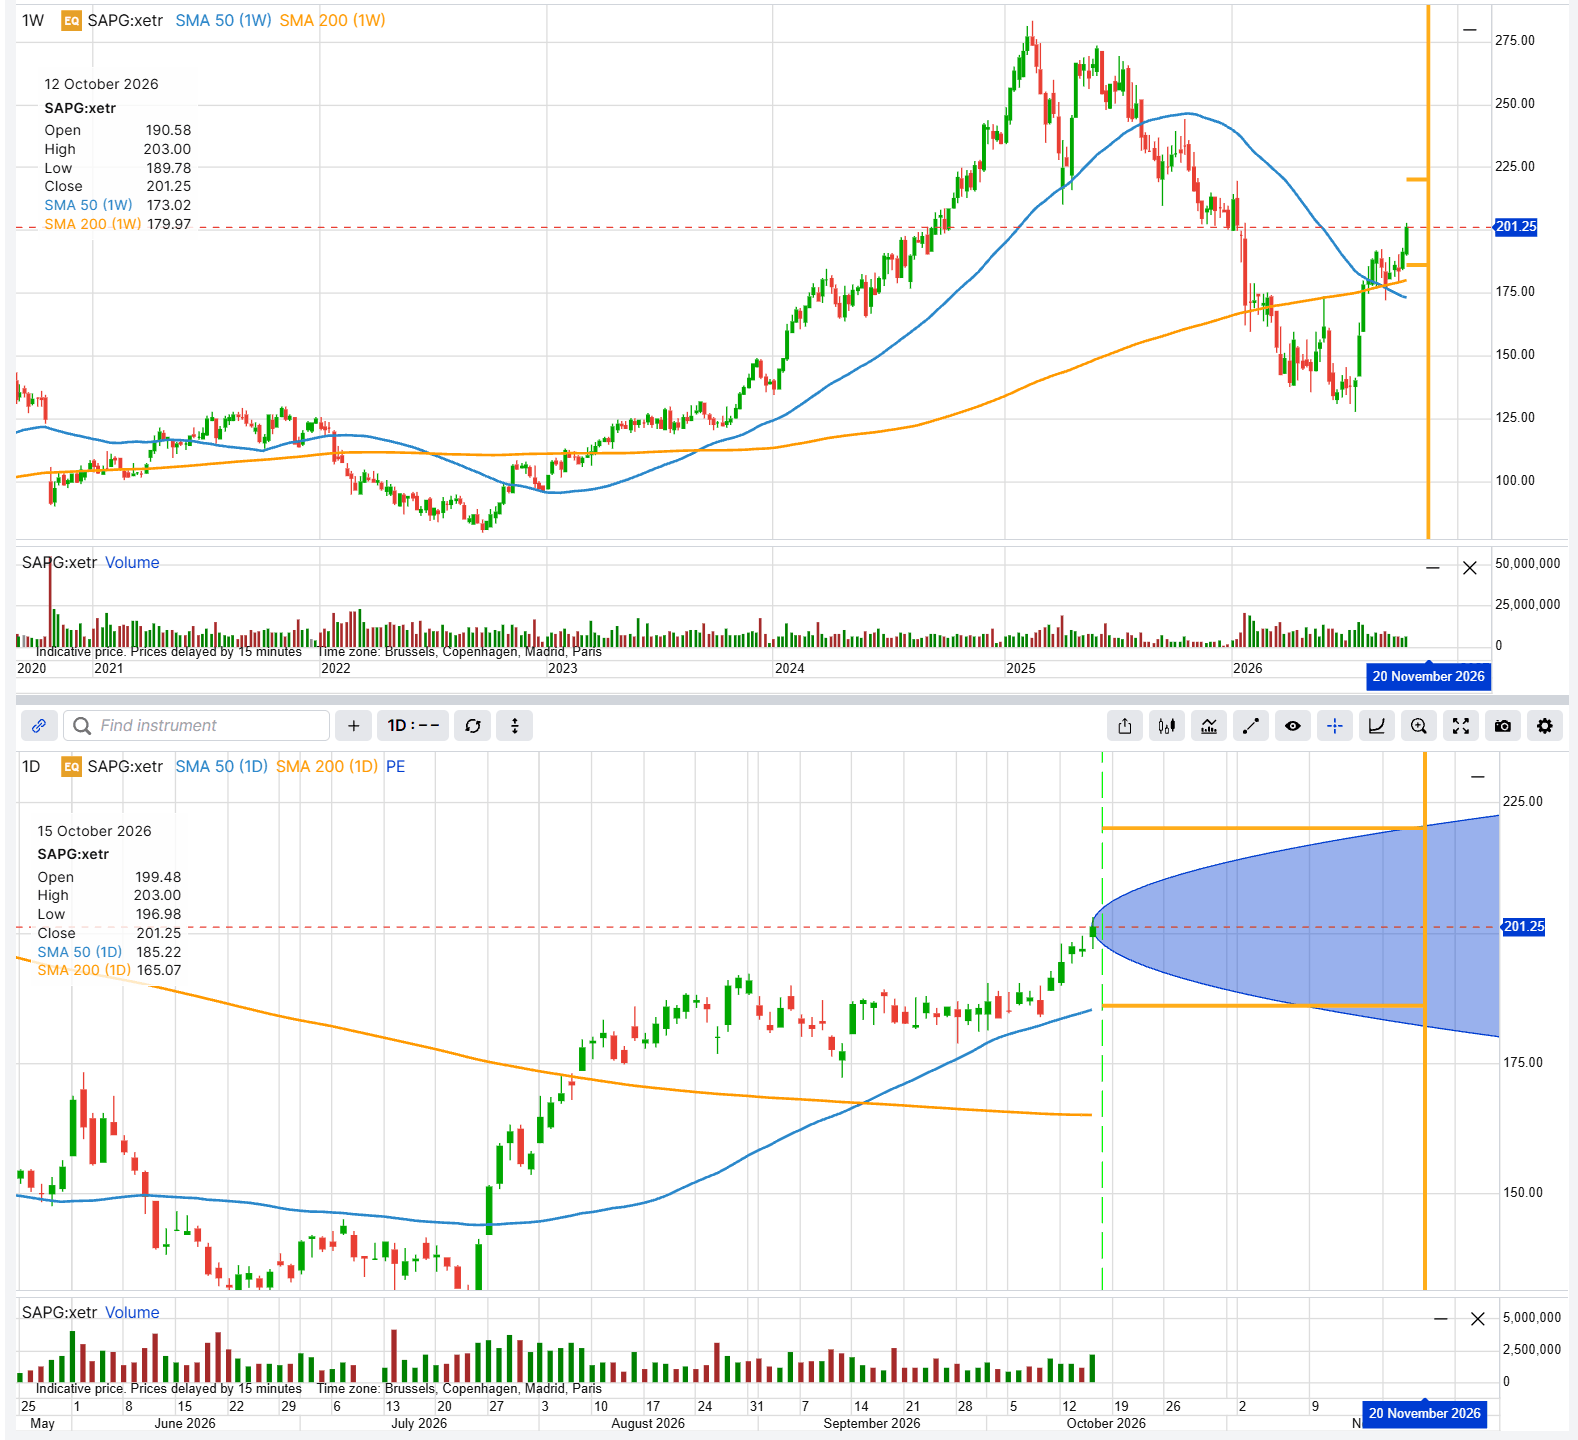 SAP weekly and daily, with the 186 and 220 strikes and the 20 November 2026 expiry marked; the shaded area is the platform's projected price range. Illustrative and educational, not predictive. Past performance is not indicative of future results. Source: SaxoTrader, indicative prices, as of 15 October 2026.
What the options market is pricing
Option prices show how big a move the market expects. Adding the price of the at-the-money call to the price of the at-the-money put for the first expiry after the report, and comparing the total with the share price, gives a rough estimate. For SAP, that points to a move of about 7.5% in either direction, almost twice its usual reaction. (We used the US-listed SAP shares, which have an option expiring two days after the report: call USD 8.85 plus put USD 8.05 makes USD 16.90, on a share price of USD 226.28. Source: Saxo, indicative prices, as of 15 October 2026, 16:43 CEST.)
On the Xetra price, that is a range of roughly EUR 186 to EUR 217. Both examples below put their strike at or just beyond the edges of that range.
Part of every SAP option’s price right now is a payment for the uncertainty of the report. Once the numbers are out, that part usually disappears, even if the share price barely moves. Traders call this IV crush. The seller of an option collects that extra payment up front. In return, the seller carries the risk of a big move, like the 16.1% fall in January 2026. Future outcomes are uncertain and may result in losses; options carry a high risk of rapid loss and are not suitable for every investor.
Important note: The strategies and examples provided in this article are purely for educational purposes. They are intended to assist in shaping your thought process and should not be replicated or implemented without careful consideration. Every investor or trader must conduct their own due diligence and take into account their unique financial situation, risk tolerance, and investment objectives before making any decisions. Remember, investing in the stock market carries risk, and it’s crucial to make informed decisions.
Why the 20 November expiry
The examples use the standard monthly SAP options on Eurex, expiring Friday 20 November 2026: 100 shares per contract, priced in EUR, American-style. A weekly Eurex expiry on 23 October exists, but on 15 October its puts showed no open interest and quotes that did not reflect a results week (Source: Saxo). November has open interest at both strikes, and shares held on Xetra are covered with Eurex options, not US ones. The trade-off is an extra month of ordinary risk, alongside a month of time decay (theta, the small amount an option loses each day, which works for the seller).
For the investor who wants to buy SAP lower: a cash-secured put at 186
Selling a cash-secured put means agreeing to buy 100 shares at the strike if SAP is below it at expiry, in exchange for a premium collected today, with the cash set aside. The view behind it: SAP is worth owning, but not at EUR 201 after a 57% run.
Hypothetical, for education only. Not advice or a trade recommendation.
Example structure (illustrative only - not a trade recommendation)
- Sell 1 SAP 20 November 2026 186 put at about 3.87 (bid 3.57, ask 4.18), with SAP at EUR 201.55
- Premium received: about EUR 387, against EUR 18,600 of cash set aside
- Delta: -0.24, a rough guide to the chance of assignment
- Purchase price if assigned: EUR 182.13, about 9.6% below the price at the time
- Maximum profit: EUR 387 (hypothetical); maximum loss: EUR 18,213 (hypothetical), if SAP fell to zero
- (Source: Saxo, indicative prices, as of 15 October 2026, 16:43 CEST)
Why 186: it sits at the lower edge of the range the options market prices for the report, so a move of the expected size would not take SAP below it. The 16.1% fall in January 2026 would have. If SAP were unchanged the day after the report, we estimate the put could be worth around half of the premium the seller collected, mostly because the payment for the report has gone. For the seller, that drop in price is a gain: buying the put back at that point would keep roughly half the premium, before costs. A big fall in SAP would do the opposite and push the put’s price up (Source: our estimate based on Saxo prices, as of 15 October 2026).
Risk: the EUR 387 is the whole upside, however far SAP rallies. Below EUR 182.13, the loss grows euro for euro, as it would for a shareholder. Options carry a high risk of rapid loss and are not suitable for every investor. Costs apply per contract; see Saxo pricing.
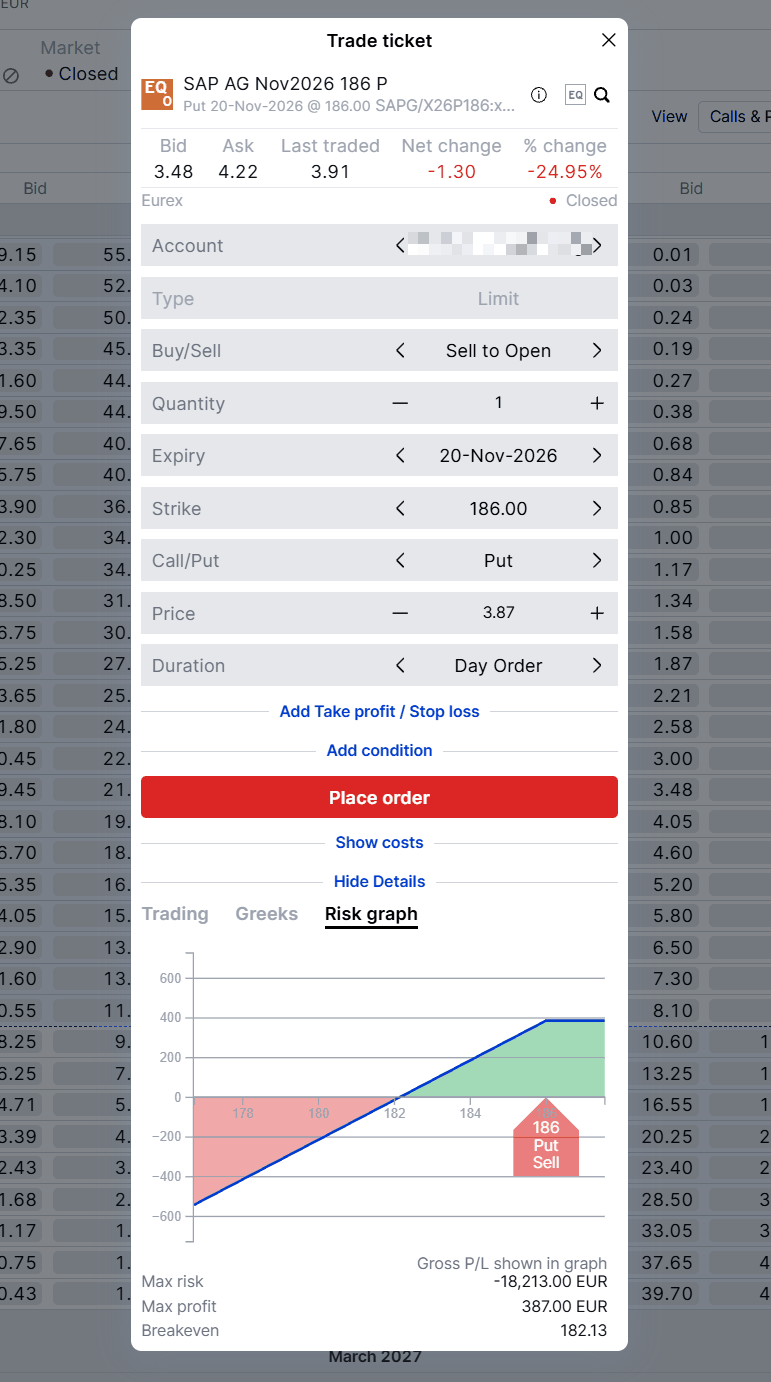
The 186 put in the SaxoTrader trade ticket, with the platform's risk graph, max risk, max profit and break-even. Hypothetical, for education only. Past performance is not indicative of future results; figures are illustrative and not predictive. Source: SaxoTrader, as of 15 October 2026.
For the investor who already holds SAP: a covered call at 220
Selling a covered call means agreeing to sell 100 shares the investor owns at the strike if SAP is above it at expiry, for a premium collected today. The view behind it: after a 57% run, the holder would be content to sell part of the position about 9% higher.
Hypothetical, for education only. Not advice or a trade recommendation.
Example structure (illustrative only - not a trade recommendation)
- Own 100 SAP shares; sell 1 SAP 20 November 2026 220 call at about 3.71 (bid 3.38, ask 4.04), with SAP at EUR 201.55
- Premium received: about EUR 371, around 1.8% of the EUR 20,155 share value
- Delta: 0.27, a rough guide to the chance the shares are called away
- Effective sale price if assigned: EUR 223.71, about 11.0% above the price at the time
- Maximum profit on the combined position at expiry: about EUR 2,216 (hypothetical), above 220; maximum loss: EUR 19,784 (hypothetical), the share value less the premium, if SAP fell to zero
- (Source: Saxo, indicative prices, as of 15 October 2026, 16:43 CEST)
Why 220: it sits above the range the options market prices for the report. Two of the last eight reactions would have carried SAP past it in one session: the 10.6% rise in April 2025 and the 9.3% rise in July 2026.
Risk: the investor retains the full downside risk of holding the shares. The premium received provides a partial offset, but it does not protect against a significant decline in the stock price; a repeat of January’s 16.1% fall would cost about EUR 3,245 on 100 shares, against EUR 371 collected. Upside above EUR 220 is given away until expiry. Options carry a high risk of rapid loss and are not suitable for every investor. Costs apply per contract; see Saxo pricing.
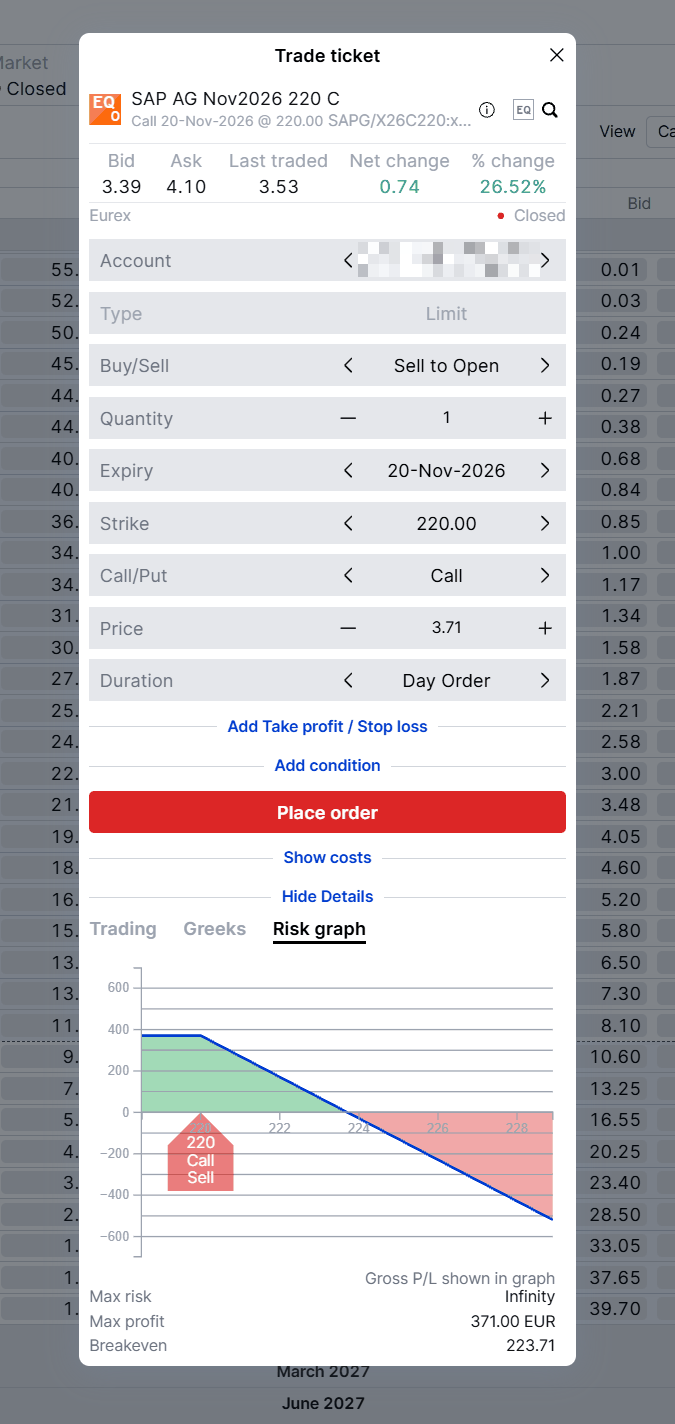
The 220 call in the SaxoTrader trade ticket. The ticket shows the call on its own, which is why it reports unlimited risk: that applies only to a call sold without the shares. Held against 100 SAP shares, a rise above 220 is covered by the shares, and the remaining risk is a fall in the share price. Hypothetical, for education only. Past performance is not indicative of future results; figures are illustrative and not predictive. Source: SaxoTrader, as of 15 October 2026.
And if neither view fits
Both examples assume the investor wants to own SAP at some price. After a 57% rise, a reasonable investor may expect the report to disappoint. In our view the put may not suit that investor: EUR 387 is unlikely to compensate for buying into a falling share. A holder with that view may prefer to trim, or to buy a protective put, which costs money instead of earning it.
The opposite case matters too. A holder who expects another 10% jump gives that jump away with the covered call. Doing nothing is a valid answer too. And these two examples are only a starting point: options offer many other ways to express a view on SAP, from protective puts to spreads that limit both the risk and the reward, each with its own trade-offs.
Before placing the trade, check:
- Bid and ask spreads; SAP options on Eurex can be wide, and selling at the bid gives up part of the premium
- Open interest at the strike and expiry
- The report timing: after the Xetra close on 21 October 2026, so the reaction shows at the open on 22 October
- Commission, charged per contract (Source: Saxo listed options commissions)
- Whether the cash is genuinely set aside; "cash-secured" is a discipline the investor applies, the platform’s margin requirement may be lower
- An exit plan, decided before the report
Assignment risk note: SAP options on Eurex are American-style, so a short option can be assigned before expiry if it moves in the money. Only the seller of an option faces assignment risk.
Final thoughts
The two examples are one idea seen from either side of the holding: the put seller names a lower price to buy at, the call seller a higher price to sell at, and both are paid for the uncertainty the report carries. Either position can be closed before expiry if the view changes.
What neither removes is the size of the move. In our view, selling an option into this report suits only an investor who would be comfortable owning, or still owning, SAP after a day like 29 January 2026. Options carry a high risk of rapid loss and are not suitable for every investor.
The author does not hold positions in any of the instruments mentioned in this article. The Author is permitted to wait at least 24 hours from the time of the publication before they trade the instruments themselves.
| Related articles/content |
|---|
| TLT naming your price on long-term bonds and being paid to wait | 29 Sep 2026 AMD after a ten percent day taking something off the table without selling the shares | 22 Sep 2026 Finding unusually expensive or cheap options in the Saxo screener | 18 Sep 2026 Apples record high is a strike price now | 16 Sep 2026 What IV crush really means in practice reviewed version | 9 April 2026 Trading earnings with defined | 31 Mar 2026 -- Front end reprices long end holds - Options Brief - 15 October 2026 Sectors pull apart the index holds - Options Brief - 14 October 2026 |
| More from the author |
|---|