Quick Take Asia

Global Market Quick Take: Asia – March 3, 2025

Macro 6 minutes to read

Key points:

  • Macro: Trump announces a digital assets strategic reserve on Sunday
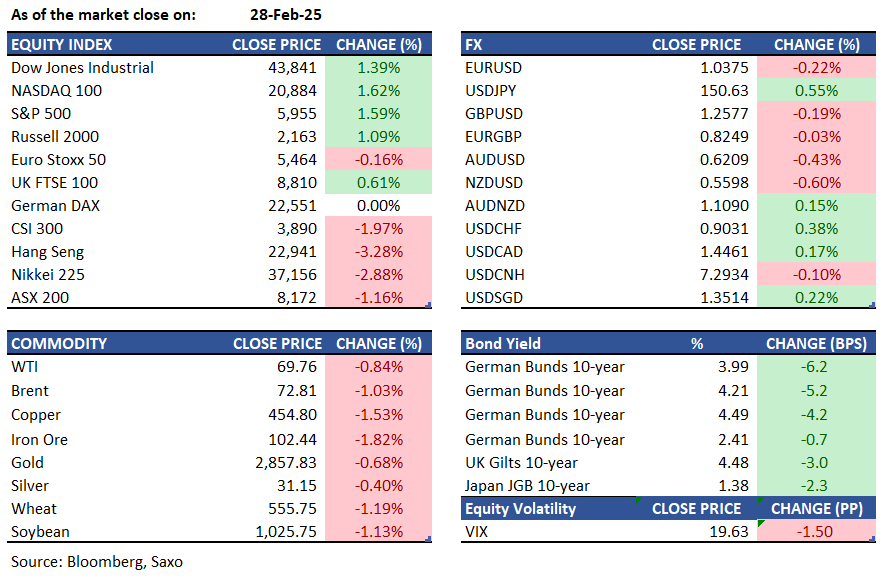
  • Equities: Nasdaq 100 recovers, gaining 1.6% on Friday to close the week.
  • FX: AUDUSD is down for the sixth session in a row
  • Commodities: Gold marked its first weekly decline of 2025
  • Fixed income: 30-year Treasury yield hit below 4.5%, the lowest since December 12

------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.


Macro:

  • China's NBS Manufacturing PMI rose to 50.2 in February 2025, indicating expansion for the first time in three months. This improvement was driven by post-Lunar New Year activity resumption and Beijing's stimulus measures. Output, new orders, and buying levels increased, while declines in foreign orders and employment eased. Input costs rose, and the drop in selling prices slowed. We look forward to the National People Congress on Wednesday this week where China will unveil the economic plan for 2025.
  • US President Trump will host the first White House cryptocurrency summit on March 7th. He mentioned that the executive order on digital assets includes a strategic reserve featuring XRP, Sol, and ADA. Trump also highlighted that BTC and ETH, as key cryptocurrencies, will be central to the reserve and expressed his admiration for Bitcoin and Ethereum.
  • US Commerce Secretary Lutnick stated that Mexico and Canada have managed the border reasonably well. However, tariffs on Canada and Mexico will be imposed on Tuesday, March 4th, with President Trump determining the levels. Lutnick also mentioned that tariffs on China will proceed unless they stop fentanyl trafficking into the US.

Equities: 

  • US - US equities closed higher on Friday, with the S&P 500 and Nasdaq each gaining 1.6%, and the Dow rising by 601 points. The market briefly dipped due to a tense exchange between President Trump and President Zelenskyy, raising geopolitical concerns. Trump's tariff threats against China added to the uncertainty, particularly for Big Tech. Nvidia rose 0.6%, recovering from an 8.5% drop despite strong earnings, while Tesla gained 3.9%, ending six days of losses amid concerns over CEO Elon Musk's political stance. Despite the gains, the S&P 500 and Nasdaq had their worst monthly declines since April 2024 and September 2023, respectively, down 1.4% and 4%, with the Dow losing 2.2%.
  • EU - European stocks closed slightly lower on Friday after a volatile week. Tech shares led the losses, with ASML and Infineon dropping 3.1% and 2.2%, respectively. Auto manufacturers recovered some losses, with Stellantis gaining 1%. BASF rose over 1% on optimistic guidance, and Saint Gobain jumped 2% after strong results. For the month, both the STOXX 50 and STOXX 600 advanced by 3.2%, outperforming US counterparts.
  • HK - HSI dropped 1.3% to 23,415, and the CSI 300 fell 2% as the US announced a 10% tariff on Chinese imports and 25% levies on Canadian and Mexican products. Hang Seng Index saw its first weekly drop in seven weeks, with tech stocks tumbling over 2.5%. Horizon Robotics led the losses with an 8.2% drop, followed by Longfor Group (-4.1%), Geely Auto (-3.4%), and Sunny Optical Tech (-2.8%).

Earnings this week:

  • Monday: No notable earnings
  • Tuesday: Target, CrowdStrike, Flutter, Sea, On Holding
  • Wednesday: Zscaler, Marvell, Campbell, Foot Locker
  • Thursday: Broadcom, Costco, BJ’s Wholesale Club, JD.com, Gap
  • Friday: No notable earnings

FX:

  • USD strengthened broadly after a contentious meeting between US President Trump and Ukrainian President Zelensky. Dollar Index (DXY) traded higher around 107.3. Trump accused Zelensky of risking World War III. A minerals deal wasn't signed, and a joint press conference was cancelled. European leaders showed solidarity with Ukraine.
  • EUR rose above 1.42 against the dollar after European leaders pledged to increase defence spending and support Ukraine.
  • The risk-off sentiment hit the AUD hardest, with AUDUSD falling for the sixth straight session, dropping below 0.62.
  • JPY didn't show its usual haven strength due to a softer-than-expected Tokyo CPI of 2.9% (expected 3.3%, previous 3.4%), ending the week around 150.50 against the USD.
  • GBP and CAD outperformed, with GBPUSD around 1.2570.
  • Major economic data: China Caixin manufacturing PMI, Eurozone inflation rate, US ISM manufacturing PMI

Commodities:

  • Oil prices rose as the market anticipated Trump's tariffs on major US trading partners and possible retaliation. Brent topped $73 a barrel, with WTI near $70. Tariffs on China, Mexico, and Canada are set for Tuesday but might be briefly delayed.
  • Gold rose as investors weighed Trump's tariffs on key trade partners. Trading near $2,870 an ounce, it saw its first weekly loss of 2025.

Fixed income:

  • Treasuries, especially front-end, rose as Fed swaps expected easing in June. The yield curve steepened with slowing PCE indexes and falling personal spending, lowering Q1 growth forecasts. The 10-year yield hit 4.23%. Fed swaps priced in 25 basis points of easing by June and 8 for May. Hedge funds covered net duration shorts for the third week, according to CFTC data.


For a global look at markets – go to Inspiration.


Disclaimer

Confidentiality and Usage:
You may not reproduce, distribute, or transmit this material or any portion thereof without prior written permission from Saxo.

Nature of Information:
The information provided herein is based on current market conditions and analysts' opinions, which may reflect personal views of the author, and are subject to change without notice. This material does not include a record of any trading prices, or an offer of, or solicitation for, or endorsement to enter into any transaction in any investment product. Any forecast on the economy, markets and economic trends of the markets provided is not necessarily indicative of the future or likely performance of the investment product subject of this material.

Responsibility and Liability:
Saxo accepts no liability for any use that may be made of these comments or for any consequences that arise from such use. Saxo does not guarantee the accuracy or completeness of any information provided and assumes no liability for any errors, omissions, losses, or damages resulting from the use of this information.

The information provided in this material is solely for information only. It is intended for general circulation and does not take into account the specific investment objectives, financial situation or particular needs of any particular person. Accordingly, it should not be relied on or treated as a substitute for specific advice concerning specific situations of any person. Please seek advice from a financial adviser regarding the suitability of any investment product taking into account your specific investment objectives, financial situation or particular needs before you make a commitment to purchase an investment product. In the event that you choose not to seek advice from a financial adviser, you should consider whether any investment product mentioned in this publication is suitable for you.

Notwithstanding the above, insofar as any information provided herein contains research analyses or reports concerning any investment product authored by any foreign research house and is issued or promulgated to a person in Singapore who is not an accredited investor, expert investor, and/or institutional investor, Saxo Capital Market Pte. Ltd. accepts legal responsibility for the contents of this material to the extent required by law. Recipients of such material are to contact Saxo Capital Markets Pte. Ltd. in respect of any matters arising from, or in connection with, this material.

Risk Disclosure:
Trading in investment products involve significant risk, including the risk of losing your entire investment. Historical returns are not a guarantee of future returns. Prices can both rise and fall, and there is a risk that you will not get back the money you invested.

Conflicts of interest:
The author may hold positions in the investment products mentioned. The author does not own positions in the underlying investment product exceeding 0.5% of its market capitalisation, save as otherwise declared. The author is not permitted to trade the mentioned investment products within the first 24 hours after the publication of this article.

Saxo maintains partnerships with companies that compensate Saxo for promotional activities conducted on its platform. Additionally, Saxo has agreements with certain partners who provide retrocession contingent upon clients purchasing specific investment products offered by these partners. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.

Publication details:
If any listed companies are the subject of the material, the content has not been submitted to the companies in question prior to publication.

Please refer to our full disclaimer and notification on non-independent investment research for more details.

Saxo Markets
88 Market Street
CapitaSpring #31-01
Singapore 048948

Contact Saxo

Singapore
Singapore

Saxo Capital Markets Pte Ltd ('Saxo Markets') is a company authorised and regulated by the Monetary Authority of Singapore (MAS) [Co. Reg. No.: 200601141M ] and is a wholly owned subsidiary of Saxo Bank A/S, headquartered in Denmark. Please refer to our General Business Terms & Risk Warning to consider whether acquiring or continuing to hold financial products is suitable for you, prior to opening an account and investing in a financial product.

Saxo is part of the J. Safra Sarasin Group.

Trading in financial instruments carries various risks, and is not suitable for all investors. Please seek expert advice, and always ensure that you fully understand these risks before trading. Trading in leveraged products such as Margin FX products may result in your losses exceeding your initial deposits. Saxo Markets does not provide financial advice, any information available on this website is ‘general’ in nature and for informational purposes only. Saxo Markets does not take into account an individual’s needs, objectives or financial situation.

The Saxo trading platform has received numerous awards and recognition. For details of these awards and information on awards visit www.home.saxo/en-sg/about-us/awards.

The information or the products and services referred to on this website may be accessed worldwide, however is only intended for distribution to and use by recipients located in countries where such use does not constitute a violation of applicable legislation or regulations. Products and Services offered on this website are not intended for residents of the United States, Malaysia and Japan. Please click here to view our full disclaimer.

This advertisement has not been reviewed by the Monetary Authority of Singapore.

Apple and the Apple logo are trademarks of Apple Inc, registered in the US and other countries and regions. App Store is a service mark of Apple Inc. Google Play and the Google Play logo are trademarks of Google LLC.