
Access all our platforms from a single account.

Global Market Quick Take: Asia – March 26, 2025

Key points:
- Macro: US new single-family homes rise 1.8%
- Equities: HSI fell 2.4%; Xiaomi is down 6.1% after 5.2b share sale
- FX: USD slightly weakened; JPY strengthened below 150 level
- Commodities: Copper futures on Comex hit a record high
- Fixed income: Treasuries reversed the losses to rally
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- U.S. sales of new single-family homes rose 1.8% to an annual rate of 676,000 in February 2025, recovering from a 6.9% drop in January but slightly below the expected 680,000. Warmer weather and easing mortgage rates attracted some buyers, but sales may remain pressured by economic uncertainty.
- Consumer confidence fell for the fourth month in March, dropping to 92.9 vs 94 est, the lowest in 4 years.
- Expectations for future business conditions and employment prospects hit a 12-year low, and optimism about future income vanished. Inflation expectations rose from 5.8% in February to 6.2% in March, amid concerns about high staple prices and tariffs.
- The S&P CoreLogic Case-Shiller 20-city home price index rose 4.7% year-on-year in January, up from 4.5% in December, but below the expected 4.8%. Growth was the fastest since last August, though high mortgage rates may slow it. New York led with a 7.7% gain, followed by Chicago at 7.5% and Boston at 6.6%.
- UK retail sales gauge fell by 18 points to -41.0 in March 2025, the lowest since April 2024 and below the expected -28.0. This marks the sixth consecutive monthly decline, with global trade tensions and the Autumn Budget cited as factors reducing consumer and business confidence, leading to weaker demand.
- The US and Russia have agreed to ensure safe navigation and prevent military use of commercial vessels in the Black Sea, as per a White House statement. They will also develop measures to ban strikes on energy facilities in Russia and Ukraine. The US will support ongoing negotiations for a peaceful resolution.
Equities:
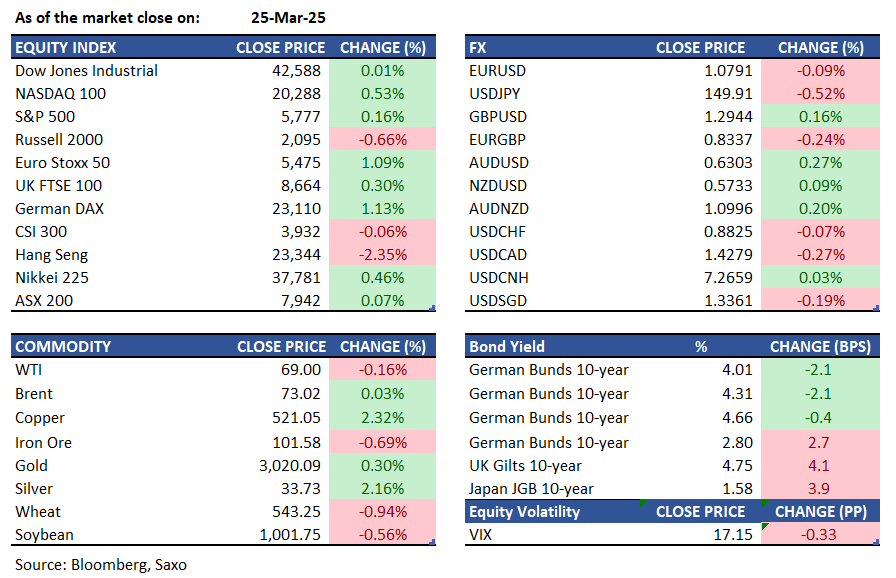
- US - On Tuesday, the S&P 500 increased by 0.1% and the Nasdaq by 0.5%, marking three days of gains. The Dow Jones stayed flat due to investor concerns over upcoming tariffs and economic uncertainty. Optimism about targeted tariff measures on Monday was dampened when President Trump proposed exemptions for some countries and hinted at new tariffs on pharmaceuticals and autos. Tesla rose 3.4% after a 12% surge on Monday, while Nvidia fell 0.6%. KB Home dropped 5.1% after cutting its sales forecast, and UniFirst plunged 14.1% as Cintas withdrew from acquisition talks. Consumer confidence declined to a four-year low, with future expectations at their weakest in 12 years.
- EU - On Tuesday, European markets rose with updates on U.S. trade policies and stronger German business confidence. The STOXX 50 increased by 0.7% to 5,450, the STOXX 600 gained 0.6%, and Frankfurt's DAX rose 1.1% to 23,110, breaking a four-day losing trend. President Trump suggested exemptions for some tariffs starting April 2 but confirmed duties on autos, pharmaceuticals, and Venezuelan crude-buying nations. Germany's Ifo Business Climate index hit an eight-month high, boosted by a significant infrastructure and defence spending approval. Meanwhile, Ukraine and Russia agreed to a Black Sea ceasefire following discussions with U.S. officials in Saudi Arabia.
- HK - HSI fell 2.4% to a two-week low of 23,344, reversing earlier gains due to broad losses as traders took profits before quarter-end. The tech index dropped 3.8%, with Xiaomi down 6.1% after announcing a $5.27 billion share sale. Alibaba fell nearly 4% due to rising data centre costs, and Sunny Optical plunged 9.9% over capacity concerns. Consumer and financial stocks also declined, despite a broader Asian rally following U.S. President Trump's tariff reduction signals. EV stocks saw steep losses, including BYD Electronic (-9.4%), Geely Auto (-5.4%), and Li Auto (-5.0%).
Earnings this week:
Wednesday: Dollar Tree, MicroVision, Chewy, Target Hospitality, Jinko Solar
Thursday: Bitfarms, Lululemon, Winnebago, TD SYNNEX, Braze
Friday: LpA, Katapult, Super League, zSpace, LiqTech
FX:
- USD showed only slight weakness throughout the day, recovering from intraday lows with support emerging after a short dip below the 104.00 level, despite disappointing US Consumer Confidence data. Meanwhile, President Trump confirmed the April 2nd tariffs and repeated his criticism of the EU concerning trade.
- EUR fluctuating around the 1.08 level, ultimately losing an initial boost from the German Ifo data. The German Ifo data was stronger than the previous figures and generally exceeded expectations. A few ECB speakers made statements, but they offered little new information.
- GBP saw slight gains but stayed within a narrow range around the 1.29 mark as market participants anticipated the latest UK inflation data.
- JPY strengthened as USDJPY continued to retreat from resistance near the 151 level, falling below the 150 threshold. Its strength was further supported by a reduction in yield differentials, with UST yields declining.
- AUD gained, supported by a positive risk environment and a budget projecting a AUD 42.1 billion deficit. AUDUSD ranged from 0.6279 to 0.6325, with focus on expected 2.5% inflation data.
- Major economic data: UK Inflation Rate, US Durable Goods Orders, US Fed Kashkari Speech, US Fed Musalem Speech, BoC Summary of Deliberations
Commodities:
- Oil prices increased due to a significant US crude stockpile drop and potential Russia-Ukraine ceasefire. WTI exceeded $69, Brent neared $73. A 4.6 million barrel decline was reported, possibly the largest since November, pending Wednesday's official data.
- Copper futures on Comex hit a record high, driven by expected import tariffs and shipment halts from Chile. Prices rose to $5.2255 per pound, surpassing the previous record, following Glencore Plc's suspension of shipments from its Altonorte smelter due to a furnace issue.
- Gold held steady near its record high as US consumer confidence fell sharply, hinting at economic trouble. Bullion traded around $3,021 an ounce after a 0.3% rise, with the confidence drop to a four-year low in March boosting gold's appeal as a safe haven amid trade war and price concerns.
Fixed income:
- Treasuries rose, reversing losses after consumer confidence hit a four-year low. Front-end yields fell, steepening the curve amid trade war concerns. Strong demand for 2-year notes supported the rally. The 10-year yield was around 4.31%, outperforming European bonds, as swaps anticipated more Fed easing.
For a global look at markets – go to Inspiration.