
Access all our platforms from a single account.

Global Market Quick Take: Asia – July 25, 2025

Key points:
- Macro: ECB holds rates after 8 rate cuts
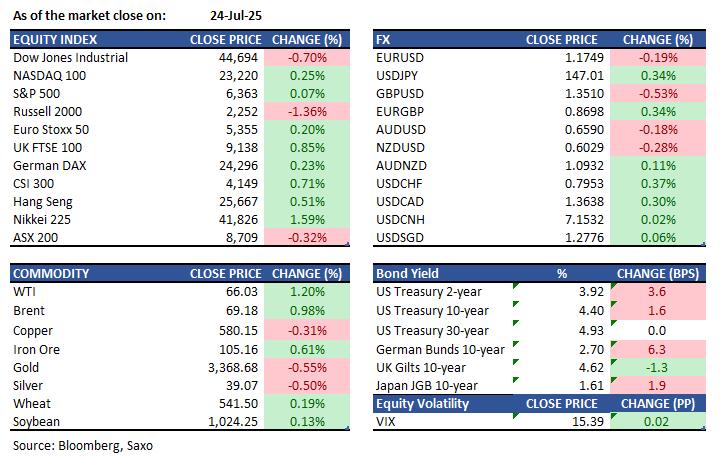
- Equities: S&P 500, Nasdaq hit records, rising on Alphabet's strong earnings
- FX: USD strengthened; US mixed data; EUR volatility in trade discussions
- Commodities: Gold stayed down but was on track for a modest weekly gain
- Fixed income: European bonds fell as the ECB tempered rate cut expectations for September
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- ECB held rates steady in July, ending its easing cycle after eight cuts. The main rate stays at 2.15%, with inflation hitting the 2% target in June. Policymakers are cautious amid trade uncertainties and potential U.S. tariffs. President Lagarde said the ECB is “in a good place” but noted challenges in assessing tariff impacts.
- Core consumer prices in Tokyo's Ku-area increased by 2.9% in July 2025, below the expected 3% but above the BOJ's 2% target, raising expectations for a rate hike. The BOJ meeting next week may see an upward inflation forecast revision, despite earlier growth concerns due to US tariffs. A new US-Japan trade deal, with a 15% tariff on Japanese exports, has eased some economic uncertainty.
- US initial jobless claims fell by 4,000 to 217,000 in the third week of July, defying expectations of a rise to 227,000 and marking the sixth consecutive decrease. Outstanding claims edged up to 1,955,000, slightly below expectations, indicating slowed hiring momentum despite low unemployment.
- S&P Global US Composite PMI increased to 54.6 in July 2025 from 52.9 in June, marking the fastest growth in 2025 and the 30th consecutive month of expansion. The rise was led by strong services activity, while manufacturing output grew more modestly. Employment grew across the private sector, but business confidence fell due to concerns over federal spending cuts and tariffs.
- In June 2025, US new single-family home sales increased by 0.6% to 627,000 units, slightly above May's low of 623,000 but below expectations of 650,000. High mortgage rates and economic uncertainty continue to pressure the housing market.
Equities:
- US - S&P 500 and Nasdaq 100 reached new record highs, rising 0.1% and 0.2% respectively, fueled by strong Alphabet earnings. Alphabet shares increased 1% after surpassing Q2 expectations and boosting its 2025 capital spending forecast by $10 billion, positively impacting Microsoft, Nvidia, and Amazon. Conversely, Tesla fell 7.9% as CEO Elon Musk warned of tough quarters ahead. The Dow Jones dropped 270 points, affected by IBM's 8% revenue-driven decline and UnitedHealth's 4.7% drop due to a DOJ investigation. Markets also focused on President Trump's unexpected Federal Reserve visit, where he heightened pressure on Chair Powell regarding interest rates. Progress was reported in trade talks with the EU, Japan, and South Korea, though Trump stated tariffs wouldn't go below 15%.
- EU - European stocks rose on Thursday as investors evaluated trade and monetary policy prospects in the EU. The STOXX 50 gained 0.3% to 5,359, and the STOXX 600 increased by 0.3% to 552. The ECB kept interest rates steady, observing disinflation aligned with its forecasts and indicating that more economic insights are needed before clarifying policy, including a potential US trade deal and euro movements. Markets reduced expectations for rate cuts after ECB President Lagarde suggested they might not be needed. Additionally, reports suggested the US might lower EU tariffs to 15% amid progressing trade talks. BNP Paribas rose 0.4% after surpassing revenue and earnings expectations.
- HK - Hang Seng rose 0.5%, to 25,667 on Thursday, marking its fifth consecutive gain and reaching its highest level since November 2021. Chinese stocks climbed ahead of upcoming trade talks with the U.S. in Stockholm, though gains were tempered by concerns over the Fed policy meeting and President Trump's visit to the central bank. China will release H1 industrial profit data over the weekend after a slight previous decline. Notable movers included Akeso Inc. (6.9%), China Hongqiao (6.3%), Horizon Robotics (5.2%), Citic Ltd. (5.6%), and Pop Mart Intl. (4.1%).
Earnings this week:
Friday: Centene Corporation, HCA Healthcare
FX:
- USD strengthened, marking its first DXY gain this week as trade deal momentum slowed. Mixed US PMI data and a continued decline in Initial Jobless Claims were reported. President Trump's Federal Reserve visit had little impact, reaffirming his call for lower rates amid some disagreement with Powell.
- EUR softened slightly to 1.1750 with volatile movements but found partial support from ECB President Lagarde's comments on policy stability. Uncertainty persists in US-EU trade talks as the August 1st deadline nears, with EU readiness for tariffs worth EUR 93 billion on US goods if no agreement is reached.
- GBP dipped to 1.35 following weak UK PMI data with manufacturing in contraction and Services below estimates.
- JPY lost ground with USDJPY returning to the 147 handle against a stronger USD.
- Economic calendar - UK Retail Sales, EU ECB Survey of Professional Forecasters, Germany Ifo Business Climate, US Durable Goods Orders
Commodities:
- Oil stabilized after its biggest weekly gain, fueled by US trade talk optimism and tight diesel markets. WTI crossed $66 per barrel, while Brent hovered near $69. India, Brazil, and Mexico aimed to expand trade ties with the US.
- Gold held its decline but remained on track for a modest weekly gain, as strong US jobs data supported the view that the Fed will hold rates next week. Spot gold was steady at $3,369.67 an ounce, up 0.6% this week. Silver and palladium were flat, while platinum edged higher.
Fixed income:
- Treasuries fell again as US labor market data led traders to reassess the Fed's rate cut plans. Yields rose about three basis points, particularly in shorter maturities sensitive to policy changes. Rate swap bets on Fed cuts now expect 42 basis points by year-end, with the first full cut by October. European bonds dropped after the ECB lessened September rate cut expectations, pushing short-term yields to a two-month high. Markets see a 25% chance of a 25bps cut in September, down from 40% on Wednesday. The two-year yield increased 7 basis points to 1.92%, the highest since May 15, with its biggest daily selloff since early June.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.