
Access all our platforms from a single account.

Global Market Quick Take: Asia – January 17, 2025

Key points:
- Macro: UK economy gains 0.1% in Nov after contracting 0.1% in previous 2 months
- Equities: TSMC revenue and profit exceed estimates; ADR rises 3.9%
- FX: JPY strengthens to 155 against USD on BoJ rate hike expectation
- Commodities: Gold hit $2,715 on Fed cut expectations and geopolitical easing
- Fixed income: Mid-term maturities led the gains in Treasuries
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- UK GDP gained 0.1% in November, missing the market estimate of 0.2%, after contracting by 0.1% in September and October.
- The key event of the day was Fed Governor Waller's dovish remarks, suggesting that a rate cut in March is still possible and that three or four cuts could occur this year based on data. This pressured the dollar, boosted Treasuries, and temporarily supported stocks.
- US retail sales came in weaker than expected at 0.4% vs 0.6% est while US Philly Fed Business Index (Jan) printed the highest figure since April 2021 at 44.3 vs. Exp. -5.0.
Equities:
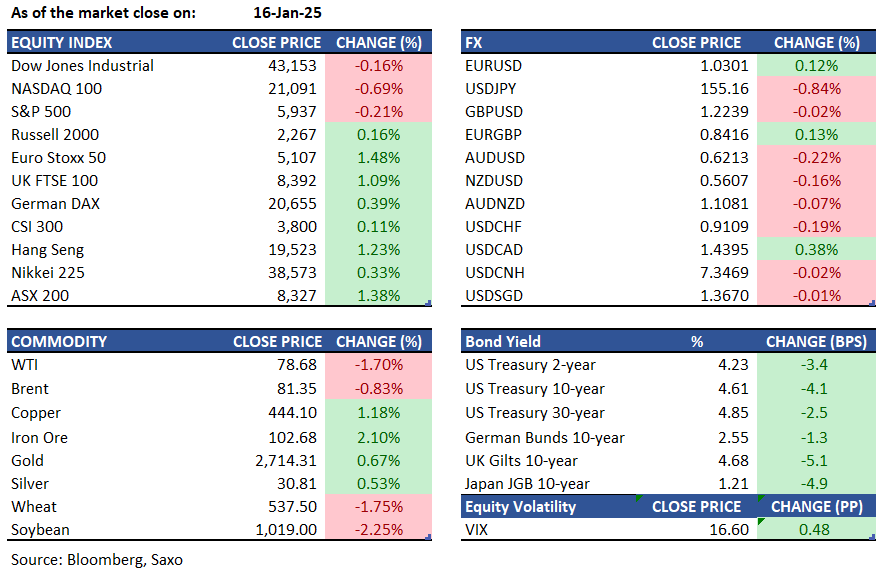
- US - In the afternoon session, US stocks declined as major tech shares retreated. The S&P 500 fell 0.1%, the Nasdaq dropped 0.5%, and the Dow Jones decreased by nearly 100 points, or 0.2%. Apple and Tesla weighed on the indexes, falling 3.6% and 3.9% respectively. Meanwhile, Morgan Stanley rose 3% on strong fourth-quarter results.
- TSMC's December-quarter revenue rose 38.8% to NT$868.46 billion, and net income increased 57.0% to NT$374.68 billion, surpassing analyst estimates due to the AI boom. TSMC ADR rose 3.9% to $214.79.
- Germany - DAX rose 0.3% to 20,634, hitting record highs on strong corporate results and rate cut bets. Top performers were Rheinmetall (+4.5%), Zalando (+2.4%), and Airbus (+1.9%).
- Hong Kong - HSI rose 1.2% to 19,523, its third consecutive gain, driven by Fed rate cut bets and potential Chinese RRR cuts. Gains were limited by caution ahead of key Chinese economic data releases, despite US tech control concerns being largely overlooked.
FX:
- USD remained stable, initially rising to 109.40 before falling due to dovish comments from Fed Governor Waller, who suggested possible rate cuts if inflation expectations are met. This led the DXY to drop to 108.820, stabilizing around 108.95.
- JPY outperformed in the G10, with USDJPY dropping to 155.11 from a high of 156.53, driven by rising expectations of a BoJ rate hike next week. Money markets are pricing an 80% chance of a 25bps hike.
- CAD, AUD, and NZD were G10 underperformers due to broader macro factors. The AUD was influenced by employment data, which exceeded expectations despite a rise in the unemployment rate to 4.0%. For CAD, BoC Deputy Governor Gravelle warned that a Trump tariff on exports could significantly harm economic growth.
- EUR and CHF gained slightly, GBP was flat. UK GDP missed expectations, pressuring Bunds. ECB Minutes were uneventful, and German CPI was revised higher. GBPUSD ranged from 1.2176 to 1.2260, and EURUSD from 1.0261 to 1.0314.
Commodities:
- WTI crude fell below $79 as markets reacted to US sanctions on Russian oil and speculation of Trump easing restrictions. India and China seek extra Saudi supplies, while Trump's team considers strategies benefiting Russian oil and boosting US production. Brent crude oil fell to $81.2.
- Gold rose to $2,715, a two-month high, on Fed rate cut expectations due to weak retail sales and rising unemployment. Lower rate expectations in the UK and Eurozone, plus an Israel-Hamas ceasefire, further supported prices.
- European natural gas fell to €46/MWh despite increased demand from colder weather. Storage is lower than last year but not critically low. Colder temperatures and weak wind power will raise gas demand. The EU may ban Russian LNG imports amid potential new sanctions.
Fixed income:
- Treasuries extended Wednesday's post-CPI gains after Fed's Waller suggested the possibility of three or four rate cuts this year, depending on data, and didn't rule out a March cut. Mid-term maturities led the gains, marking the largest two-day rise of the 2s5s30s butterfly since July 2023. Treasury yields dropped 3 to 5 basis points across the curve, as traders anticipated further Fed easing.
For a global look at markets – go to Inspiration.