
Access all our platforms from a single account.

Asia Market Quick Take – 19 November, 2026

Key points:
- Macro: Oct FOMC minutes reinforce December hike expectations
- Equities: Nvidia fell for fifth straight day; Moody’s lowered outlook to stable
- FX: USD strengthens on hawkish Fed; EUR hits 19‑month low, AUD slides on weak jobs
- Commodities: Copper plunges 5.7%; gold tumbles over 3% to lowest in over a year
- Fixed income: Treasuries rally on risk-off, long end leads; curve flattens
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- Fed hawkishness intensifies: Fed Governor Christopher Waller called for a half-point rate hike at the December meeting, citing annualised core inflation running near 3.5% over the past three months — well above the 2% target. Danske Bank revised its Fed call, now forecasting three additional hikes bringing the policy rate to 4.50%–4.75% by March 2027.
- FOMC October minutes (hawkish): Minutes from the October FOMC meeting reinforced expectations for a December rate hike, weighing on risk sentiment and contributing to the Nvidia post-earnings rally fizzling out.
- US Housing Starts (Oct): Housing starts rose 9.9% month-on-month to a 1.309 million annualised rate, beating the 1.250 million consensus. However, building permits fell 7.4% to 1.295 million, well below the 1.375 million estimate, signalling a weak pipeline ahead.
- UK CPI (Oct): UK annual inflation climbed to a one-year high of 3.6% in October from 3.5% in September, driven primarily by transport and motor fuel costs, adding pressure on the Bank of England.
- Geopolitics — Xi-Trump-Putin summit: Presidents Xi, Trump and Putin convened in China for high-stakes talks. Xi and Putin jointly criticised trade barriers ahead of the summit, while Trump and Putin are reportedly planning a separate bilateral meeting.
- Japan 20-year JGB auction: Demand was notably weak, with a bid-to-cover ratio of 3.64 versus 5.84 at the prior auction and a 12-month average of 3.92, reflecting reduced appetite for long-duration amid rising inflation and rate expectations.
Equities:
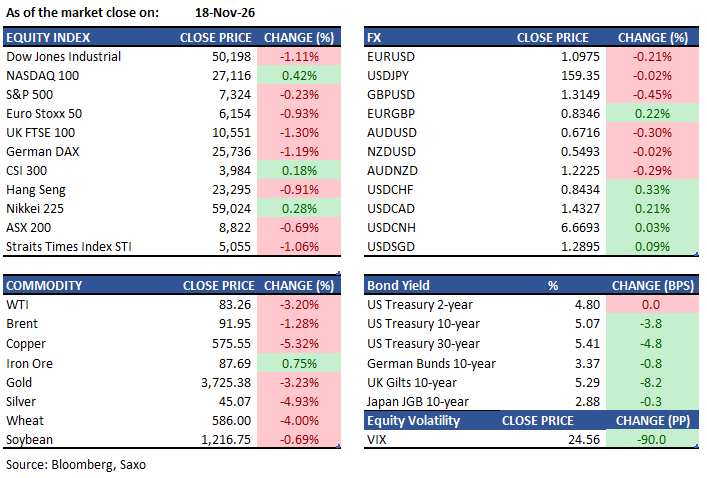
- US: US equities closed mixed on Wednesday. The Dow fell 1.1% to 50,198, the S&P 500 slipped 0.2% to 7,324 — its fifth consecutive down session — while the Nasdaq Composite gained 0.4% to 24,430 as tech outperformed. Nvidia fell ~3% as its post-earnings rally fizzled despite a strong Q4 revenue outlook of $126–134 billion and Moody’s revises Nvidia outlook to stable from positive after Jensen Huang’s sudden exit, citing lack of succession plan; the stock is down ~24% this month. TJX rose ~5% after Q3 comparable sales beat at +4% vs. +3% estimated. UnitedHealth declined 10% sharply after new rule toughens oversight of Medicare. After hours, Palo Alto Networks surged ~9% after beating Q1 estimates and raising full-year guidance, also announcing a $4.5 billion all-stock acquisition of Applied Compute. Nasdaq 100 futures rose ~0.9% in Asia hours.
- EU: European equities fell for a third consecutive session on Wednesday. The Stoxx 600 dropped 1.0% to 644.05, the DAX fell 1.2% to 25,736 — its fourth straight decline — the FTSE 100 lost 1.3% to 10,551, and the CAC 40 slid 0.9% to 8,147. Mining stocks led losses as copper plunged over 5%; the basic resources subindex fell 4.7%, its worst session since May. Antofagasta, Glencore and Endeavour Mining each fell more than 6%. SAP dropped 3.8%, the largest drag on the DAX and Stoxx 600. HSBC was the biggest drag on the FTSE 100, falling 2.1%. Chip stocks partially recovered on Nvidia's revenue outlook, with ASML, STMicroelectronics and Infineon each gaining over 2.5%.
- Asia:The Hang Seng stands at 23,295, the Nikkei 225 at 59,024, the Kospi at 5,067 and the STI closed Wednesday at 5,055 (down 1.1%). In Hong Kong, Tencent ADR fell 2.4% after reporting Q3 revenue of 207.3 billion yuan, missing the 210.5 billion yuan estimate, with operating profit diving 7% and capex surging to 81.4 billion yuan — swinging the company to a net debt position. Alibaba is due to report results Thursday after the close. The Nasdaq Golden Dragon China Index fell 1.3% on Wednesday. Japan's TOPIX Banks Index opened down 2.1% Thursday, with MUFG falling 3.2%. The STI's worst performer on Wednesday was Frasers Logistics & Commercial Trust, down 5.1%, while Jardine Matheson gained 2.4%. The ASX 200 fell 1.1% in early Thursday trade, led by BHP and Rio Tinto tracking copper lower. Kospi 200 futures closed down 1.4% on Wednesday.
Earnings this week:
- Thursday – PDD, Walmart, Alibaba, Futu, Intuit
FX:
- USD strengthened broadly on Wednesday, driven by hawkish Federal Reserve signals. Fed minutes showed nearly all officials agreed further rate hikes would likely be needed "in the months ahead," and Fed Governor Christopher Waller called for the Fed to consider a larger 50bp hike at its December meeting.
- EUR fell to a fresh 19-month low of 1.0960 intraday before recovering slightly to close at 1.0975. Options traders remained relatively calm, with one-week risk reversals showing a bearish but lower-conviction skew. Loomis Sayles shorted the euro, citing France's political risks as a persistent headwind.
- GBP was the weakest G10 performer, down 0.45%, reflecting broad dollar demand with no specific UK catalyst.
- Scandinavian currencies saw the largest G10 moves, with USDNOK up 0.74% and USDSEK up 0.43%, consistent with risk-off sentiment and commodity weakness.
- USDJPY was nearly flat at 159.35, with Bloomberg's FX macro model turning neutral on the yen after a prolonged bearish bias.
- AUDUSD trades near 0.669, down ∼3.5% over two weeks. A weak October jobs report (unemployment 4.9%, employment –43.5k) drove today’s drop, dovish RBA repricing, record shorts and bearish options skew.
Commodities:
- Copper fell 5.7% on the LME on Wednesday to $12,471 per tonne — the lowest since April — in a broad selloff across London, New York and Shanghai as bullish investors unwound AI-linked bets and sentiment turned outright bearish. Tin and nickel also fell sharply. European mining stocks were among the hardest hit, with Antofagasta, Glencore and Endeavour Mining each falling over 6%.
- Gold fell more than 3% on Wednesday to $3,725/oz — the lowest since October 2025 — as hawkish Fed rhetoric from Waller and the FOMC minutes reinforced rate hike expectations. The move was described as a potential capitulation, with investors selling gold to cover losses elsewhere. Silver also declined sharply.
- Oil declines: Brent crude fell to $91.95/barrel and WTI to $83.26/barrel on Wednesday, down roughly 0.7–1.9% on the session. The decline in oil provided some relief to bonds, partially offsetting the hawkish Fed pressure on Treasuries. European benchmark gas also fell 2.8%.
Fixed income:
- Treasuries advanced with gains led by longer tenors as equities weakened. The 10-year yield settled at 5.072%, the 2-year at 4.808% and the 30-year at 5.413%. A solid $16 billion 20-year bond auction that stopped on the screws preserved the curve-flattening move. Options flow targeting a move in the 10-year yield toward 4.85% was also notable.
- September TIC data showed foreign holdings of US Treasuries fell by $75.5 billion — the largest monthly drop since March — to $9.24 trillion, the lowest in a year. China and France led the decline, adding to concerns about demand for US government debt at elevated yield levels.
- Japan's 20-year government bond auction saw a bid-to-cover ratio of 3.64, well below the prior auction's 5.84 and the 12-month average of 3.92, reflecting reduced appetite for duration amid rising inflation expectations. Separately, French borrowing costs reportedly reached their highest level in more than two decades, with credit market participants flagging broader fixed income stress as rates reprice higher globally.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.