
Quick Take Asia

Global Market Quick Take: Asia – April 11, 2025

Macro 6 minutes to read


Key points:

  • Macro: China tariffs are now at 145%, US CPI came in weak at 2.4% vs 2.6% est
  • Equities: S&P 500 fell 3.4%, with Tesla dropping 10%
  • FX: USD selling boosted CHF and EUR to biggest gains since 2015
  • Commodities: Gold reaches new record $3,200 amid recession fears
  • Fixed income: Yield curve sharply steepens

------------------------------------------------------------------

0411

Disclaimer: Past performance does not indicate future performance.

Macro:

  • The White House stated that US tariffs on China now total 145% after the latest hike. CNN reported the 125% "reciprocal" tariff announced by Trump adds to the existing 20% tariff. The Trump Administration may delist Chinese public company shares from US exchanges, with incoming SEC chair Paul Atkins likely to address this upon taking office, according to FBN's Gasparino.
  • US inflation dropped to 2.4%, the lowest since September, from 2.8% in February, below the forecast of 2.6%. Gasoline and fuel oil prices fell, while natural gas prices rose. Inflation eased for shelter, used cars, and transportation. Food inflation increased. The CPI decreased by 0.1% month-on-month, the first drop since May 2020, against expectations of a rise. Core CPI came in at 2.8% yoy vs 3% est.
  • US initial jobless claims rose by 4,000 to 223,000, meeting expectations and staying at low levels since March. Continuing claims fell by 43,000 to 1,850,000, below the expected 1,880,000, showing employment progress.
  • China's consumer prices fell by 0.1% year-on-year, missing the expected 0.1% rise, marking a second monthly decline amid the US trade dispute. This drop was milder than February's 0.7% fall, due to slower food price declines with rising pork prices and recovering fresh fruit costs.

Equities: 

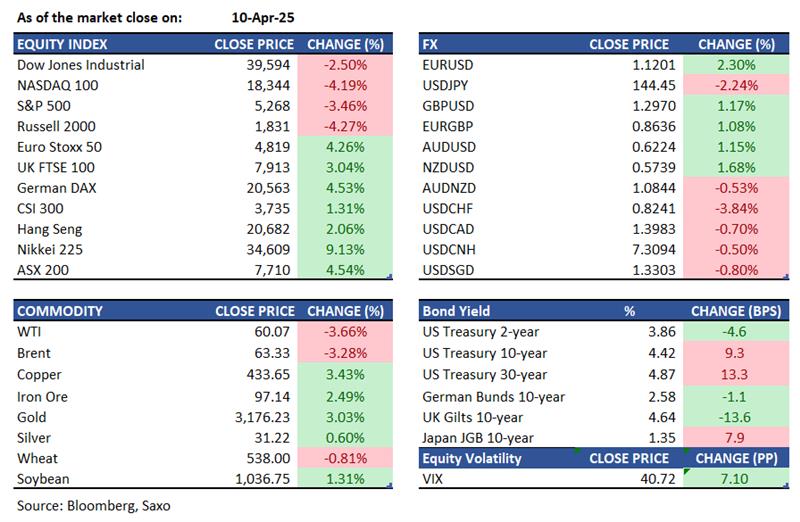
  • US - US stocks continued their decline on Thursday, erasing much of the previous day's gains as the US raised tariffs on China, heightening economic uncertainty and recession fears. The S&P 500 dropped 3.4%, the Dow lost over 1,000 points, and the Nasdaq fell 4%, with tech giants particularly affected by risk sentiment. The White House increased tariffs on China to 145% from 125%, but did not address potential tariffs on base metals and chemicals. Growth concerns overshadowed yesterday's rally, despite disinflation signs in the CPI report. Leading the downturn, Tesla fell 10%, with Nvidia, Apple, and Amazon dropping over 6.5%. Oil producers Chevron and Exxon Mobil also declined by 6% as energy prices fell.
  • EU - European bourses surged on Thursday, with the STOXX 50 up 4.4% and the STOXX 600 rising 4%, driven by tariff suspensions from both the EU and the U.S., alleviating fears of economic slowdown and inflation. The EU announced a 90-day pause on new U.S. tariffs to facilitate trade talks, following President Trump's decision to lower tariffs for non-retaliating countries. The U.S. now has a 10% baseline tariff on all imports, including the EU, with exemptions for sectors like semiconductors, copper, lumber, pharmaceuticals, metals, energy, and minerals, while autos face a 25% tariff. Banking, technology, and industrial stocks led the rally.
  • HK - The Hang Seng rose 417 points, or 2.1%, to 20,682 Thursday, achieving its third consecutive gain as traders downplayed Washington's tariff increase on Chinese goods. China's White Paper signalled readiness to engage with the U.S., promising firm measures to defend interests. Sentiment improved with reports of Chinese leaders discussing market support and regulators considering calming strategies. March consumer prices dropped only 0.1% year-on-year, against expectations, lifting the mood. All sectors gained, driven by record HKD 35.5 billion mainland buying via Stock Connect. Tech and EV shares led the rally, including Kuaishou (4.7%), Trip.com (4.0%), Li Auto (5.6%), and Geely (4.9%).

Earnings this week:

Friday: JPMorgan Chase (JPM), Morgan Stanley (MS), Wells Fargo (WFC), Bank of New York Mellon (BK), BlackRock (BLK)

FX:

  • USD experienced significant losses as safe havens, particularly the CHF, surged by about 4% to below 0.82 against USD due to uncertainty from President Trump's tariff changes and weaker-than-expected CPI data. DXY dropped 1.8% to 101.5.
  • EUR rallied, surpassing the 1.12 level, aided by the dollar's decline and the EU's agreement on a 90-day pause in countermeasures against the US, pending satisfactory negotiations.
  • GBP steadily advanced, nearing the 1.30 level, despite limited UK-specific catalysts, with attention now on upcoming UK economic data.
  • JPY strengthened, with USDJPY testing the 144 level due to haven flows and the dollar's weakness.
  • China's inflation was cooler than expected, and CNH strengthened without a clear driver, following reports of the PBoC asking state banks to cut dollar purchases.
  • Major economic data: UK GDP, US PPI, US Michigan Consumer Sentiment Preliminary

Commodities:

  • Oil futures fell again after Wednesday's relief rally amid US trade policy shifts. WTI dropped 3.7% to near $60, flirting with a four-year low, while Brent closed near $63. Previous session saw the largest intraday gain since October.
  • Gold hit a fresh record as tariff concerns drove investors to safe havens. Bullion rose above $3,200 an ounce, surpassing the previous session's record, which saw a more than 3% gain for the second consecutive day.

Fixed income:

  • Treasuries were mixed, with a sharply steeper curve. 2-year yields fell about 8bp, while the 30-year sector rose up to 12bp. Price action intensified after weaker-than-expected CPI, as a significant concession built in the long end for the $22 billion 30-year bond reopening.


For a global look at markets – go to Inspiration.


Disclaimer

Confidentiality and Usage:
You may not reproduce, distribute, or transmit this material or any portion thereof without prior written permission from Saxo.

Nature of Information:
The information provided herein is based on current market conditions and analysts' opinions, which may reflect personal views of the author, and are subject to change without notice. This material does not include a record of any trading prices, or an offer of, or solicitation for, or endorsement to enter into any transaction in any investment product. Any forecast on the economy, markets and economic trends of the markets provided is not necessarily indicative of the future or likely performance of the investment product subject of this material.

Responsibility and Liability:
Saxo accepts no liability for any use that may be made of these comments or for any consequences that arise from such use. Saxo does not guarantee the accuracy or completeness of any information provided and assumes no liability for any errors, omissions, losses, or damages resulting from the use of this information.

The information provided in this material is solely for information only. It is intended for general circulation and does not take into account the specific investment objectives, financial situation or particular needs of any particular person. Accordingly, it should not be relied on or treated as a substitute for specific advice concerning specific situations of any person. Please seek advice from a financial adviser regarding the suitability of any investment product taking into account your specific investment objectives, financial situation or particular needs before you make a commitment to purchase an investment product. In the event that you choose not to seek advice from a financial adviser, you should consider whether any investment product mentioned in this publication is suitable for you.

Notwithstanding the above, insofar as any information provided herein contains research analyses or reports concerning any investment product authored by any foreign research house and is issued or promulgated to a person in Singapore who is not an accredited investor, expert investor, and/or institutional investor, Saxo Capital Market Pte. Ltd. accepts legal responsibility for the contents of this material to the extent required by law. Recipients of such material are to contact Saxo Capital Markets Pte. Ltd. in respect of any matters arising from, or in connection with, this material.

Risk Disclosure:
Trading in investment products involve significant risk, including the risk of losing your entire investment. Historical returns are not a guarantee of future returns. Prices can both rise and fall, and there is a risk that you will not get back the money you invested.

Conflicts of interest:
The author may hold positions in the investment products mentioned. The author does not own positions in the underlying investment product exceeding 0.5% of its market capitalisation, save as otherwise declared. The author is not permitted to trade the mentioned investment products within the first 24 hours after the publication of this article.

Saxo maintains partnerships with companies that compensate Saxo for promotional activities conducted on its platform. Additionally, Saxo has agreements with certain partners who provide retrocession contingent upon clients purchasing specific investment products offered by these partners. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.

Publication details:
If any listed companies are the subject of the material, the content has not been submitted to the companies in question prior to publication.

Please refer to our full disclaimer and notification on non-independent investment research for more details.

Saxo Markets
88 Market Street
CapitaSpring #31-01
Singapore 048948

Contact Saxo

Singapore
Singapore

Saxo Capital Markets Pte Ltd ('Saxo Markets') is a company authorised and regulated by the Monetary Authority of Singapore (MAS) [Co. Reg. No.: 200601141M ] and is a wholly owned subsidiary of Saxo Bank A/S, headquartered in Denmark. Please refer to our General Business Terms & Risk Warning to consider whether acquiring or continuing to hold financial products is suitable for you, prior to opening an account and investing in a financial product.

Saxo is part of the J. Safra Sarasin Group.

Trading in financial instruments carries various risks, and is not suitable for all investors. Please seek expert advice, and always ensure that you fully understand these risks before trading. Trading in leveraged products such as Margin FX products may result in your losses exceeding your initial deposits. Saxo Markets does not provide financial advice, any information available on this website is ‘general’ in nature and for informational purposes only. Saxo Markets does not take into account an individual’s needs, objectives or financial situation.

The Saxo trading platform has received numerous awards and recognition. For details of these awards and information on awards visit www.home.saxo/en-sg/about-us/awards.

The information or the products and services referred to on this website may be accessed worldwide, however is only intended for distribution to and use by recipients located in countries where such use does not constitute a violation of applicable legislation or regulations. Products and Services offered on this website are not intended for residents of the United States, Malaysia and Japan. Please click here to view our full disclaimer.

This advertisement has not been reviewed by the Monetary Authority of Singapore.

Apple and the Apple logo are trademarks of Apple Inc, registered in the US and other countries and regions. App Store is a service mark of Apple Inc. Google Play and the Google Play logo are trademarks of Google LLC.