
Access all our platforms from a single account.

Asia Market Quick Take – 20 October, 2026

Asia Market Quick Take – 20 October, 2026
Key points:
- Macro: Canadian inflation rises 3.1%, below forecasts of 3.2%
- Equities: Tech rebound; Amazon rises 5% after Morgan Stanley upgrade
- FX: USD steady with bullish momentum; EUR lags on politics, AUD outperforms
- Commodities: Precious metal remains under pressure while oil stays elevated
- Fixed income: Credit spread widens and treasury yield rose across the curve
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- Canada’s inflation edged up to 3.1% in September 2026 from 3.0%, below the 3.2% forecast, as gasoline jumped 27.8% and shelter costs rose, while ex-gas CPI slowed to 2.2% and BoC trimmed-mean core stayed at 1.8%.
- US Energy Secretary Chris Wright said Persian Gulf oil flows are back to about 80% of pre-war levels, though refined products remain constrained. The US is allowing sanctioned tankers from the roughly 1,600‑vessel “dark fleet” to re-enter legal trade. Iran is tightening control of the Strait of Hormuz amid ship attacks, while Saudi–Houthi and Russia–Ukraine strikes on energy infrastructure have resumed.
- China’s GDP grew 4.5% year-on-year in Q3 2026, beating forecasts and up from 4.3%, helped by policy easing and strong AI-related, high-tech, and EV exports. Stronger September data lifted year-to-date growth to 4.6%, within the lower end of the 4.5%–5% target, though authorities warned of weak domestic demand and global risks.
- Japan’s 10-year bond yield slipped toward 2.9% as PM Sanae Takaichi vowed to rein in debt issuance and maintain fiscal discipline, while BoJ Governor Kazuo Ueda said underlying inflation is near the 2% target on a moderate recovery and tight labor market.
- The NAHB Housing Market Index fell to 29 in October 2026 from 32, the lowest since June 2012 and below forecasts, as current and expected sales and buyer traffic all weakened. Price cuts spread to 43% of builders, with an average 6% reduction, amid high mortgage rates, elevated costs, and poor affordability.
- NEC Director Kevin Hassett said inflation, once “completely under control,” now “needs some work,” though it’s unclear if this is a trend or a blip. With the Fed in blackout before the October 28 decision, markets see a hold now but are rebuilding 2027 hike bets.
Equities:
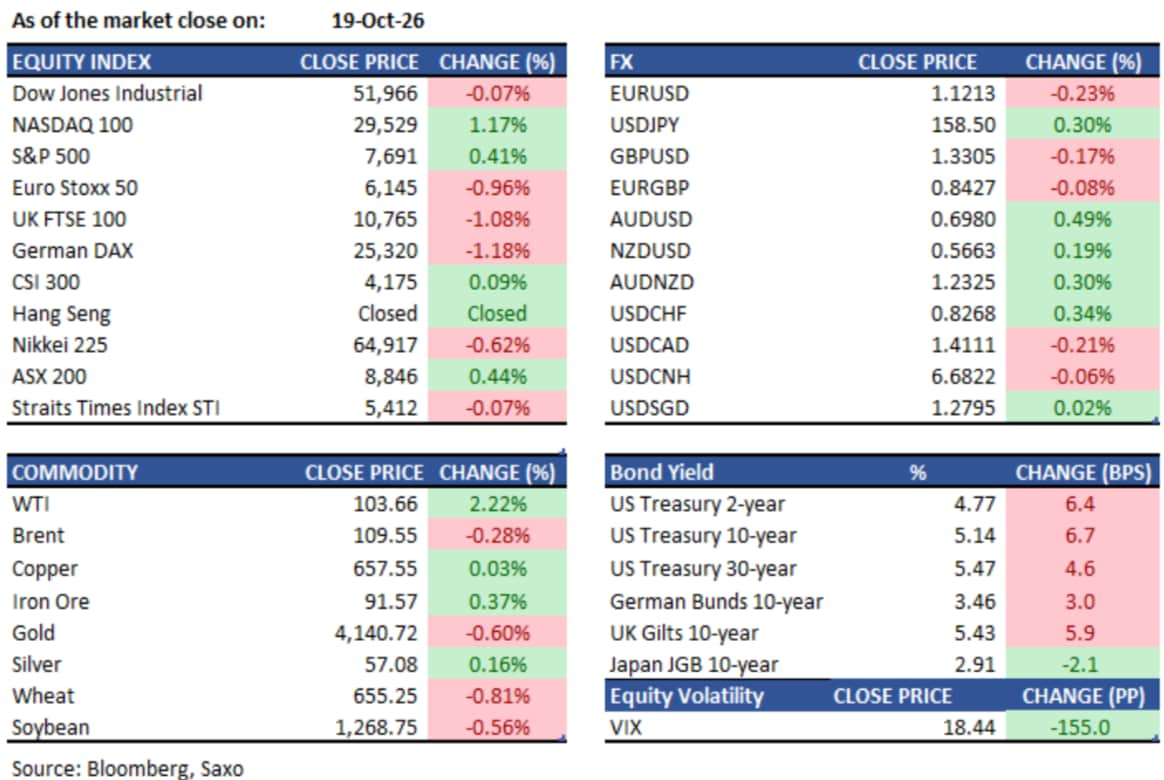
- US (Monday close): S&P 500 +0.4% to 7,690.73; Nasdaq 100 +1.2%; Dow Jones flat at 51,996. Tech and consumer discretionary led gains. The Philadelphia Semiconductor Index +1.6%, snapping an eight-session losing streak — its longest since 2008 — after wiping out ~$2.3 trillion in market value. Amazon surged 5.0%, its best day since July, after being named a top pick at Morgan Stanley. Western Digital/SanDisk +6.1%. After hours: W.R. Berkley fell ~3% on a revenue miss; Crown Holdings beat on EPS ($2.39 vs $2.26 est.) and revenue.
- EU (Monday close): Stoxx 600 -0.8% to 639.56; DAX -1.2% to 25,319.77; FTSE 100 -1.1% to 10,764.69; CAC 40 -1.1%, underperforming peers after weekend riots in France. Banks were the worst-performing sector — BNP, SocGen and Credit Agricole all fell more than 2%. HSBC led Stoxx 600 declines (-2.2%); Aker ASA dropped 7.1%. The CAC 40 now trades at its steepest discount to the DAX since early 2009. Technology was the only sector in the green.
- Asia (Tuesday open): Asian equities opened lower, shrugging off Wall Street's chip-led rebound. MSCI Asia Pacific -0.3%, led by declines in South Korea. Note: Hong Kong markets are closed today for a public holiday. Nikkei 225 opened softer, tracking global tech weakness, though commodity-linked names including mining and oil provided some support. Kospi under pressure — the index has been technically oversold with forward P/E at record lows; Samsung and SK Hynix remain key drags following last week's rout. STI broadly steady. Australia's ASX 200 fell 1.1% to 8,748.50 in early trade, with BHP down as much as 2.3% after copper output slumped at its Chilean mines due to weather and lower ore quality. NAB slipped after announcing up to 2,500 job cuts. Indonesia's JCI extended losses following the MSCI warning. Nasdaq 100 futures +0.1%, offering modest relief.
Earnings this week:
- Tuesday: GE Aerospace, General Motors, 3M, Netflix, United Airlines, SpaceX, CATL
- Wednesday: Abbott, NextEra Energy, AT&T, CME Group, Danaher, Tesla, Meta, IBM, Lam Research, Texas Instruments, Philip Morris
- Thursday: Lockheed Martin, Nokia, Comcast, American Airlines, Bloom Energy
- Friday: American Express, Schlumberger
FX:
- USD was broadly steady on Monday and into early Tuesday, with the Bloomberg Dollar Spot Index flat and a key Fear‑Greed momentum gauge staying positive for a 24th straight day—the longest bullish streak in a year—despite reduced Fed hike expectations.
- EUR was the weakest G10 currency on Monday, dropping about 0.44% as French protests and Russia‑Ukraine tensions weighed, with EURUSD holding near 1.12 and only edging slightly higher early Tuesday.
- AUD was the G10 outperformer, rising roughly 0.33% to around 0.6973 and steady near 0.6984 this morning, with some analysts expecting a move back above 0.73 by year‑end on stronger copper demand and the prospect of further RBA hikes.
- USDJPY reversed earlier yen gains to finish Monday at 158.50 and is steady around 158.52 this morning; intervention fears are curbing fresh shorts, but most see the broader yen‑weakness trend intact.
- GBPUSD has edged up to around 1.3317, making sterling the strongest G10 pair so far today, while USDCAD is broadly flat after a brief CAD lift from headline CPI faded on softer core readings.
- In Asia, the yuan firmed on better‑than‑expected China Q3 GDP and a slightly stronger PBOC fixing, with USDCNH near 6.68, and the Korean won outperformed EM Asia as slowing foreign equity outflows supported USDKRW lower.
Commodities:
- WTI crude settled at $103.70/bbl, up $2.29 on the session, after Iran signalled it may assert control over the Strait of Hormuz. Brent slipped modestly from a five-month high. Oil's sustained rally above $100 is a key driver of the current inflation re-acceleration narrative and is weighing on risk assets globally.
- Gold fell approximately 0.6%–0.7% to around $4,136/oz as elevated bond yields and rising real rates (10-year US real yield up 4.6bps to 2.77%) weighed on the non-yielding metal. The path for gold remains clouded by the Fed's uncertain rate trajectory, with oil-driven inflation complicating the picture.
Fixed income:
- Treasuries sold off on Monday as the equity rebound sapped haven demand. Yields rose 6–8bps across the curve: the 10-year yield climbed to 5.14%, the 30-year rose to 5.48%, and the 1-year lifted to 4.47%. Traders rebuilt wagers on Fed hikes in 2027 while continuing to price a quarter-point increase in December. The 10-year real yield rose 4.6bps to 2.77%, up 85bps year-to-date.
- French government bonds extended losses following the weekend riots, with the selloff spilling into bunds and gilts. The CAC 40's discount to the DAX widened to its most since 2009, reflecting the depth of investor concern. Treasuries were pulled off their early session highs by the European bond weakness, with the two markets trading in tandem for much of the day.
- US HY CCC spreads hit a four-year high last week, with junk bond yields surging to an 18-month high and risk premiums jumping to a six-month high of 331bps. The selloff was compounded by two consecutive hotter-than-expected inflation readings. Asian HY spreads tightened modestly on Monday — the first tightening in more than a week — as chipmaker stocks snapped their losing streak.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.