
Access all our platforms from a single account.

Asia Market Quick Take – November 20, 2025

Key points:
- Macro: Fed minutes show officials were split during rate cut in October
- Equities: Nvidia rises 5% in post market after strong earnings
- FX: Yen down 1%; USDJPY above 157, highest since mid-Jan
- Commodities: Oil extends biggest weekly drop on rising US fuel inventories
- Fixed income: Front-end Treasury yields rise as Dec Fed cut bets fade
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- Federal Reserve officials were split on lowering the federal funds rate in October. Most favored further cuts for December, though some were skeptical about another 25bps cut. The Fed decreased the rate by 25 bps to 3.75%–4.00% in October 2025.
- The BLS will delay the November jobs report until after the Fed’s December meeting, clouding the policy outlook and raising odds of a hold. The October report is cancelled.
- BoC Deputy Governor Vincent stated that Canada's weak productivity is a systemic issue needing a coordinated approach, as it hampers addressing frequent economic shocks. He emphasized the importance of the link between rising labor costs and productivity in inflation assessments, according to Reuters.
- Japan is looking to compile an economic package worth more than 20 trillion yen ($129b) by this week to ease the pain of rising living costs.
- UK inflation fell to 3.6% in October 2025, its lowest in four months, meeting expectations. Housing and utilities saw slower price increases due to energy cap changes. Transport inflation stayed at 3.8%, but food and recreation rose. Monthly CPI rose 0.4%, and core inflation hit a six-month low of 3.4%.
- In August 2025, US exports rose $0.2 billion to $280.8 billion amid trade policy uncertainty. Service exports grew $0.8 billion, while goods exports fell $0.5 billion due to declines in consumer goods, industrial supplies, and automotive exports. A $2.4 billion increase in capital goods, especially computers, provided some offset.
Equities:
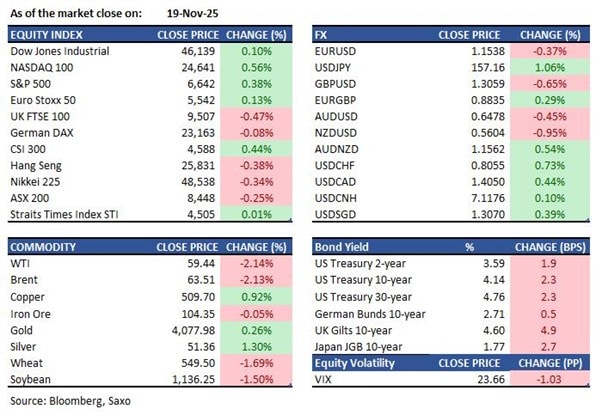
- US - Nvidia shares jumped over 5% in after-hours trading after reporting strong earnings, revenue, and an upbeat fourth-quarter forecast. CEO Jensen Huang said demand for its Blackwell chips is “off the charts.” Other chipmakers and AI-linked stocks gained, with AMD, Micron, Broadcom, and Palantir up 2.9%–4.1%. U.S. stocks closed higher Wednesday, rebounding from four days of losses as markets digested a mixed Fed minutes release. The S&P 500 rose 0.4%, Nasdaq 100 added 0.6%, and Dow edged up 0.1%. Retail results were mixed: Target fell 2.8%, while Lowe’s and TJX advanced.
- EU - European stocks edged higher Wednesday, breaking a four-day losing streak as investors weighed Fed policy signals and tech valuations. The STOXX 50 gained 0.3% to 5,552, while the STOXX 600 hovered near 563. Sentiment stayed cautious amid concerns over AI-driven overvaluation, with Nvidia’s earnings due after the U.S. close. AI-linked shares were mixed: ASML rose 2.5%, Infineon slipped slightly. Nokia plunged 7% after spinning off its AI unit following Nvidia’s $1 billion investment. Pharma stocks outperformed, with Roche, AstraZeneca, and Novo Nordisk closing higher. Markets remain focused on whether tech optimism can sustain amid tightening monetary conditions and valuation risks.
- HK - Hang Seng slipped 0.4% to 25,831 on Wednesday, marking a fourth straight decline and holding near a two-week low. Sentiment stayed weak after Wall Street’s sharp drop ahead of Nvidia’s earnings, FOMC minutes, and key U.S. jobs data. Inflation concerns grew as speculation mounted that Trump’s falling approval could trigger more fiscal spending. Diplomatic strains between China and Japan added pressure, while the HKMA reportedly tightened oversight of distressed loans amid property weakness. Losses were broad, led by tech and property. Xiaomi fell 4.7% on rising chip costs, while Pop Mart (-2.4%) and SMIC (-1.2%) also declined.
Earnings this week:
- Thursday
US: Walmart, Warner Music Group, Intuit
Asia: Webull
- Friday
US: BJ’s Wholesale Club
Asia: Meituan
FX:
- The yen fell 1% with all G-10 peers against the dollar, lifting USDJPY 1% to 157.03—its highest since mid-January—as BoJ Governor Ueda met cabinet ministers on the government’s accord and an adviser signalled no rate hike before March.
- GBPUSD slipped 0.7% to 1.3049 after UK inflation fell for the first time in seven months, with traders paying up for protection ahead of the Autumn Budget; EURUSD dropped 0.4% to 1.1536, and NZDUSD fell 0.9% to 0.5605 before the Aussie and kiwi pared losses on Nvidia’s strong revenue outlook.
Commodities:
- Oil extended its biggest weekly drop as US fuel inventories rose and investors braced for sanctions on two Russian producers. WTI January held above $59 after Wednesday’s 2% slide, Brent closed below $64, and government data showed gasoline and distillate stocks—including diesel—climbed for the first time in over a month.
- Gold extended its rebound, up 0.5% to $4,097.51 after a 0.3% rise, signalling firm demand despite a risk-on tone as tech rallies on Nvidia hopes; silver, platinum and palladium also gained.
Fixed income:
- Late weakness in Treasury futures lifted yields modestly, led by the front end, as traders pared bets on a 10 December Fed cut after the BLS said October employment data will be released with November’s on 16 December and hawkish October FOMC minutes reinforced the shift. January fed funds futures sold off, trimming December easing priced to about 6bp from 11bp, while a solid 20-year auction had little effect and a UK gilt selloff alongside US dollar strength added upward pressure to US yields.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance. The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.