
Access all our platforms from a single account.

Asia Market Quick Take – January 29, 2026

Key points:
- Macro: Fed holds rates at 3.5%-3.75% as expected
- Equities: S&P 500 traded above 7,000 briefly
- FX: Dollar peaks as Fed holds rates; US dismisses yen intervention concerns
- Commodities: Gold at record above $5,500; oil up third day
- Fixed income: Treasuries subdued; Fed holds rates
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- The Fed maintained rates at 3.5%–3.75% in its meeting for January 2026 after last year's cuts. Governors Miran and Waller wanted a 25bps cut instead. Economic growth is steady, with low job gains and stable unemployment amid high inflation. The Fed will monitor data for future rate changes. Chair Powell stated current rates support goals as the economy enters 2026 strongly.
- Bessent cut bets on US intervention, stressing the preference for a strong dollar and denying involvement in Japan's markets. Earlier, the dollar hit 2022 lows due to speculation and Trump's indifference. Tariff threats and shutdown fears contributed to the "sell America" trade.
- Bessent said there's no trade deal with South Korea until ratification and criticized the EU for freezing the deal during Trump's Davos speech. A South Korean adviser warned of possible US tariff hikes over future investment disagreements.
- The 30-year mortgage rate for loans up to $806,500 rose to 6.24% in the week ending January 23, causing an 8.5% drop in applications. Refinancing fell 15.7%, and thepurchase index decreased 0.4%. FHA refinance activity increased due to lower rates. Joel Kan of the MBA noted the market's sensitivity to rate changes.
Equities:
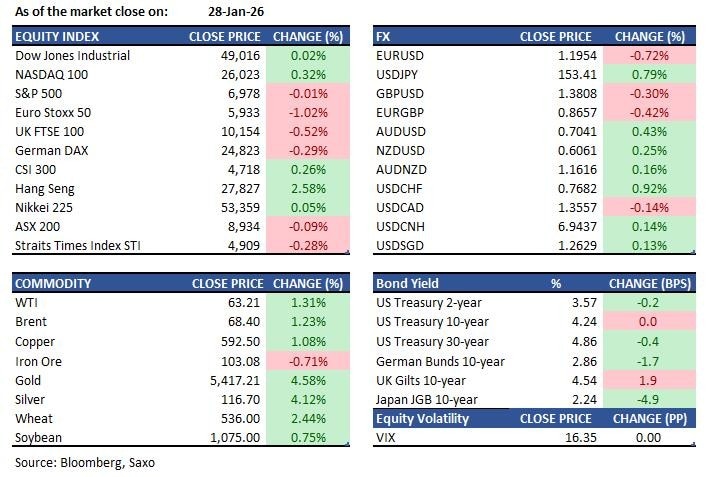
- US - The S&P 500 briefly topped 7,000 for the first time but ended slightly lower, alongside the Dow, while chip strength lifted the Nasdaq 100 by 0.2%. The Fed signalled balanced risks to inflation and employment, reinforcing expectations for two rate cuts this year. Texas Instruments surged 9.9% after strong results, boosting Micron and Intel. AT&T rose 4.7% following its results. In after hours, Microsoft reported earnings that beat estimates but fell 6.11% on AI spending surge of 66% and poor Azure growth. Meta rose 7% after strong earnings while keeping capex cost under control. Tesla also rose 1.7% despite weaker profit and EV sales figures as Musk announced end to Model S/X to make Optimus robots.
- EU - European stocks closed sharply lower Wednesday, extending early losses as weak earnings hit luxury and pharmaceutical shares. The STOXX 50 fell 0.9% to 5,940, while the STOXX 600 dropped 0.7% to 609. LVMH slid 7.3% after disappointing results, dragging the luxury sector lower, while Hermès fell nearly 3%. Pharma stocks also weakened, with Bayer and argenx down more than 3% each. ASML ended 1.7% lower after paring strong intraday gains driven by robust order data. Investors now look ahead to the Federal Reserve’s policy decision, with rates expected to remain unchanged.
- HK - Hang Seng Index surged 2.6%, to close at 27,827, marking its largest single-day gain since January 2 and reaching a four-and-a-half-year high. The uptick was supported by gold amid geopolitical tensions and a weak dollar. In corporate news, China approved the import of Nvidia’s H200 AI chips, and Busy Ming Group soared 75% on its Hong Kong debut, raising HKD 3.67 billion in its IPO. China Vanke's stock rose after strong backing from Shenzhen Metro, a major shareholder. Zijin Gold Intl. and China Hongqiao increased by 7.1%, while SMIC climbed 3.7%
Earnings this week:
- Thursday - Mastercard, Caterpillar, Nokia, Visa, Apple, Sandisk, SAP
- Friday - Verizon, American Express, CN, Chevron, ExxonMobil
FX:
- USD reached its daily high after the Federal Reserve kept interest rates steady, noting stabilization in the job market. Treasury Secretary Scott Bessent reinforced dollar strength by confirming no US intervention in the yen market, maintaining a strong dollar policy.
- USDJPY increased 1.2% to 154.05, marking its biggest gain since December 19. The Fed's decision to hold rates at 3.50%-3.75% came with positive remarks about job gains and unemployment. Powell commented at a press conference, with observers noting improved economic language since December.
- USDCAD steadied at 1.3584, following earlier gains after the BOC maintained rates. The BOC noted disruptions from US trade policies impacting Canadian growth. Elias Haddad suggested delaying market expectations for a BOC rate hike.
- EURUSD fell 1.2% to 1.1896, and GBPUSD declined 0.7% to 1.3750. ECB is assessing how a stronger euro affects inflation in its policy decisions.
- AUDUSD dropped 0.2% to 0.6996 amidst choppy trading, with Australia's core inflation suggesting persistent price pressures.
Commodities:
- Gold surged to a record above $5,500 an ounce, earlier hitting $5,596, as US dollar weakness and a broader flight from sovereign bonds and currencies extended a rally that saw bullion jump up to 3.2% early after a 4.6% leap—the biggest one-day gain since March 2020—while silver also set a recordbreaking above $119.
- Oil rose for a third day as President Donald Trump warned Iran to make a nuclear deal or face military strikes, heightening Middle East supply concerns, with WTI climbing towards $64 after a 1.3% advance to the highest since late September, and Trump saying US ships were ready to act “with speed and violence, if necessary.”
Fixed income:
- Treasuries were muted as the Fed kept rates unchanged and Chair Powell offered few new signals, with price action subdued even as the statement upgraded growth to “solid” and noted stabilising unemployment—hinting hawkishly—while Fed‑dated OIS was little changed, still pricing about 45bp of cuts by year‑end with the first fully priced for July.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance. The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.