
Access all our platforms from a single account.

Asia Market Quick Take – December 10, 2025

Key points:
- Macro: US job openings hit a five-month high
- Equities: Nvidia eased 0.3% as China limiting H200 purchases
- FX: EURJPY hits a record high above 182.50
- Commodities: Spot silver surges to a record high above $60
- Fixed income: US Treasuries fell, led by the front end and belly
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- France’s National Assembly approved next year’s social security bill by 247–234, boosting the odds of a year‑end budget and easing calls for Prime Minister Sebastien Lecornu to resign, with Lecornu saying the vote shows compromise is possible even as the main budget will be tougher and the government’s stance unchanged.
- US job openings rose to a five‑month high of 7.67 million in October while layoffs climbed to 1.85 million, the highest since early 2023, and hiring fell by 218,000, with Stephen Stanley saying the labour market is slowing but not as sharply as some alternative indicators suggest.
Equities:
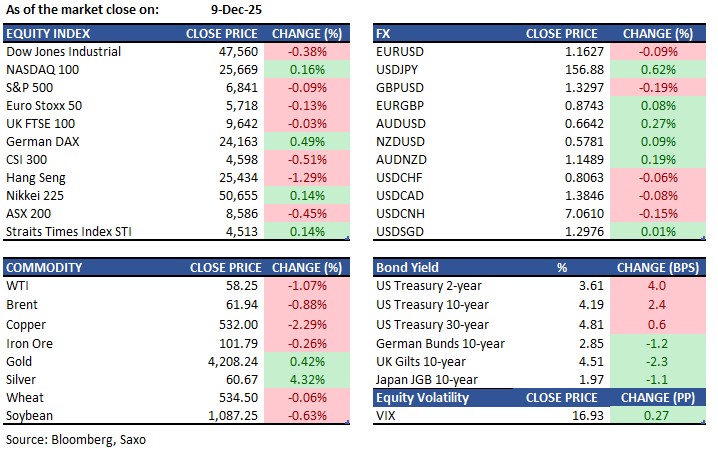
- US - U.S. stocks were flat Tuesday as traders digested labor data and headlines ahead of the Fed decision. The S&P 500 was little changed, the Nasdaq edged higher, and the Dow fell 0.3%. JPMorgan slid 4.7% after projecting 2026 expenses near $105 billion, pressuring bank peers. Job openings rose to about 7.67 million in October, reinforcing the Fed’s data-dependent stance while markets still price a 25 bp cut this week. Nvidia eased 0.3% on reports China may limit H200 purchases despite U.S. export clearance with a 25% surcharge. Home Depot lost 1.3%. Paramount (+0.5%) and Netflix (-0.1%) eyed Warner Bros. (3.8%).
- EU - European stocks slipped Tuesday, with the STOXX 50 down 0.1% and the STOXX 600 near flat, as traders stayed cautious ahead of Wednesday’s Fed decision. A 25 bp cut is widely expected, though the 2026 outlook remains hazy. EssilorLuxottica fell 5.7% after Warby Parker unveiled AI‑enabled glasses with Google, intensifying smartglasses competition. Thyssenkrupp dropped 7% on guidance pointing to a potential €800 million loss in 2026. Defense names rallied after reports German lawmakers will approve 29 procurement deals totaling €52 billion next week: Hensoldt +6.5%, Rheinmetall +4.1%, Leonardo +2.6%, BAE Systems +2.3%, Thales +2.6%.
- HK - Hang Seng fell 1.3%, to 25,434 Tuesday, hitting a two-week low as losses extended across sectors. Investors stayed cautious ahead of the Fed’s decision, with talk of a “hawkish cut” and uncertainty over Powell’s successor in 2026. Mainland shares eased before China’s November CPI and PPI data, keeping deflation risks in focus. U.S. President Trump said Nvidia can ship H200 chips to approved Chinese buyers. Sentiment improved slightly after the Politburo pledged stronger 2026 support, signaling proactive fiscal and loose monetary policy. Top laggards: Pop Mart (-5.4%), SMIC (-4.2%), Xiaomi (-3.0%), Meituan (-2.0%), China Resources Land (-3.9%).
Earnings this week:
- Wednesday: Oracle, Adobe, Chewy, Synopsys, Nordson
- Thursday: Costco, Broadcom, RH (Restoration Hardware), Lululemon
- Friday: Quanex Building Products, Johnson Outdoors
FX:
- The dollar edged higher after US job openings hit a five month high even as layoffs persisted. The yen lagged amid uncertainty over the BoJ’s path, while the euro trimmed losses after France approved a social security bill.
- USDJPY rose 0.7% to 156.95, the strongest since 25 November, with implied volatility ticking higher as authorities warned they could act on excessive moves and Governor Ueda called the rise in long term yields “somewhat fast.” EURJPY gained 0.7% to a record 182.64.
- AUDUSD climbed 0.5% to 0.6654 as Australia’s three-year yields hit a 13-month high and Governor Bullock said further cuts may not be needed and a hike was discussed.
- EURUSD slipped 0.1% to 1.1625; Germany is set to approve €52bn in defence procurement and France’s bill supports year end budget passage.
- GBPUSD briefly rose to 1.3356 before reversing to down 0.2%.
Commodities:
- Oil remained under pressure after its biggest two‑day drop in a month, with WTI back above $58 and Brent near $62, as the US forecast record output of 13.6 million barrels a day this year, adding to global oversupply.
- Silver was steady around $60.68 an ounce after its first break above $60 on Tuesday, supported by bets on further Fed easing (a potential 25bp cut on 9–10 Dec) and supply tightness; gold was little changed at $4,208.46, while platinum and palladium were steady.
Fixed income:
- US Treasuries fell, led by the front end and belly, after stronger JOLTS data flattened the curve and pushed 5s30s down ~2.5bp to ~103bp (fourth straight decline from >110bp), with losses trimmed by a well‑received 10‑year auction ahead of Thursday’s $22bn 30‑year reopening post‑FOMC; Australian 10‑years also traded lower for a third day ahead of an A$1bn Dec‑2030 sale, with yields up in seven of the past eight sessions.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.