
Access all our platforms from a single account.

Asia Market Quick Take – December 1, 2025

Key points:
- Macro: Trump has said he decided on next Fed chair
- Equities: Stocks gained after CME outage, Intel popped 10%.
- FX: JPY rises to 155.75; market anticipates BOJ policy shift, bond yield rises
- Commodities: Metals surged; silver and copper hit records
- Fixed income: Treasuries lower as Fed blackout begins
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- CME data center outage lasted 10 hours on a cooling facility malfunction and reopened at 8.30am ET.
- President Trump said he has decided on the next Fed chair, while White House economic adviser Hassett noted he would gladly accept if chosen.
- President Trump declared the cancellation of executive orders signed by former President Biden using an autopen, claiming about 92% were signed this way and are now void. Trump alleged Biden's lack of involvement in the autopen process and threatened perjury charges if Biden denies it.
- China’s official Manufacturing PMI stayed in contraction at 49.2 (in line with expectations), while Non-Manufacturing PMI missed forecasts at 49.5 (vs. 50.0 expected).
Equities:
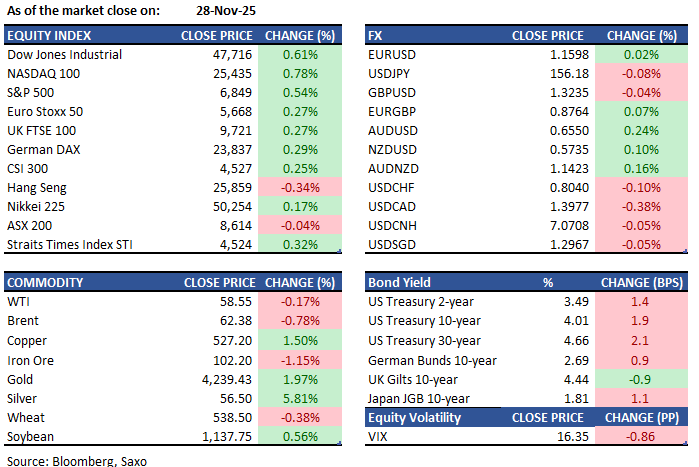
- US - US stocks closed November higher, with the S&P 500 up 0.5%, Nasdaq gaining 0.8%, and Dow adding 0.6% in a shortened post-Thanksgiving session. Investor optimism grew as markets priced an 80–85% chance of a near-term Fed rate cut. Communication services led, while healthcare lagged with Eli Lilly falling 2.6% after November rally. Tech performance was mixed: Microsoft (+1.3%), Amazon (+1.8%), Meta (+2.3%), Broadcom (+1.4%), Tesla (+0.8%), while Nvidia fell 1.8% and Alphabet was flat. A CME technical outage briefly disrupted futures trading, adding volatility. Intel shares jumped 10%, up for a fifth straight day, after TF International Securities analyst Ming-Chi Kuo said the company is expected to begin shipping Apple’s lowest-end M processor.
- EU - European stocks edged higher Friday, extending weekly gains on optimism that Fed easing could boost global equities. The STOXX 50 rose 0.2% to 5,666 and STOXX 600 gained 0.3% to 577. Tech led with ASML, SAP, Infineon, and Prosus up 0.7–1.5%. Consumer discretionary also advanced, with LVMH (+1.4%), Volkswagen (+1.3%), and Stellantis (+2%) driving autos. Inflation data reinforced expectations the ECB will hold rates, as Italy and France undershot forecasts while Germany was above. Despite a strong week, the Eurozone benchmark fell 0.6% in November.
- HK - Hang Seng slipped 87 points (0.3%) to 25,859 on Friday, ending a four-day rally as property and financial stocks weighed. Sentiment cooled ahead of China’s November PMI data and amid caution over volatility as mainland benchmarks approach multi-year highs on AI optimism. Losses were cushioned by modest gains in U.S. futures. Sportswear names Anta (-0.6%) and Li Ning (-1.4%) fell amid reports of interest in acquiring Puma. Other laggards included Alibaba Health (-3.1%), Nongfu Spring (-3.4%), and China Overseas Land (-2.7%). For November, the Hang Seng was little changed despite a 2.5% weekly gain ahead of China’s key economic meeting in December.
Earnings this week:
- Monday: MongoDB, Hafnia
- Tuesday: Scotiabank, Marvell Technology, CrowdStrike, TD Bank
- Wednesday: Royal Bank of Canada, Salesforce, Dollar Tree, Macy's, Snowflake, C3.ai
- Thursday: Kroger, Dollar General, DocuSign, Ulta Beauty, Hewlett Packard Enterprise
- Friday: Victoria's Secret, MoneyHero
FX:
- Dollar Index traded around 99.44. Political discourse from President Trump suggests income tax cuts funded by tariff revenues.
- EUR and GBP displayed subdued performance against the USD, driven primarily by the dollar’s movements rather than any specific economic developments in the Eurozone or the United Kingdom.
- JPY strengthened to 155.75 against USD as markets awaited Bank of Japan Governor Kazuo Ueda's comments, amid speculation of a December rate hike. Japan's two-year bond yield hit 1% for the first time since 2008, reflecting expectations of policy shifts.
- NZD is experiencing a pullback following recent gains post-RBNZ activity. AUDNZD remains near its weekly trough at 1.1410, down from a pre-RBNZ high of 1.1536.
- PBoC established the USDCNY mid-point at 7.0789, slightly above expectations of 7.0769, and marginally higher than the previous setting of 7.0779.
Commodities:
- OPEC+ will keep group-wide oil output unchanged for Q1 2026 and confirmed that members have approved the secretariat’s mechanism for assessing each country’s maximum sustainable production capacity.
- Silver hit a record above $57 on supply tightness and fully priced bets on a December US quarter-point rate cut; gold gained 2% to $4239 on Friday before slipping 0.4% to $4,222.87 in the early Asia session, and palladium and platinum also rose.
- Copper prices rose as miners, smelters and traders met in Shanghai amid mounting concerns over global operational disruptions, with LME futures up as much as 2.5% on Friday to a record $11,210.50 a tonne.
Fixed income:
- Treasuries ended near lows with yields up 1.5–3bp led by the belly after a CME outage delayed trading and kept price action muted; Canada underperformed (10y +1bp vs Treasuries) on a strong 3Q GDP beat, and with the Fed blackout started last Saturday ahead of the 10 Dec FOMC, swaps were little changed, pricing ~21bp of easing.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.