
Access all our platforms from a single account.

Asia Market Quick Take – 5 May, 2026

Key points:
- Macro: US and Iran launch attacks in Strait of Hormuz
- Equities: Stocks fell on attacks; Palantir reported fastest growth since 2020
- FX: JPY weakens near 157 against USD despite intervention and bullish options
- Commodities: Brent crude surged 5.8% to $114.44, the highest close since June 2022
- Fixed income: 30-year Treasury yield hit 5.03%, highest since July
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- US and Iran exchanged fire in the Strait of Hormuz, undermining a four-week ceasefire. US forces said they repelled Iranian attacks while escorting two US-flagged ships, and the UAE reported intercepting missiles and a fire at its Fujairah oil terminal. Despite US plans to restore shipping, security risks may keep the route closed until a US–Iran deal, sustaining concern over energy prices.
- Australia’s services PMI was revised up to 50.7 in April from 50.3 and 46.3 in March, signaling modest growth. Activity and jobs increased, but domestic demand and new orders fell amid higher fuel costs from the Middle East war. Export orders recovered slightly. Input costs and selling prices rose at their fastest pace since 2022 and early 2023 respectively, while business sentiment stayed muted.
- US factory orders rose 1.5% m/m in March 2026, beating the 0.5% forecast after a 0.3% gain in February. Durable orders were up 0.8%, led by a 3.6% jump in computers and electronics on strong AI and data-center demand, and higher transport equipment. Nondurable orders rose 2.1%, the highest since October 2022. Orders ex-transport were up 1.6%, ex-defense 0.9%.
Equities:
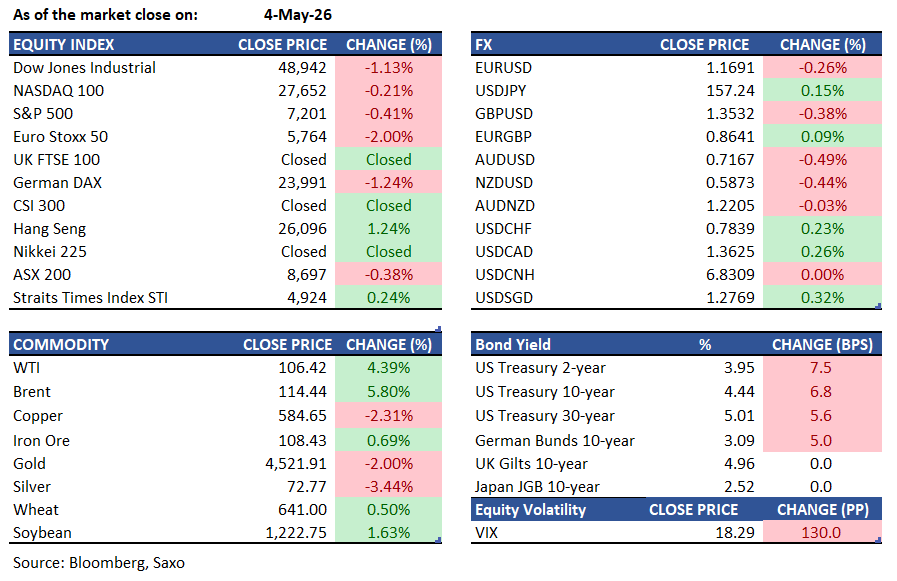
- US: The S&P 500 retreated 0.4% to 7,200.8 from record highs as oil prices jumped amid renewed US-Iran tensions. The Nasdaq fell 0.2% to 25,067.8, while the Dow Jones dropped 1.1% to 48,941.9. All sectors except energy were in the red, led by materials. eBay shares gained 5.6% after GameStop announced a surprise $56 billion takeover bid for the online auction company, while GameStop shares declined 7.5%. Apple contributed the most to the S&P 500 decline, decreasing 1.2%, while United Parcel Service had the largest drop, falling 10.5%. In after-hours trading, Advanced Energy shares fell 9.1% after reporting first-quarter results. Palantir fell 2.7% even after raising FY revenue outlook to $7.65b-$7.66b (vs $7.19b prior) while revenue grew 85%, fastest since 2020. Grab holdings+2% after beatingQ1 earnings with revenue growing 24% while maintaining sales outlook for 2026. Pinterest rose 15% after raising Q2 sales outlook and growing 18% in Q1.
- EU: European stocks fell as tensions in the Strait of Hormuz pushed up oil prices and President Trump's higher tariffs on car imports from the region weighed on auto stocks. The Stoxx Europe 600 Index fell 1% to 605.51, its biggest loss since April 7. The Euro Stoxx 50 Index dropped 2% to 5,763.61, its largest one-day percentage decline since March 20. Germany's DAX fell 1.2% to 23,991.27, while the Swiss Market Index declined 1% to 13,003.33. ASML contributed the most to the Stoxx 600 decline, decreasing 2.9%, while CSG had the largest drop, falling 13.1%. Trading was more muted than usual, with the London Stock Exchange closed for the early May bank holiday.
- Asia: Asian stocks rallied to record highs led by technology shares, with South Korea's Kospi surging 5.1% to 6,936.99, hitting a fresh all-time high as semiconductor giants Samsung Electronics rose 5.4% and SK Hynix jumped 12.5%. Taiwan's TWSE Index rose 4.6% to a new record high, led by Taiwan Semiconductor Manufacturing Co., which closed 6.6% higher, notching its largest gain in more than a year. Hong Kong stocks also finished in the green, while markets in Japan, mainland China, and Thailand remained closed for holidays. The MSCI Asia Pacific Index jumped as much as 2.3%, the most since April 8, before paring some gains.
Earnings this week:
- Tuesday: HSBC, Westpac, AMD, Shopify, PayPal, Pfizer, Lumentum, Strategy
- Wednesday: Arm, Disney, Novo Nordisk, Uber, Lyft, Coherent
- Thursday: UOB, Block, Shell, Gilead Sciences, Airbnb, Expedia, McDonald, Cloudflare, Coinbase, IREN
- Friday: Toyota, Sony, NTT, OCBC, Japan Tobacco, Macquarie, Commerzbank
FX:
- USD gained against all major currencies except the Norwegian krone after US–Iran clashes in the Persian Gulf, which also drew in the UAE and briefly pushed Brent crude above $115. The Bloomberg Dollar Spot Index rose, though it later pared gains; earlier, it had weakened on Trump’s comments about “very positive” talks with Iran.
- JPY weakened to about 157.15 against USD despite ongoing speculation about Japanese intervention, even as options markets turned increasingly bullish on the currency.
- EUR fell to $1.1692 while EURGBP edged higher, with an ECB survey showing inflation near 2.7% this year before easing toward target and officials warning of rising recession risks from Middle East supply disruptions.
- AUD and NZD reversed earlier gains, AUDUSD fell 0.5% to 0.7168 and NZDUSD dropped 0.5% to 0.5872. RBNZ Monetary Policy Committee member Prasanna Gai said supply shocks such as those in the Strait of Hormuz tend to push up the neutral interest rate.
Commodities:
- Brent crude jumped 5.8% to close at $114.44 a barrel, the highest close for the most-traded futures contract since June 2022, while WTI crude rose 3.1% to $105.12 after Iran struck a United Arab Emirates oil port and several ships.
- Gold futures fell 2.4% to $4,519.50 an ounce, now down 15% from January highs, as the swift reassessment of the US monetary outlook points to dimming prospects for precious metals despite lingering Iran uncertainty.
- Silver futures fell 3.8% to $73.07 an ounce, paring gains for the year to date to around 4%, as firmer real yields and a stronger dollar weighed on precious metals.
Fixed income:
- Treasury yields rose across the curve by at least five basis points, with the 30-year yield climbing as high as 5.03%, the highest since July, as traders boosted wagers that the Federal Reserve will have to reverse course and raise interest rates to curb inflation following a surge in oil prices.
- Two-year yields, the most sensitive to shifting expectations for Fed policy, climbed as much as 11 basis points to 3.96%, rising nearly 10 basis points last week.
- SOFR futures sold off with the March and June 2027 contracts underperforming on heavy volumes as a rate hike premium started to aggressively price into next year.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.