
Access all our platforms from a single account.

Asia Market Quick Take – 12 October, 2026

Key points:
- Macro: Riyadh’s airport attack kills 12 over weekend with fresh strikes this morning
- Equities: Stocks higher as yields fall; Verizon -8.7% after SpaceX enters mobile service
- FX: EUR edges up but outlook cautious; bears rotate into GBP, CHF options
- Commodities: Gold extend gains above $4,200
- Fixed income: US bond market is closed and 10 year yield at 5.24%
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- Ridyadh King Khalid International Airport hit again this morning, killing 1 and injuring 11, after the deadly attack over the weekend by the Houthis killed 12 people and injured 300, briefly pushing Brent above $105.50 before it reversed.
- US yields at multi-decade highs: The 10-year Treasury yield closed Friday at approximately 5.25%, while the 30-year yield sits near 5.61% — levels last seen in 2002. Economists increasingly believe higher rates will define the rest of the decade, per a WSJ survey of forecasters.
- Russia diesel deal: Russia partially lifted its diesel export ban, agreeing to supply 500,000 tonnes to global markets pursuant to a Trump-Putin agreement effective October 10, adding modest relief to energy markets.
- US midterms approaching: With midterm elections weeks away, Trump faces political pressure on energy costs and tariff impacts. US manufacturers continue to flag significant cost increases from tariffs, with Mexico vehicle exports plunging in September.
- University of Michigan sentiment: The preliminary October consumer sentiment index fell to 46.3, below the 47.6 consensus estimate and down from 48.1 in September, reflecting persistent inflation and geopolitical anxiety.
Equities:
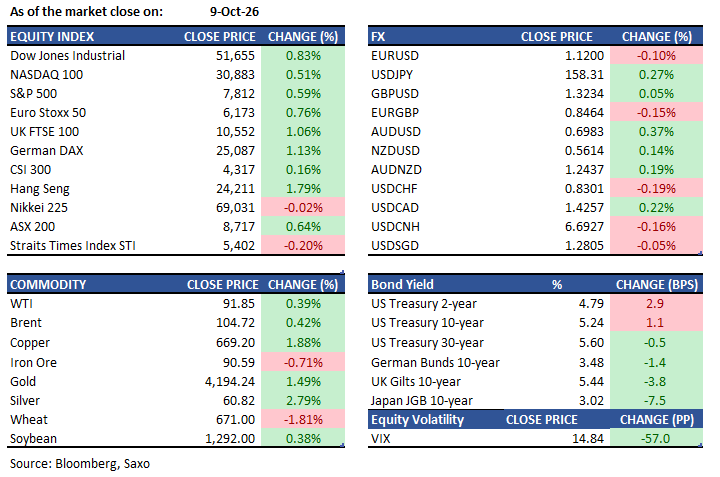
- US — US equities ended last week on a positive note, with the S&P 500 rising 0.6% on Friday to 7,811.54, the Nasdaq Composite gaining 0.6% to 27,366.17, and the Dow advancing 0.8% to 51,654.95. For the week, all major indices posted gains, though small caps lagged — the Russell 2000 fell for a fifth consecutive week, down 0.9% on the week and 5.7% over five weeks. Verizon was a notable decliner on Friday, falling 8.7%, its largest single-day drop in over 24 years as SpaceX purchases US nationwide spectrum portfolio, aiming to expand its Starlink internet into mobile service. Apple slipped 1.6% on reports of cut component orders for the iPhone 18 Pro. Heading into Monday, S&P 500 futures are up 0.2% and Nasdaq 100 futures up 0.5%, with oil reversing early Houthi-driven gains.
- EU — European equities recovered on Friday after touching a near four-month low mid-week, with the Stoxx 600 rising 1.0% to 631.55 — its best day since September 21 — led by industrial goods and services. The FTSE 100 gained 1.1% to 10,552, with HSBC and Relx among top contributors. The Euro Stoxx 50 ended the week down 1.04% at 6,173.37. European banks remain under pressure, with the Euro Stoxx Banks index down roughly 8% over two weeks, entering a technical correction. Deutsche Telekom fell 6.9% on Thursday after SpaceX announced a spectrum deal for Starlink mobile, raising competition concerns for European telcos. BofA upgraded French and European equities to overweight and neutral respectively, citing recent underperformance.
- Asia — Asian markets face a mixed open Monday. Japan's Nikkei is closed for a public holiday. The Kospi is expected to open lower, taking cues from semiconductor weakness on Wall Street — chip stocks including memory names lagged the broader US Friday rally, with the Roundhill Memory ETF slipping below its 50-day moving average. The Hang Seng faces continued pressure from elevated US yields and waning appetite for HK assets; the HKMA's intervention risk is reportedly rising, per DBS. The Straits Times Index (STI) was among the worst performers regionally last week, tumbling 3.5% on Wednesday — its largest drop since April 2025 — as Singapore bank shares DBS, OCBC, and UOB each fell more than 4-5% on JPMorgan warnings that surging long bond yields will hurt Southeast Asian lender earnings. Chinese AI funding activity has unsettled HK equity investors, with IPO and placement volumes hitting a record $47.5 billion in Q3.
Earnings this week:
- Tuesday: Aeon, JPMorgan Chase, UnitedHealth Group, Goldman Sachs, Wells Fargo, Citigroup, Johnson & Johnson, Domino's Pizza
- Wednesday: ASML, Bank of America, Morgan Stanley, BlackRock, State Street
- Thursday: Alcoa, Charles Schwab, Interactive Brokers, Prologis, Bank of New York Mellon, US Bancorp, PNC Financial, TSMC
FX:
- USD is broadly softer across the G10 board this morning, with the DXY down 0.07%. Scandinavian currencies lead gains, while NZD lags.
- SEK and NOK are the standout movers this morning. The Norwegian krone is the best-performing G10 currency YTD, up 5.43% against USD.
- EUR edges higher to 1.1214, but the broader EUR outlook remains cautious. Bears are rotating away from EURUSD and into GBP and CHF options to express their view. GBPUSD gains modestly to 1.3248, benefiting from euro bear positioning shifting into cable options.
- JPY firms slightly to 158.14, though it remains structurally weak — down ~1% YTD — and Japan's Finance Ministry continues to warn against one-sided moves.
- CHF is the preferred vehicle for EUR bears, with one-month EURCHF options seeing elevated demand.
- AUD holds near 0.6990, the second-best YTD G10 performer at +4.65% against USD.
Commodities:
- Brent crude briefly surged above $105.50/bbl overnight following the Houthi attack on Riyadh's King Khalid International Airport before reversing to trade around $104.15/bbl, down 0.6% on the session. Brent has been trading firmly above $100/bbl for several weeks, driven by the Iran war and tanker attacks in the Middle East. Russia's partial lifting of its diesel export ban provided modest downside pressure.
- Gold rose as much as 1.8% on Friday to trade above $4,200/oz, recovering from a two-month low earlier in the week. The rebound was supported by solid demand at the 30-year US Treasury auction, which pulled long-dated yields off their peaks. Gold-related equities in Hong Kong rallied in tandem, with Shandong Gold up 6.1% and Zijin Mining gaining on Friday.
Fixed income:
- Cash markets for US bonds are closed today for Columbus Day. The 10-year yield stands at 5.242%, the 2-year at 4.793%, and the 30-year at 5.599% — hovering near 24-year highs. Bond traders are focused on Wednesday's CPI print and Warsh's IMF appearance for guidance on the Fed's rate path. A November hike is not fully priced in.
- Last week's 10-year auction cleared at 5.30% with solid demand, and the 30-year drew strong appetite at 5.6%. However, asset managers are actively deleveraging ultra-long Treasury futures — shrinking bullish positions by ~$27m/DV01 over two weeks — suggesting forced selling remains a risk.
- US high-yield issuance fell 65% last week to $4.89bn, with spreads widening 2bps. Globally, the bond selloff is doing some of the central banks' tightening work — traders have begun paring rate-hike expectations as yields tighten financial conditions independently.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.