
You can access both of our platforms from a single Saxo account.

Visa earnings: options price a bigger move than Visa usually makes

Summary: Visa’s shares have usually moved little after a report, but option prices expect a bigger move this time. Two example structures show what each reading relies on.
Visa’s shares usually move little after a report. This time, options expect more.
Visa publishes its results for the fiscal fourth quarter and the full 2026 financial year after the US market closes on Tuesday 27 October 2026 (Source: Visa, company announcement, 8 October 2026). Visa’s financial year ends on 30 September, so this report also comes with the first look at the year ahead. In its July report, the company said payments volume grew 10% and cross-border volume 13% in constant dollars (Source: Visa, company announcement, 28 July 2026).
This article does not try to guess the result. It looks at a simpler question: how big a move does the market expect, and is that more or less than Visa usually moves?
How much Visa usually moves
Visa has reported eight times since October 2024, each time after the US close. Four times the shares rose the next day, and four times they fell. Most of the moves were small. In seven of the eight reports, the shares moved less than 3% in a single day. The exception was April 2026, when they rose 8.3% (Source: Saxo price data, author calculation). Past performance is not indicative of future results.
One simple way to sum up those eight moves is the median: line them up from small to large and take the one in the middle. For Visa, that is about 1.4%. The average is higher, at about 2.3%, because the April jump pulls it up. For Visa, a quiet report has been the normal case.
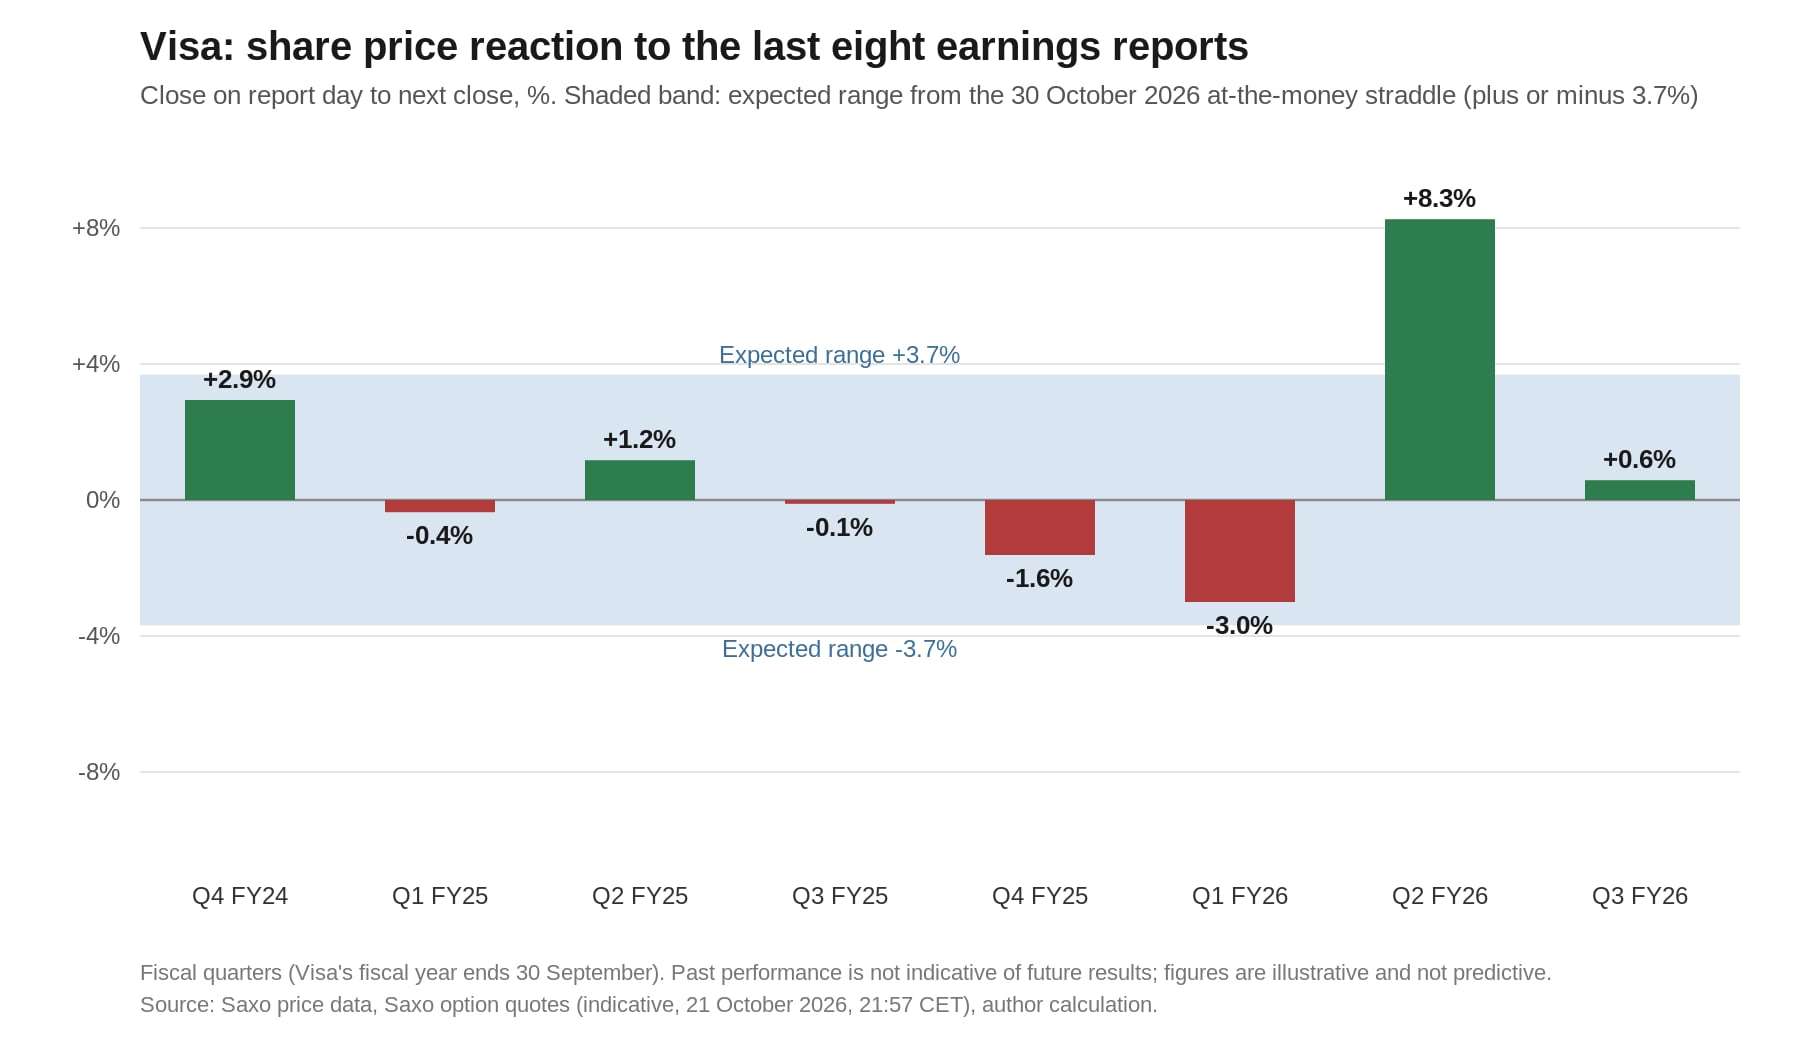 Share price move from the close on report day to the next close, last eight reports, against the range priced by the at-the-money straddle on the 30 October 2026 expiry (indicative Saxo quotes as of 21 October 2026, 21:57 CET). Past performance is not indicative of future results; figures are illustrative and not predictive. Source: Saxo price data, Saxo option quotes, author calculation.
What the options market expects
Option prices also hold an estimate of how far a share might move. A quick way to read it is the straddle: the cost of buying both the call and the put at the strike closest to the share price. By expiry, the shares have to move more than that combined cost before the pair is worth more than it cost. So the straddle price is roughly the move the market is paying for.
For Visa, the first expiry after the report is 30 October 2026. With the shares at about 407.9, the closest strike is 407.5:
- 407.5 call: about 7.95
- 407.5 put: about 7.10
- Straddle (call + put): about 15.05, or 3.7% of the share price
- Expected range: roughly 393 to 423
(Source: Saxo, indicative mid prices as of 21 October 2026, 21:57 CET.) Anyone can repeat this sum on a Visa option chain, though prices will have changed since.
So the market expects a move of about 3.7%, while Visa’s typical move has been about 1.4%. Part of the gap is time, because the 30 October expiry also prices the ordinary trading days around the report. Even so, in our view the options appear to price more than most past reports delivered. A higher price does not mean the market is wrong: it may be pricing the first outlook for the new year, or a repeat of April. Options carry a high risk of rapid loss and are not suitable for every investor.
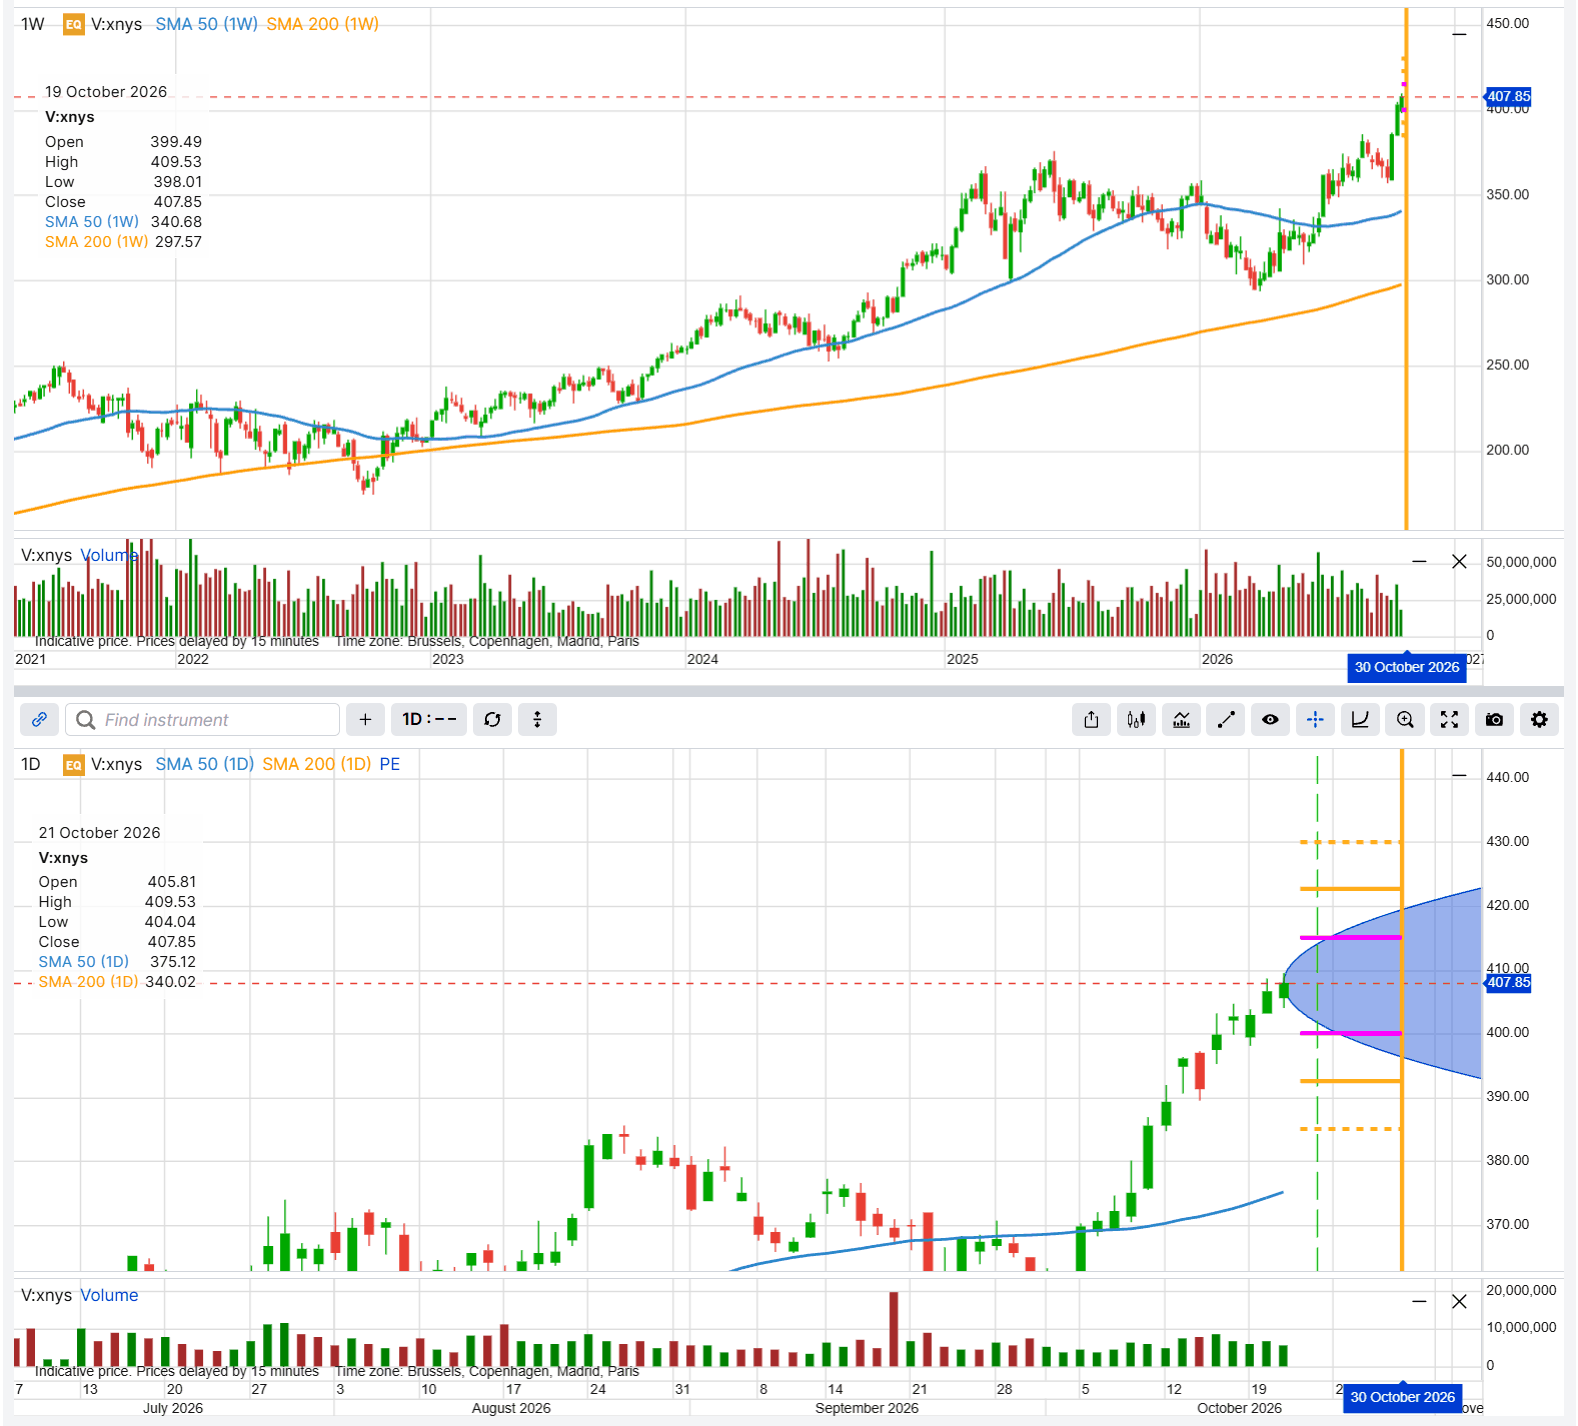 Visa share price, weekly (top) and daily (bottom), with the 30 October 2026 expiry marked. The horizontal lines mark the strikes used in the two examples below, and the shaded area shows the range implied by option prices. Past performance is not indicative of future results. Source: SaxoTrader.
Important note: The strategies and examples provided in this article are purely for educational purposes. They are intended to assist in shaping your thought process and should not be replicated or implemented without careful consideration. Every investor or trader must conduct their own due diligence and take into account their unique financial situation, risk tolerance, and investment objectives before making any decisions. Remember, investing in the stock market carries risk, and it’s crucial to make informed decisions.
Why option prices usually drop after a report
Before a report, options are expensive because nobody knows the numbers yet. Once the results are out, that uncertainty is gone, and option prices usually fall quickly, even if the shares hardly move. Traders call this IV crush, after implied volatility (IV), the amount of movement that option prices assume. It matters for both examples below: it works in favour of someone who sells options and against someone who buys them.
How the strikes and the expiry were chosen
The expiry is 30 October 2026, the first one after the report. Because Visa reports on a Tuesday, it also includes three trading days after the report. A later expiry would include more ordinary days, so it would cost more and depend less on the report.
Both examples start from the expected range above:
- Iron condor: sell the listed strikes nearest the edges of the expected range (392.5 and 422.5), and buy protection 7.5 points further out (385 and 430), about half the expected move.
- Long strangle: buy the strikes about half the expected move away from the share price (400 and 415).
Changing a strike changes the trade-off. Sold strikes placed closer to the share price bring in more money but are reached sooner. Strangle strikes placed further away cost less but need a bigger move.
All examples use indicative Saxo mid prices as of 21 October 2026, 21:57 CET, and contracts of 100 shares; actual prices will differ. All figures are hypothetical and for education only. Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply to each leg and vary by account and venue; check the applicable rates before entering any position.
View 1: Visa moves as little as usual
Iron condor (illustrative only, not a trade recommendation)
The idea is to sell a put below the share price and a call above it, and collect their price. Then buy a cheaper put further down and a cheaper call further up. Those two bought options put a limit on the loss if the shares move a lot.
The risk first: if Visa closes beyond either bought option, the loss reaches its maximum of about USD 551 per contract, almost three times the money collected. If the shares stay between the two sold strikes, the position keeps the money collected, and IV crush may help along the way.
- Sell 1 392.5 put at 2.12
- Buy 1 385 put at 1.23
- Sell 1 422.5 call at 2.16
- Buy 1 430 call at 1.06
- Net credit: about 1.99 per share (0.89 from the puts + 1.10 from the calls), or USD 199 per contract
- Maximum risk: about USD 551; maximum profit: about USD 199 (hypothetical, for education only)
- Break-even at expiry: about 390.51 and 424.49
- Risk: the maximum loss is the wing width minus the net credit; sold options can be assigned early. Costs and charges apply to each leg and vary by account and venue.
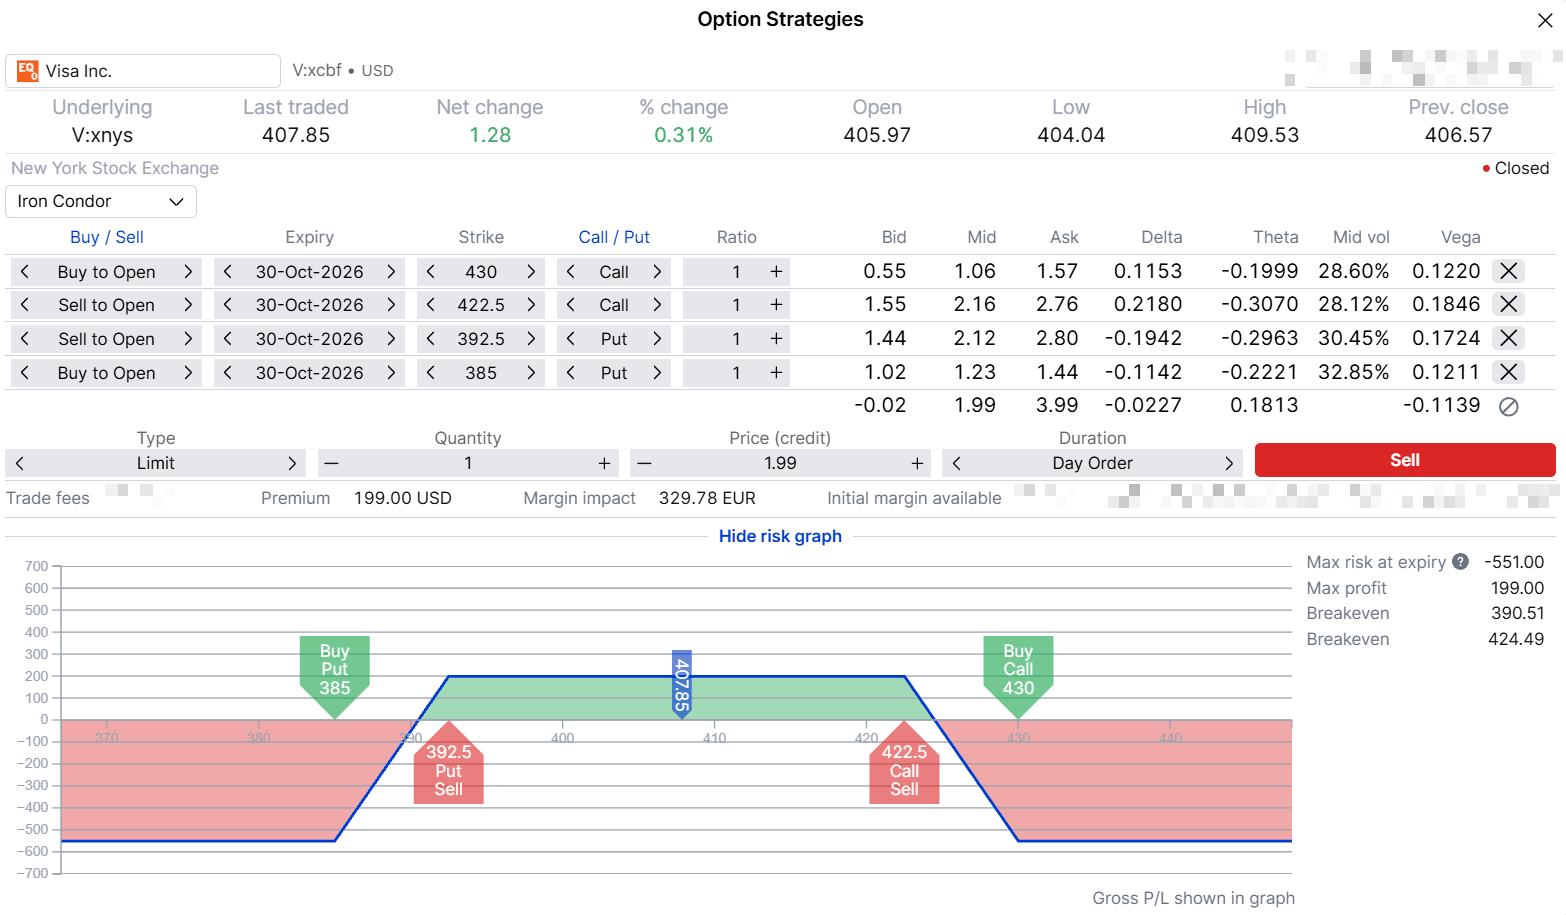 Iron condor, 385/392.5 puts and 422.5/430 calls, 30 October 2026 expiry, payoff at expiry. Hypothetical example for education only, indicative prices as of 21 October 2026, 21:57 CET. Past performance is not indicative of future results; figures are illustrative and not predictive. Source: SaxoTrader.
View 2: this report moves Visa like April did
Long strangle (illustrative only, not a trade recommendation)
The idea is the opposite of View 1. Buy a call above the share price and a put below it. If the shares jump, the call gains; if they fall, the put gains. Either way, the move has to be big enough to pay for both options.
The risk first: the price paid for the two options is the most that can be lost. That happens if Visa closes between 400 and 415 on 30 October 2026, and IV crush is likely to lower the value of both options from the morning after the report. Beyond the break-even points the position gains, with no fixed limit.
- Buy 1 415 call at 4.58
- Buy 1 400 put at 4.25
- Net debit: about 8.83 per share (4.58 for the call + 4.25 for the put), or USD 883 per contract
- Maximum risk: about USD 883; maximum profit: not capped (hypothetical, for education only)
- Break-even at expiry: about 391.17 and 423.83
- Risk: the maximum loss is the full premium paid, with the worst outcome if Visa closes between the two strikes at expiry. Costs and charges apply to each leg and vary by account and venue.
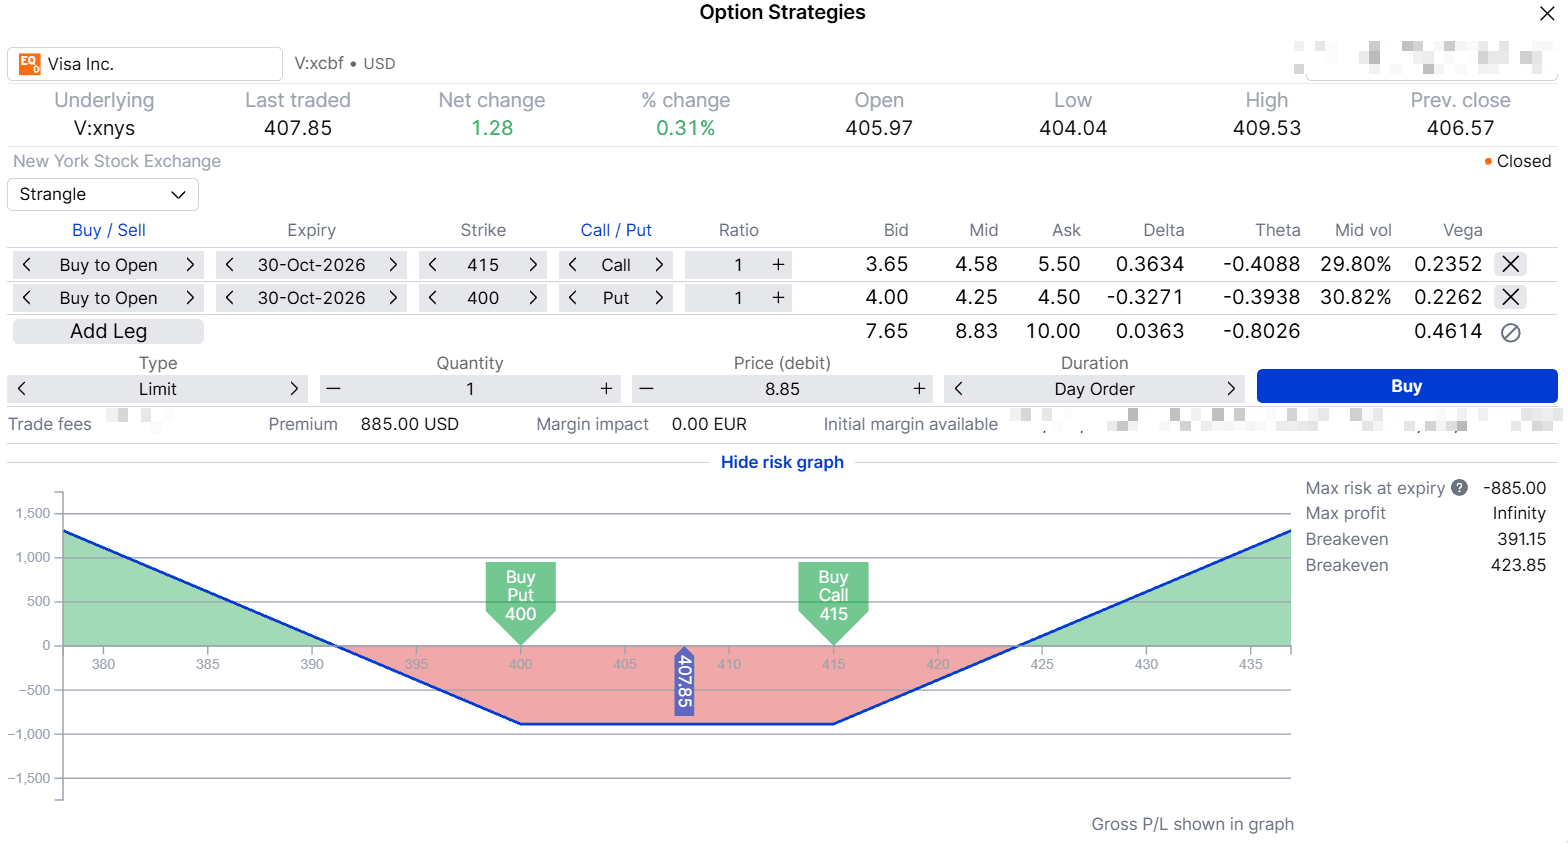 Long strangle, 400 put and 415 call, 30 October 2026 expiry, payoff at expiry. Hypothetical example for education only, indicative prices as of 21 October 2026, 21:57 CET. The platform rounds the order price to 8.85, so its debit, maximum risk and break-evens differ by a few cents from the mid-price figures in the text. Past performance is not indicative of future results; figures are illustrative and not predictive. Source: SaxoTrader.
Same eight reports, two readings
The break-even points of both examples sit roughly 4% either way of the share price. Seven of the last eight reports stayed inside both ranges, where the condor gains and the strangle loses. Only April 2026 went beyond it. Earlier moves came at different option prices, and past performance is not indicative of future results, so this tells us nothing about 27 October 2026. It does show what each example relies on, and both can lose their maximum. The condor loses on a report like April’s. The strangle loses on a report like most of the others.
Before any position: practical points
- Costs add up with every leg. Each leg has its own commission and its own gap between the buy and sell price. One order can hold up to four legs, so each example fits in a single order.
- Check the quotes. Several of the Visa options used here showed a wide gap between the buy and sell price, the outer condor legs most of all. Trading at those prices instead of the mid would collect much less on the condor and pay more for the strangle.
- Timing. Visa reports after the close. The first reaction shows up in after-hours trading and in the opening price on 28 October 2026, before most positions can be changed.
- The exit. Deciding before the report whether to close on 28 October 2026 or hold to expiry is easier than deciding mid-move.
- Assignment. Visa options are American-style, so a sold option that moves into the money can be exercised against the seller before expiry.
Final thoughts
Visa’s shares have usually moved little after a report, up or down. This time, option prices expect more. In our view, the useful question is whether that history still applies, or whether this report, with a new financial year to guide on, is different. The direction split evenly over the last eight reports.
The two examples show both answers. Each has a maximum loss known in advance, and each loses in exactly the case the other is built for. Which, if either, fits depends on a reader’s own view, risk tolerance and the prices available at the time. Options carry a high risk of rapid loss and are not suitable for every investor.
The author does not hold positions in any of the instruments mentioned in this article. The Author is permitted to wait at least 24 hours from the time of the publication before they trade the instruments themselves.
| Related articles/content |
|---|
| Meta earnings options price a smaller move than Meta usually makes | 20 Oct 2026 Tesla earnings the median says small the average says big What do options price | 19 Oct 2026 ASML earnings three ways to read the move options are pricing | 12 Oct 2026 Two banks one morning what options price for Goldman Sachs and Wells Fargo earnings | 9 Oct 2026 Same coin different payoffs an options toolkit for earnings season | 7 Oct 2026 Earnings season is close to a coin flip The edge is in what happens next | 5 Oct 2026 Finding unusually expensive or cheap options in the Saxo screener | 18 Sep 2026 Implied volatility rank what it measures and what it misses | 11 Sep 2026 Nine prints later what Q2 earnings season taught us | 11 Aug 2026 What IV crush really means in practice reviewed version | 9 April 2026 Trading earnings with defined | 31 Mar 2026 |
| More from the author |
|---|