
You can access both of our platforms from a single Saxo account.

US midterms: Scenarios, and what they can mean for AI and bond yields
Key points:
- Gridlock could be the most market-friendly outcome. A divided Congress may limit further fiscal expansion, potentially easing pressure on bond yields and supporting equity valuations.
- AI faces political risks, but the bigger challenge is financing. Election outcomes could influence data-centre approvals and energy policy, but rising power costs, debt and pressure to deliver returns may matter more for AI's next phase.
- A Republican win could favour AI infrastructure, but pressure bonds. Policy continuity may support AI, energy and financials, but concerns over deficits and higher yields could offset the benefits for equity valuations.
The US midterm elections matter for investors, but probably not because they will completely change the direction of markets.
The bigger issue is this: will the election affect the AI story and bond yields?
Right now, those are the two biggest questions for markets. AI is still a major growth story, but investors are starting to ask tougher questions about how much companies are spending, how they are funding that spending, and whether returns will justify the cost. At the same time, higher bond yields are making it harder for expensive growth stocks to keep rallying.
That is why the midterms matter. Not because one result is automatically bullish or bearish, but because each outcome could affect fiscal policy, regulation, and the ease of building AI and energy infrastructure.
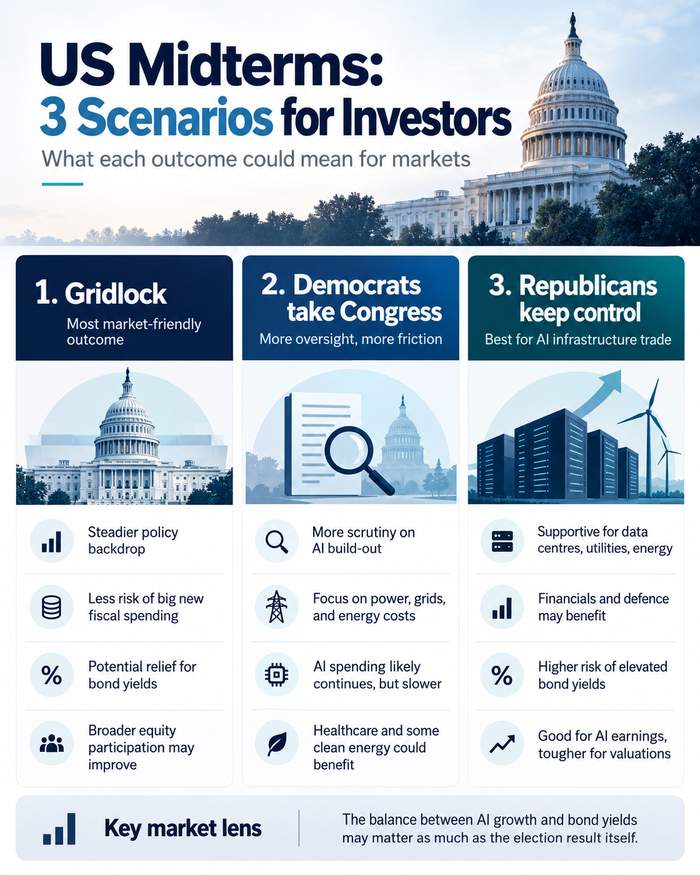
Scenario 1: Gridlock
This is probably the most market-friendly outcome.
If Democrats win one chamber and Republicans keep the other, it becomes harder to push through major policy changes. Markets often like that because it reduces the chance of large new spending plans, tax changes, or sweeping regulation.
For investors, that could be helpful if it means less fiscal pressure and a better backdrop for bonds. Lower or more stable bond yields could in turn support equity valuations, especially for growth stocks.
What it could mean for investors
- A steadier policy backdrop
- Less risk of another big fiscal push
- Potential relief for bond yields
- A better environment for broader equity participation, not just the biggest AI names
Scenario 2: Democrats take Congress
This would not mean a complete reversal of Trump’s agenda, because the president would still have veto power.
But it could mean more oversight, more scrutiny, and more friction around parts of the AI build-out, especially the physical side of it.
That is where the AI debate is evolving. The question is no longer just about chips and software. It is increasingly about data centres, electricity demand, grid investment, water usage, and who pays for all of it.
So the risk is not that AI stops. The risk is that the build-out becomes slower, more expensive, or more politically sensitive.
What it could mean for investors
- More pressure on data-centre and infrastructure projects
- Greater focus on power, utilities, grids, and energy costs
- AI spending likely continues, but perhaps with more scrutiny
- Healthcare and some clean-energy areas could benefit
Scenario 3: Republicans keep control
This is likely the most supportive outcome for the AI infrastructure trade.
It would probably mean more policy continuity, easier permitting, and stronger support for energy and infrastructure expansion. That could help areas linked to the physical build-out of AI, including data centres, utilities, nuclear, gas, copper, grid equipment, financials, and defence.
But there is an important catch.
The same outcome that supports growth and AI spending could also be more negative for bonds if markets start worrying about bigger deficits, more borrowing, and higher inflation pressure.
That means this outcome could be good for AI earnings, but less comfortable for AI valuations if bond yields keep rising.
What it could mean for investors
- Stronger support for the AI infrastructure theme
- Favourable backdrop for energy, financials, and defence
- Higher risk that bond yields stay elevated
- A more difficult backdrop for highly valued growth stocks
Source: Saxo
Bottom line
The US midterms may shape the market narrative, but they are unlikely to decide the whole market on their own.
- Gridlock could be good for bonds, but less supportive for fiscal growth
- Democratic control could mean lower fiscal impulse, but more regulatory friction
- Republican control could support growth and AI infrastructure, but keep pressure on yields
For investors, the real test is whether AI investment can keep delivering growth at a time when bond yields remain high and financing conditions are tighter.
That is why the election matters. But the bigger story is still the same: AI versus yields.