
Access all our platforms from a single account.

Asia Market Quick Take – 27 October, 2026

Asia Market Quick Take – 27 October, 2026
Key points:
- Macro: Trump hints strikes could resume. Japan services PPI rises 3.7% yoy.
- Equities: SOXX surges 2.8%. Tesla jumps 5.2% after upgrade by Barclays.
- FX: JPY weakest on Monday for G10. Brazilian real tumbles 8%.
- Commodities: Gold holds near $4,000; Brent crude pulls back from a six-month high
- Fixed income: Treasury curve flattens notably; 10-year remains around 5%
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- President Luiz Inácio Lula da Silva scored a surprise re-election win over Flávio Bolsonaro, sending Brazilian assets tumbling.
- Renewed Middle East diplomacy is seeking to avert wider US‑Iran escalation, with Saudi, Pakistani, and Turkish officials meeting Iranian leaders to revive talks and prevent further US‑Israeli strikes. The effort comes before US midterms, as Trump hints strikes could resume. Ongoing clashes involving Saudi-led forces, Iran-backed Houthis, and Hezbollah keep regional oil supplies at risk despite crude flows returning to near prewar levels.
- Japan’s Services PPI rose 3.7% y/y in September, up from a revised 3.5% and the highest since June 2024, led by transport and postal, leasing and rental, and other services; advertising prices fell. Month-on-month, the index gained 0.3%, its third straight rise.
- The Chicago Fed National Activity Index rose to +0.07 in September from -0.08, as production and sales/orders/inventories improved, employment was neutral, and consumption and housing weakened. The three‑month average ticked up to +0.03.
- UK shop price inflation rose to 2.1% y/y in October from 1.4%, the fastest since February 2024 and above the 1.6% forecast. Food inflation climbed to 2.9%, ambient food to 3.2%, fresh food stayed at 2.6%, and non‑food rose to 1.7%. The BRC flagged rising costs for retailers. Separately, UK CPI reached 3.5% in September, an 11‑month high.
Equities:
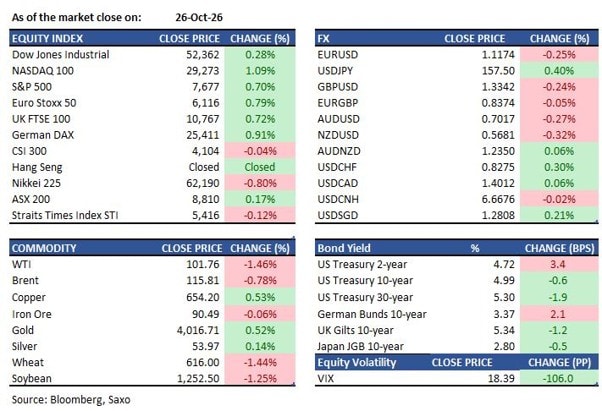
- US — On Monday 26 October, US equities snapped a two-day losing streak. S&P 500 rose 0.7% to 7,676.77, the Nasdaq Composite gained 0.8% to 26,169.38, and the Nasdaq 100 advanced 1.1%. The Philadelphia Semiconductor Index (SOX) surged 2.8%, its best day since 21 September, as Anthropic IPO filing slated for week of 16 Nov boosted sentiment. Tesla was the standout Mag 7 mover, jumping 5.2% after Barclays upgraded the stock citing SpaceX M&A potential. Nvidia rose 2.4%. Meta fell 1.9% after the company disclosed plans to raise up to $95 billion via a stock offering. Lumentum Holdings surged 8.2%. US equity index futures are steady to slightly higher in early Asian trading Tuesday.
- EU — European equities advanced on Monday 26 October, snapping a two-day losing streak. The Stoxx Europe 600 rose 0.8% to 640.66, the DAX gained 0.9% to 25,410.84, the CAC 40 added 0.8% to 7,847.32, and the Euro Stoxx 50 rose 0.8% to 6,116.23. Genmab surged 12% after a positive late-stage trial update for an experimental cancer treatment, hitting a 52-week high. Rolls-Royce rose 6.1%, leading the FTSE 100 higher by 0.7% to 10,767.33. Computacenter jumped 13.1%. On the downside, Telefonica fell 7–8% and Santander dropped 3–6% on Brazil election exposure. Frasers Group took control of Hugo Boss.
- Asia — Asian equities are broadly higher on Tuesday morning, tracking Wall Street's gains and buoyed by the Anthropic IPO filing. The MSCI Asia Pacific index is up 0.6%. The Nikkei 225 is advancing 1.6% to approximately 63,215, led by SoftBank Group (+5.3%) on AI sentiment. The Kospi is the standout performer, surging approximately 4.2% to 5,699, boosted by Anthropic euphoria and reports of SK Hynix's shareholder return programme — though analysts note the index needs to clear the 6,000 level to confirm a sustained recovery. The STI closed down 0.1% to 5,415.91 on Monday, with Sembcorp Industries the worst performer (-2.8%) and Hongkong Land the top gainer (+2.2%). Hong Kong markets are opening with a positive bias. The S&P/ASX 200 is slightly lower, down 0.2%, as investors rotate out of defensives into growth and AI-linked names.
Earnings this week:
- Tuesday: Coca-Cola, Boeing, PayPal, Visa, HSBC
- Wednesday: Alphabet, Microsoft, Ford, Ping An Insurance, PetroChina, Hitachi, SK Hynix
- Thursday: Merck, Mastercard, Caterpillar, Intel, Amazon, BYD, Denso, Keyence, Wilmar International
- Friday: Chevron, ExxonMobil, China Construction Bank, Kweichow Moutai, CNOOC, ICBC, Bank of China, Sands China, Panasonic
FX:
- USDJPY rose 0.4% to 157.53 and is little changed in early Asia Tuesday. The yen was the worst G10 performer on Monday. Markets are in wait-and-see mode ahead of the Fed decision, with Nomura expecting the pair to remain range-bound around 157. Japan's FX cyber attack adds a layer of headline risk.
- The Brazilian real tumbled more than 8% — its biggest single-day drop since the 1990s — following Lula's surprise re-election, dragging broader EM FX lower. The exchange operator B3 widened trading limits twice to accommodate the volatility.
- AUDUSD fell 0.3% to 0.7015, consolidating ahead of Wednesday's Australian CPI. Markets are pricing approximately a 60% chance of an RBA hike next week, which could provide support if CPI surprises to the upside.
- NZDUSD fell 0.3% to 0.5682. AUDNZD has scope to fall around Wednesday's RBNZ meeting, as leveraged funds remain net short NZD while AUD longs are stretched, according to Bloomberg Intelligence.
Commodities:
- Brent crude settled near $116 in a volatile session, pulling back from a six-month high near $117 seen last week. Diplomatic efforts to ease US-Iran tensions provided some relief, though Saudi-Houthi tensions and Middle East supply risk continue to underpin prices. European benchmark gas rose 2.8% to €96.44/MWh, a four-year high, on winter supply fears.
- Gold is holding near $4,000 an ounce, having added 0.5% on Monday. Traders are in wait-and-see mode ahead of the Fed decision on Wednesday. The 10-year real yield fell 1.6bps to 2.63%, providing a mild tailwind for bullion.
- Copper futures edged up 0.3% to $14,339 per metric ton on Monday, supported by the broader AI infrastructure spending theme and resilient US manufacturing data.
Fixed income:
- The Treasury curve flattened notably on Monday ahead of this week's coupon auctions and the October 28 Fed decision. The 10-year yield was little changed near 4.997%, while the 30-year fell 1.7bps to 5.309%. The 5s30s spread compressed to 47.7bps from 51.6bps. Options demand remains skewed toward hedging a further rally in longer-dated yields.
- The Treasury sold $69 billion in 2-year notes at 4.708%, tailing the 4.705% when-issued yield at the bidding deadline, indicating demand fell slightly short of expectations. Direct bidders were awarded a record share. The 2s10s curve remained approximately 4bps flatter following the results.
- US investment-grade bond sales hit an annual record of $1.76 trillion, surpassing the prior record of $1.75 trillion set during the pandemic borrowing boom of 2020. AI infrastructure spending is a key driver, with QTS (Blackstone) seeking $800 million in private placement debt and SpaceX closing a $40 billion equipment financing deal.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance. The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.