
Access all our platforms from a single account.

Asia Market Quick Take – October 23, 2025

Asia Market Quick Take – October 23, 2025
Key points:
- Macro: Trump administration sanctions 2 Russian oil companies
- Equities: Netflix fell 10% on tax dispute; Tesla -3.5% in post market after earnings miss
- FX: Sterling lagged G10 peers as UK CPI boosted BoE cut odds
- Commodities: Oil jumped after US sanctioned Russia’s biggest producers
- Fixed income: US Treasury yields edged lower across the curve
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- The Trump administration sanctioned Russian oil companies Rosneft and Lukoil to pressure Moscow to stop its war in Ukraine. Treasury Secretary Scott Bessent called for a ceasefire, highlighting the companies' role in funding the war. The sanctions include subsidiaries, with a call for allies to join and enforce them.
- The Trump administration is considering restricting exports to China of items using U.S. software—like laptops and jet engines—due to Beijing's rare earth export curbs, Reuters reports. This proposal matches Trump's October 10 threat of 100% tariffs and controls on "critical software." Meanwhile, Beijing is querying U.S. semiconductor firms about their operations in China, focusing on pricing and profits, as reported by Bloomberg News.
- The average 30-year fixed mortgage rate fell to 6.37% as of October 10, 2025, nearing a one-year low due to anticipated Fed rate cuts. Mortgage applications dropped 0.3% by October 17th, marking the fourth weekly decline, as increased refinancing didn't offset fewer new home purchases.
- The UK's annual inflation rate held at 3.8% in September 2025, below the expected 4%. Transportation prices rose sharply by 3.8%, driven by motor fuels and air fares. Prices also increased in restaurants, hotels, and clothing. Inflation slowed for recreation and culture and food and beverages due to more sales and discounts.
- According to Bloomberg's Wasson, US House Ways and Means Committee Chair Smith stated that lawmakers are considering a stopgap bill lasting until December 2026.
Equities:
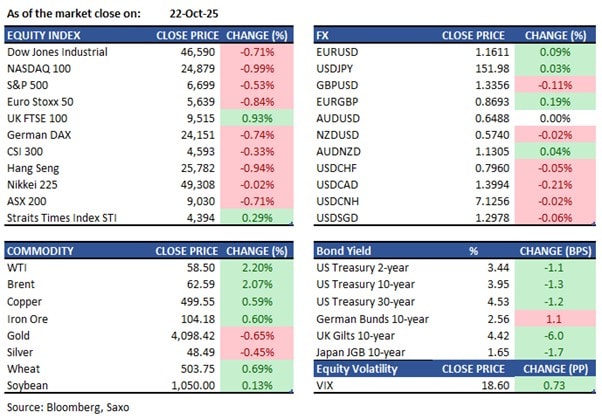
- US - The Dow fell 320 points from its record close, while the S&P 500 slipped 0.4% and Nasdaq dropped 0.9% after reports the White House may curb exports to China using U.S. software. Netflix plunged 10% on a Brazil tax dispute; Texas instruments sank 5.9% on weak guidance, dragging Intel (-3%) and AMD (-3.9%). On the upside, Raytheon rose 2% after strong Q3 results and raised guidance, while Intuitive Surgical surged 14.2% on robust earnings. In after hours, Tesla reported earnings that miss estimates despite strong delivery numbers, falling 3.5% post market while IBM reported earnings that beat estimates but did not perform as well in two key software areas, leading to a decline of 6.3% post market.
- EU - Germany’s DAX slipped 0.2% to 24,280 on Wednesday, ending a two-day winning streak as earnings season dominated focus. Infineon fell 3%, leading declines after Texas Instruments’ weak update pressured European chipmakers. Adidas dropped over 2% despite strong preliminary Q3 results and higher guidance, as JPMorgan trimmed its price target slightly on FX concerns. SAP eased 1% ahead of earnings. Defense stocks outperformed, with Renk up 4.7%, Rheinmetall 2.9%, and Hensoldt 1.8%, after Trump postponed a planned meeting with Putin.
- HK - Hong Kong stocks fell 0.4% to 25,922 in early Wednesday trade, reversing prior gains amid broad losses. Sentiment weakened as mainland markets eased and tech shares retreated after Nasdaq’s pullback ahead of key U.S. inflation data and next week’s Fed meeting. Consumer and financial stocks also slipped as Trump postponed a summit with Putin, while uncertainty lingered over a potential Xi meeting. Losses were cushioned by hopes the U.S. shutdown may end and Trump’s remark that high tariffs on China are “not sustainable.” Gold miners dropped sharply on weaker bullion, while CSPC Pharma and Smoore also declined.
Earnings this week:
- Thursday: Honeywell, Dow, American Airlines, Intel, Newmont
- Friday: Procter & Gamble, General Dynamics
FX:
- The dollar was little changed ahead of Friday’s US inflation report, delayed by the government shutdown. Sterling lagged G10 peers after UK CPI held at 3.8% year on year in September versus 4% expected, boosting odds of a BoE cut; GBPUSD slipped 0.1% to 1.3356.
- USDJPY was steady near 151.88 as exports rose for the first time in five months on chips and electronics, and Prime Minister Sanae Takaichi ordered fresh measures to ease inflation pressures.
- EURUSD rose 0.1% to 1.1610; USDCAD fell 0.2% to 1.3991 ahead of next week’s BoC decision; USDCHF eased 0.1% to 0.7960, with UBS economists suggesting the SNB may be intervening to weaken the franc.
- Australia’s dollar traded near the week’s low as US–China relations deteriorated ahead of a planned Trump–Xi meeting at the APEC summit, with AUDUSD little changed intraday and overnight at 0.6488. NZDUSD was also little changed at 0.5740.
Commodities:
- Oil jumped after the US blacklisted Rosneft and Lukoil, as President Donald Trump stepped up pressure on Vladimir Putin to end the war in Ukraine. Brent rose as much as 2.9% to above $64 a barrel and WTI rallied. Washington cited Moscow’s lack of commitment to peace and is seeking to squeeze key buyers India and China. The move marks a U‑turn from Trump’s recent plan to meet Putin; he said Tuesday he didn’t want a “wasted” meeting.
- Gold extended declines for a third session, sliding back towards $4,000 amid concerns the rally is overheated. Spot traded around $4,090 in early Asia morning, reinforcing a technical retracement, as investors weighed prospects of a US–China deal that could ease geopolitical tensions and temper haven demand. The metal is down nearly 6% over the past two sessions from a record high.
Fixed income:
- US Treasury yields slipped marginally across the curve, supported by strong demand for a $13bn 20‑year reopening. Front‑ and belly‑led strength into the US afternoon delivered a modest steepening, aided by a block buy in 5‑year futures. Swap spreads widened on reports of potential easing to bank capital proposals. Australia will auction linkers and New Zealand nominal bonds later today. JGBs are expected to firm, tracking US Treasuries amid risk‑off sentiment driven by escalating US–China tensions and the prolonged US government shutdown.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance. The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.