
Access all our platforms from a single account.

Asia Market Quick Take – 21 October, 2026

Asia Market Quick Take – 21 October, 2026
Key points:
- Macro: US ADP rose; UK unemployment falls to 4.7%
- Equities: Dow outperforms rising 1%
- FX: Pound was among the top G10 performers and yuan strengthens
- Commodities: Oil whipsawed & gold under pressure.
- Fixed income: Treasuries bull-flattened with real yields declining
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- ADP Weekly Payrolls showed US private payrolls rose an average of 18,500 per week in the four weeks to 3 October, highlighting a modestly softening labour market.
- Japan’s exports rose 16.7% yoy in September 2026, below the 20.1% consensus and the softest growth in 13 months, despite strong AI‑related chip and semiconductor demand and broad-based gains across major destinations and categories.
- US pending home sales fell 7.3% m/m in September 2026 to a record low, far worse than the expected 0.5% drop, as surging mortgage rates hit affordability and dragged down activity across all regions.
- Pakistan’s army chief Asim Munir met senior Iranian officials in Tehran to discuss bilateral ties and talks with Washington, but a participating diplomat denied an imminent deal while confirming negotiations continue.
- The UK unemployment rate fell to 4.7% in the three months to August 2026, beating expectations for 4.9% and reaching its lowest since mid‑2025, as unemployment declined and employment rose, pushing the employment rate up to 75.3% and nudging inactivity lower.
- Governor Kazuo Ueda said underlying inflation is nearing the BOJ’s 2% target amid a moderate recovery and tight labor market, driven by higher Middle Eastern energy costs and strong AI‑related demand.
Equities:
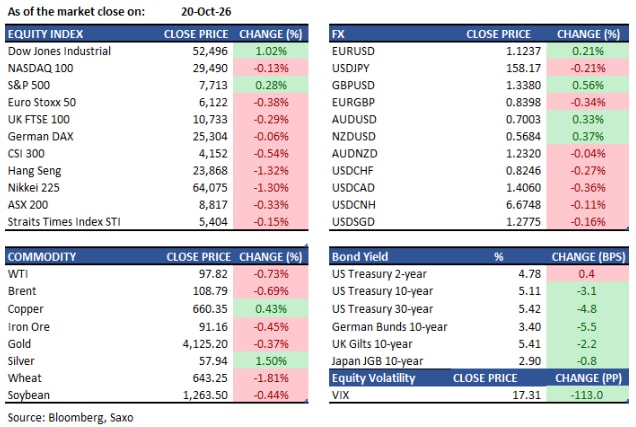
- US: US equities closed mixed as strong earnings offset AI credit concerns. The Dow Jones Industrial Average jumped 1.0% to 52,495.88, the S&P 500 rose 0.3% to 7,712.57 led by healthcare stocks, while the Nasdaq Composite edged down 0.02% to 26,424.82. Key movers: Equifax surged 11.3%, Eli Lilly gained 3.5%, and GM fell 7.6% after CEO Mary Barra warned of "intensifying" challenges and narrowed guidance. In after-hours trading, SpaceX posted $4.4 billion in net income, well above the $1.88 billion consensus, lifting S&P 500 ETFs. Tesla also gained 2% after Musk said he likes the idea of Tesla and SpaceX merging. Capital One rose 4.5% post-market on a strong earnings beat. Netflix sank on a disappointing subscriber update. Super Micro Computer jumped 15% after preliminary sales results $18.5-$19.5b vs estimate of $15b.
- EU: European equities drifted lower, weighed by AI jitters and French political risk. The Stoxx 600 fell 0.1% to 638.64, with ASML down 2.7% the largest drag. The FTSE 100 dropped 0.3% to 10,733, with HSBC the biggest contributor to losses and Diploma falling 4.0%. The DAX was little changed at 25,304, with Brenntag the worst performer at -3.4%. The SMI outperformed, rising 0.8% to 14,478 led by Roche (+2.6%). The OMX Stockholm fell 0.9%, dragged by ABB (-4.9%). French stocks continued to underperform amid ongoing cost-of-living protests and fiscal concerns, with French 10-year OAT yields holding near multi-year highs at 4.95%.
- Asia: Asian equities fell sharply on Tuesday as AI trade jitters and rate fears dominated. The MSCI Asia Pacific Index dropped as much as 1.2%. The Hang Seng Index fell 1.3% to 23,867.74, with Alibaba down 3.6% and Lenovo tumbling 10.0% after Citi cut its price target by 20%. CATL fell sharply ahead of earnings that subsequently missed estimates — net income rose 15% year-on-year to 21.25 billion yuan, well below the 26 billion yuan consensus. The Kospi plunged 3.7% to 5,552.74, with Samsung Electronics and SK Hynix each falling around 3–4% on AI spending concerns and the Elice IPO debacle. The STI slipped 0.1% to 5,404.02, with Yangzijiang Shipbuilding the worst performer at -3.1%. The Nikkei 225 also declined. However, sentiment has sharply reversed overnight: as of early Wednesday, the MSCI Asia Pacific Index is up 0.6%, the Kospi has rebounded 1.9%, and Nasdaq 100 futures are up 0.7% on the back of SpaceX and Super Micro earnings beats.
Earnings this week:
- Wednesday: Abbott, NextEra Energy, AT&T, CME Group, Danaher, Tesla, Meta, IBM, Lam Research, Texas Instruments, Philip Morris
- Thursday: Lockheed Martin, Nokia, Comcast, American Airlines, Bloom Energy
- Friday: American Express, Schlumberger
FX:
- All G10 currencies advanced against the greenback at the session's weakest point for the dollar.
- USDJPY has slipped past 158, trading at 158.34 this morning (+0.1% on the day). The pair has traded in a tight 200-pip range over the past 20 days, with analysts noting the range increasingly resembles a managed currency. A Fed rate hike remains the clearest catalyst for a topside break.
- GBPUSD is at 1.3374, holding above its 21-day moving average for the first time since late August, reinforcing near-term topside dynamics. The pound was among the top G10 performers during Tuesday's dollar weakness.
- The yuan strengthened modestly onshore and offshore on Tuesday as the dollar weakened alongside falling oil prices.
Commodities:
- Brent crude hit a five-month intraday high above $111 a barrel on Tuesday before reversing sharply, settling at $108.79 (-0.69%) after a diplomat confirmed that reports of an imminent US-Iran peace deal were inaccurate. WTI settled near $98 a barrel. The session saw a range of over $6 for Brent. Iranian IRGC reported tankers struck mines in the Strait of Hormuz, and Iran added 122 tankers to its sanctions list. Brent is currently at $109.50 and WTI at $98.50.
- Gold settled at $4,122.40 on Tuesday (-0.40%), its second consecutive session of losses, as elevated oil prices fuelled inflation concerns and clouded the Fed rate path. Bullion is trading around $4,117 this morning, down more than 1% since the start of the week and approximately 22% below its January 2026 peak of $5,318. ETF gold holdings continue to rise, reaching a four-year high, but leveraged players have reduced exposure.
Fixed income:
- The curve aggressively twist-flattened, with the long end rallying on haven demand from AI jitters and lower oil prices. The 10-year yield fell 2.6 basis points to 5.117%, while the 30-year fell 4.7 basis points to 5.424%. The front end was little changed, with the 1-year yield at 4.482%. The 5s30s spread compressed to 49.1 basis points from 52.9 basis points.
- US 10-year real yields fell 4.9 basis points to 2.74% on Tuesday, though they remain 81 basis points higher year-to-date. September CPI was 3.7% year-on-year, keeping the inflation backdrop elevated. Treasury options markets showed two consecutive days of demand for downside protection targeting a 10-year yield rise to 5.3% by month-end, suggesting the market is not fully convinced the rally has legs.
- French 10-year yields held near multi-year highs at 4.95%, extending underperformance versus Bunds. French bonds remain under pressure from ongoing cost-of-living protests and fiscal concerns, with a record share of investors reportedly underweighting French equities. US high-yield credit also remains stressed, with CCC spreads at 1,072 basis points — the widest since October 2022.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.