
Access all our platforms from a single account.

Asia Market Quick Take – 11 November, 2026

Key points:
- Macro: Headline and Core CPI hotter than expected; Fed signals more tightening.
- Equities: NVDA falls 5.5%; Coreweave reported a strong quarter rising 8% after hours.
- FX: USD strengthens after hotter than expected CPI.
- Commodities: Gold falls on real yield rising and brent near $90
- Fixed income: US Treasuries suffer one of biggest selloffs since April 2025
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- Headline CPI rose 0.4% m/m vs. 0.3% expected; core CPI rose 0.3% vs. 0.2% expected, the third straight upside surprise. YoY figures were not published due to missing October 2025 data from last year’s shutdown.
- Fed officials signaled more tightening: Waller backed a 25bp December hike with openness to 50bp; Logan called for at least two more hikes; Goolsbee labeled October inflation “distressing.” Markets fully price a December hike and ∼55bp of tightening by mid-2027.
- NFIB Small Business Optimism dipped to 97.8 in October (from 97.9), a new low since June. Labor quality/availability remained the top issue (25%), with taxes rising to 21%, the highest since May 2021. A net 8% of owners expect better conditions over the next six months, up 2 points.
- Reuters Tankan: manufacturers rose to +27 in November from +22, the highest since August 2021, led by electronics (+39) and precision machinery (+42). Non-manufacturers jumped to +35 from +23, the highest since June 2018. Three months ahead, manufacturers see +28 and non-manufacturers +29.
Equities:
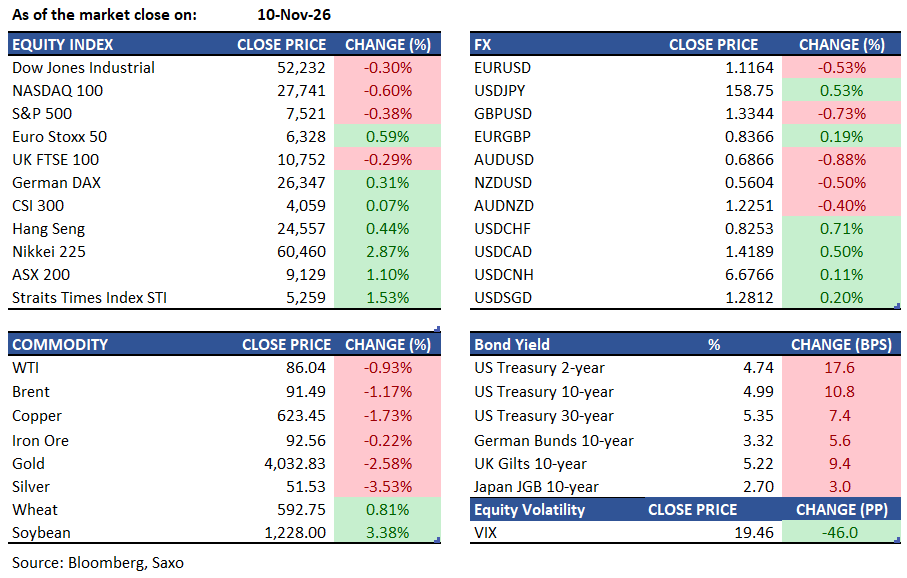
- US: On Tuesday, the S&P 500 fell 0.4% to 7,520.93, halting back-to-back gains, as hotter-than-expected CPI data and hawkish Fed commentary weighed on sentiment. The Nasdaq 100 shed 0.6% and the Dow declined 0.3%. Nvidia was the biggest drag on the S&P 500, falling 5.5%, while Broadcom and AMD advanced. Financials and energy closed in the green. In after-hours trading, CoreWeave reported a strong third quarter, with revenue rising 168% and the company raising guidance, while Akamai fell ~1.7% after a downgrade by Evercore ISI. FT: Anthropic may lift IPO price above $70–$78 on strong demand, potentially topping a $1.5 trillion valuation while prioritising proceeds for heavy compute spending.
- EU: European markets were broadly supported by strong earnings momentum, with Stoxx 600 tech hardware and semiconductor revenue beats outpacing misses 10-to-0 in the most recent quarter. Inficon Holding posted the largest positive revenue surprise at +15%, while ASML had the largest miss at -0.4%. Materials sector beats also outpaced misses 16-to-8, with Fuchs SE leading on the upside and Boliden posting the largest miss at -18%.
- Asia: Asian equity markets are set to open lower on Wednesday, with futures for South Korea, Japan, and Hong Kong all pointing to declines following Tuesday's hot US CPI print and Wall Street selloff. The Kospi opened 0.6% lower at 5,209.71. Nikkei futures dropped 0.5% overnight. On Tuesday, the STI gained 1.5% to 5,258.59, led by Yangzijiang Shipbuilding (+5.5%), as tech stocks clawed back some ground after last week's sharp selloff. Australian stocks were little changed, with Commonwealth Bank gains offsetting BHP declines. Japan's AI adopters such as BayCurrent and Shift Inc. have outperformed chip-related names like Kioxia. Power equipment stocks in Japan — including Mitsubishi Heavy, Fuji Electric, and Meidensha — are expected to face pressure following SoftBank's data center writedown. SoftBank reported a ¥1.12 trillion (about $7.1 billion) net loss in its fiscal Q2, its first in almost two years, after a ¥3.7 billion writedown tied to non-refundable advance payments for US data-center power equipment and weaker AI-related valuations.
Earnings this week:
- Wednesday: Recruit; Kirin; Singapore Airlines; RWE; E.ON
- Thursday: SMIC; Bridgestone; Inpex; Cisco; Siemens; Allianz; Merck; Applied Materials
- Friday: MUFG; Sumitomo Mitsui Financial; Mizuho Financial; Japan Post Bank; Singtel; Generali
FX:
- USD strengthened after hotter‑than‑expected October CPI cemented expectations for a December Fed rate hike, pushing the Bloomberg Dollar Spot Index up about 0.5% and lifting the greenback against all major peers.
- NOK, AUD, SEK each fell at least 0.8% against the dollar, the worst performers among G10 currencies on Tuesday.
- USDJPY was little changed at 158.75 in early Asian trading on Wednesday, after rallying 0.5% on Tuesday. Japanese government bonds are expected to fall as the yen remains under pressure from the widening US-Japan rate differential.
- The yuan weakened both onshore and offshore following the CPI data. USDCNH rose 0.1% to 6.6766 and USDCNY rose 0.1% to 6.6794. The PBOC set Tuesday's fixing at 6.7167 per dollar.
Commodities:
- Gold tumbled as much as 2.8% on Tuesday to trade below $4,030 per ounce, as the hot CPI print and hawkish Fed commentary drove Treasury yields and the dollar sharply higher. The drop reversed a near-2% gain from Monday, which had been supported by hopes of a diplomatic resolution to the Middle East conflict.
- Brent crude fell, briefly sub-$90 and settling below $92 after a 3.7% drop, as technicals and Iran de-escalation bets weighed, with Trump signalling no further strikes and Democrats eyeing the shutdown deadline to press for an off-ramp.
Fixed income:
- The US Treasury market suffered one of its biggest selloffs since April 2025 on Tuesday. Two-year yields surged as much as 21 basis points to 4.77% — the largest single-day move since President Trump's tariff announcements — as the hot CPI print and hawkish Fed speakers drove aggressive bear flattening. The 2s10s and 5s30s spreads tightened by approximately 7bp and 6.5bp respectively.
- Five-year yields rose 15bp to 4.829%, seven-year yields rose 15bp to 4.918%, and the 30-year yield rose 6bp to 5.343%. The 10-year note auction on Tuesday tailed by around 1bp, keeping upward pressure on yields. US 10-year real yields rose 11bp to 2.76%, heading for a three-week closing high.
- Treasury futures are hovering near overnight lows in early Asian trading and look vulnerable to further downside, with cash Treasuries closed for the US Veterans Day holiday reducing liquidity. Australian and New Zealand government bonds opened lower, tracking the US move. Multiple Fed officials — including Anna Paulson and Austan Goolsbee — continued to keep a December hike firmly in play overnight.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.