Quick Take Asia

Asia Market Quick Take – 18 September, 2026

Macro 6 minutes to read

Asia Market Quick Take – 18 September 2026 

Key points:  

  • Macro: BoE holds rates at 3.75%; warns of hikes if inflation rises 
  • Equities: Chips lead equities with SMH up 3.1% 
  • FX: AUDUSD firms to 0.7120 on hawkish RBA expectations 
  • Commodities: Oil drops further as Saudi restores pipeline 
  • Fixed income: US yields break 8-day rise, down 9bps 

------------------------------------------------------------------  

qt 1809

Disclaimer: Past performance does not indicate future performance.  

Macro:  

  • The BoE kept rates at 3.75% in a 6–3 vote but warned they could rise if Middle East tensions stoke inflation. Governor Bailey said the energy shock’s impact is so far limited but prolonged volatility could increase inflation risks.
  • Eurozone inflation rose to 3.2% in August 2026, near a 2½-year high and above the ECB’s 2% target, driven by a 14.3% jump in energy. Core inflation edged down to 2.4% and services inflation to 3.0%. Inflation picked up in Germany, France, Spain, and Italy, but eased slightly in the Netherlands.
  • Canada’s producer prices rose 1.3% m/m in August 2026, up from 0.3% in July and versus expectations for no change. Energy and petroleum prices gained 4%, led by refined products, while PPI excluding energy rose 0.8%. Nonferrous metals (+4.4%) and chemicals (+2.8%) also rebounded, boosted by unwrought precious metals and plastic resins.
  • Saudi Arabia is rerouting crude via ship-to-ship transfers near Oman’s Sohar to offset a key pipeline shutdown, cutting tankers’ exposure to Iranian attacks. It expects to restore about half of the East-West pipeline’s capacity within days and full flows in six weeks. Ship-to-ship transfers in the Gulf of Oman have risen to 2.7 million bpd from 1.5 million bpd in August.
  • US jobless claims fell by 10,000 to 196,000 in midSeptember, near July’s 60year low and below the 208,000 forecast. Continuing claims dropped to 1.73 million, the lowest since January 2024, highlighting labor market resilience. Federal employee claims edged up to 398 but remain historically low.
  • The US House passed a bipartisan bill imposing economic sanctions on Russia via tariffs in a 262-159 vote. The bill is expected to be signed by President Trump.

Equities:  

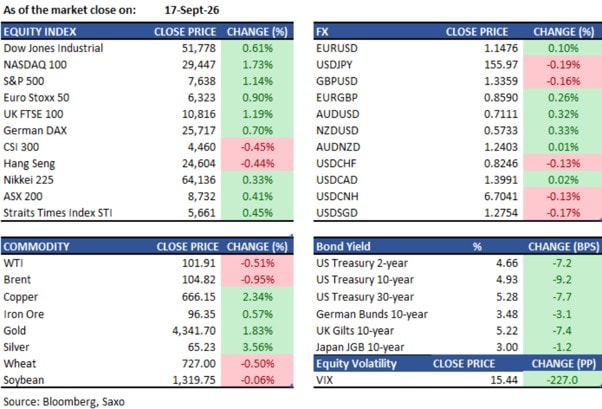
  • US (Thursday close): US equities posted their best session in six weeks on Thursday, with the S&P 500 rising 1.1% to 7,637.76, the Nasdaq 100 climbing 1.7% to 29,447, and the Dow Jones gaining 0.6% to 51,778. The Philadelphia Semiconductor Index surged 3.1%, led by Nvidia (+~2.5%) after CEO Jensen Huang said the company expects to sell twice as many chips next year. Berkshire Hathaway was a notable laggard, weighing on financials. In after-hours trading, Steel Dynamics fell 3.4% and Nucor dropped 3.7% after both steel producers issued Q3 EPS guidance below consensus estimates. Intuit reported in-line Q1 revenue guidance of $4.29–4.31bn.
  • EU (Thursday close): European equities advanced for a second consecutive session, buoyed by the Fed's inflation-fighting commitment and a pullback in oil. The Stoxx 600 rose 0.9% to 642.60, the DAX gained 0.7% to 25,717, the CAC 40 added 0.6% to 8,187, and the FTSE 100 climbed 1.2% to 10,816 after the BoE held rates. ASML led the Stoxx 600 higher, while Allegro.eu surged 9.5% to a 52-week high. Man Group rose as much as 6% after a UBS upgrade. Raiffeisen Bank was among the notable decliners. The OMX Stockholm 30 rose 1.3%, led by Swedbank (+2.6%) and Boliden (+3.3%).
  • Asia (Friday open): Asian equities are tracking Wall Street's rally, supported by lower oil prices and cooling Treasury yields. The Kospi opened sharply higher, rising 2.5% to 6,886 at the open, driven by Korean memory chipmakers on the back of Nvidia's bullish chip demand outlook. The Nikkei 225 is trading around 64,136, with attention focused on the BOJ rate decision due later today — a 25bp hike to 1.25% is fully priced in, though markets are watching Governor Ueda's press conference for forward guidance. The Hang Seng closed Thursday at 24,604 (-0.4%), weighed by Tencent (-1.7%) and Laopu Gold (-3.0%), though mainland investors bought a net HK$3.36bn via Stock Connect for a ninth consecutive session. Huawei announced over 10 new AI chipsets at its annual summit in Shanghai, accelerating the launch of its Ascend 960DT chip to Q1 2027.

Earnings this week: 

FX: 

  • The dollar stayed firm postFed, keeping USDJPY elevated around 156.2 (with Citi eyeing upside toward 159 if the BOJ disappoints), weighing on EURUSD near 1.148 amid weaker French OATs and political risk, and pushing GBPUSD down to 1.336 after leading G10 losses despite some short covering postBoE; in contrast, AUDUSD firmed to about 0.712 on hawkish RBA expectations, while USDCNH held steady around 6.70, supported by the PBOC fix and continued northbound Stock Connect inflows.

Commodities: 

  • Oil fell for a third day, with Brent near $104.8/bbl and WTI around $101.2, as Saudi plans to restore about half of its East-West pipeline capacity and easing Middle East risks unwind the recent price premium. Gold jumped to about $4,346/oz after spiking to $4,380, helped by lower Treasury yields and a softer dollar post-Fed. Copper remains volatile as traders await a US decision on refined copper tariffs, keeping pressure on names like Freeport-McMoRan and Southern Copper after LME prices previously hit a record $14,617/ton on tariff bets.

Fixed income:  

  • US Treasury yields snapped an eight-day rise Thursday, with the 10-year down about 9 bps to 4.93%, the 30-year at 5.29% and the 1-year at 4.38%, helped by weaker oil and the BoE’s hold boosting gilts and Treasuries. A $19bn 10-year TIPS auction tailed at 2.653%, the highest since 2008 and ~2 bps above WI, with softer indirect demand. A Bloomberg survey shows over 60% of respondents expect the 10-year above 5% by end-2026 (median 5.1%); KKR lifted its year-end target to 5.1%, and Jeffrey Gundlach warned a future US recession could spark a fiscal-driven surge in long yields.

For a global look at markets – go to Inspiration.  

This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance. 
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information. 


Quarterly Outlook

01 /

  • Q1 Outlook for Traders: Five Big Questions and Three Grey Swans.

    Quarterly Outlook

    Q1 Outlook for Traders: Five Big Questions and Three Grey Swans.

    John J. Hardy

    Global Head of Macro Strategy

    Strap yourself in for key market questions that must be answered in 2026.
  • Q1 Outlook for Investors: “AI” party hangover needs discipline and diversification

    Quarterly Outlook

    Q1 Outlook for Investors: “AI” party hangover needs discipline and diversification

    Charu Chanana

    Chief Investment Strategist

    2026 is a high-valuation, high-dispersion year: the AI story matures, policy becomes less predictabl...
  • Q4 Outlook for Investors: Diversify like it’s 2025 – don’t fall for déjà vu

    Quarterly Outlook

    Q4 Outlook for Investors: Diversify like it’s 2025 – don’t fall for déjà vu

    Jacob Falkencrone

    Global Head of Investment Strategy

  • Q4 Outlook for Traders: The Fed is back in easing mode. Is this time different?

    Quarterly Outlook

    Q4 Outlook for Traders: The Fed is back in easing mode. Is this time different?

    John J. Hardy

    Global Head of Macro Strategy

    The Fed launched a new easing cycle in late Q3. Will this cycle now play out like 2000 or 2007?
  • Q3 Investor Outlook: Beyond American shores – why diversification is your strongest ally

    Quarterly Outlook

    Q3 Investor Outlook: Beyond American shores – why diversification is your strongest ally

    Jacob Falkencrone

    Global Head of Investment Strategy

  • Q3 Macro Outlook: Less chaos, and hopefully a bit more clarity

    Quarterly Outlook

    Q3 Macro Outlook: Less chaos, and hopefully a bit more clarity

    John J. Hardy

    Global Head of Macro Strategy

    After the chaos of Q2, the quarter ahead should get a bit more clarity on how Trump 2.0 is impacting...
  • Equity outlook: The high cost of global fragmentation for US portfolios

    Quarterly Outlook

    Equity outlook: The high cost of global fragmentation for US portfolios

    Charu Chanana

    Chief Investment Strategist

  • Commodity Outlook: Commodities rally despite global uncertainty

    Quarterly Outlook

    Commodity Outlook: Commodities rally despite global uncertainty

    Ole Hansen

    Head of Commodity Strategy

  • Upending the global order at blinding speed

    Quarterly Outlook

    Upending the global order at blinding speed

    John J. Hardy

    Global Head of Macro Strategy

    We are witnessing a once-in-a-lifetime shredding of the global order. As the new order takes shape, ...
  • Asset allocation outlook: From Magnificent 7 to Magnificent 2,645—diversification matters, now more than ever

    Quarterly Outlook

    Asset allocation outlook: From Magnificent 7 to Magnificent 2,645—diversification matters, now more than ever

    Jacob Falkencrone

    Global Head of Investment Strategy

Disclaimer

The Saxo Group entities each provide execution-only service and access to Analysis permitting a person to view and/or use content available on or via the website is not intended to and does not change or expand on this. Such access and use are at all times subject to (i) The Terms of Use; (ii) Full Disclaimer; (iii) The Risk Warning; (iv) the Rules of Engagement and (v) Notices applying to Saxo News & Research and/or its content in addition (where relevant) to the terms governing the use of hyperlinks on the website of a member of the Saxo Group by which access to Saxo News & Research is gained. Such content is therefore provided as no more than information. In particular no advice is intended to be provided or to be relied on as provided nor endorsed by any Saxo Group entity; nor is it to be construed as solicitation or an incentive provided to subscribe for or sell or purchase any financial instrument. All trading or investments you make must be pursuant to your own unprompted and informed self-directed decision. As such no Saxo Group entity will have or be liable for any losses that you may sustain as a result of any investment decision made in reliance on information which is available on Saxo News & Research or as a result of the use of the Saxo News & Research. Orders given and trades effected are deemed intended to be given or effected for the account of the customer with the Saxo Group entity operating in the jurisdiction in which the customer resides and/or with whom the customer opened and maintains his/her trading account. Saxo News & Research does not contain (and should not be construed as containing) financial, investment, tax or trading advice or advice of any sort offered, recommended or endorsed by Saxo Group and should not be construed as a record of our trading prices, or as an offer, incentive or solicitation for the subscription, sale or purchase in any financial instrument. To the extent that any content is construed as investment research, you must note and accept that the content was not intended to and has not been prepared in accordance with legal requirements designed to promote the independence of investment research and as such, would be considered as a marketing communication under relevant laws.

Please read our disclaimers:
- Notification on Non-Independent Investment Research (https://www.home.saxo/legal/niird/notification)
- Full disclaimer (https://www.home.saxo/en-hk/legal/disclaimer/saxo-disclaimer)

None of the information contained here constitutes an offer to purchase or sell a financial instrument, or to make any investments. Saxo does not take into account your personal investment objectives or financial situation and makes no representation and assumes no liability as to the accuracy or completeness of the information nor for any loss arising from any investment made in reliance of this presentation. Any opinions made are subject to change and may be personal to the author. These may not necessarily reflect the opinion of Saxo or its affiliates.


Hong Kong

Contact Saxo

Hong Kong S.A.R
Hong Kong S.A.R

Saxo Capital Markets HK Limited (“Saxo”) is a company authorised and regulated by the Securities and Futures Commission of Hong Kong. Saxo holds a Type 1 Regulated Activity (Dealing in Securities); Type 2 Regulated Activity (Dealing in Futures Contract); Type 3 Regulated Activity (Leveraged Foreign Exchange Trading); Type 4 Regulated Activity (Advising on Securities) and Type 9 Regulated Activity (Asset Management) licenses (CE No. AVD061). Registered address: 19th Floor, Shanghai Commercial Bank Tower, 12 Queen’s Road Central, Hong Kong.

Trading in financial instruments carries various risks, and is not suitable for all investors. Please seek expert advice, and always ensure that you fully understand these risks before trading. Trading in leveraged products may result in your losses exceeding your initial deposits. Saxo does not provide financial advice, any information available on this website is ‘general’ in nature and for informational purposes only. Saxo does not take into account an individual’s needs, objectives or financial situation. Please click here to view the relevant risk disclosure statements.

The Saxo trading platform has received numerous awards and recognition. For details of these awards and information on awards visit www.home.saxo/en-hk/about-us/awards.

The information or the products and services referred to on this site may be accessed worldwide, however is only intended for distribution to and use by recipients located in countries where such use does not constitute a violation of applicable legislation or regulations. Products and services offered on this website are not directed at, or intended for distribution to or use by, any person or entity residing in the United States and Japan. Please click here to view our full disclaimer.

Apple, iPad and iPhone are trademarks of Apple Inc., registered in the US and other countries. AppStore is a service mark of Apple Inc. Android is a trademark of Google Inc.