
Access both platforms from your single Saxo account.

Asia Market Quick Take – 22 September, 2026

Asia Market Quick Take – 22 September, 2026
Key points:
- Macro: Trump to address UN and meet other world leaders including Xi
- Equities: Nasdaq Composite +2.2% for a record close as chip stocks rally
- FX: USD higher for the 5th straight session
- Commodities: Oil down for 4th session. Copper nears record levels
- Fixed income: Long end Treasury yields rally and yield curve flattens
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- Trump will address the UN today and may meet Iran’s President Pezeshkian, other Gulf leaders, and China’s Xi, as the US proposes a $5bn Middle East reconstruction fund. Saudi crude flows through Hormuz have reached about 2.9mn bpd in the past six days, with tanker capacity at its Gulf terminals at the highest since at least June.
- The Chicago Fed National Activity Index slipped to -0.04 in August 2026 from +0.08 in July, signaling slightly softer growth as production and sales/orders weakened, while employment, consumption, and housing improved modestly. The three-month average edged up to +0.01 from -0.01.
Equities:
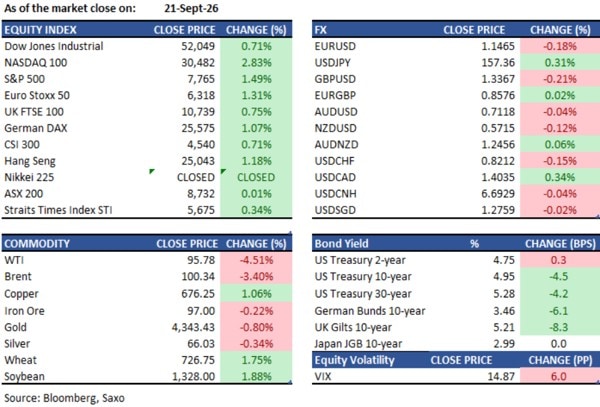
- US — US equities posted their best session since early August on Monday, driven by a surge in AI-related technology stocks. S&P 500 rose 1.5% to 7,764.70, the Nasdaq Composite jumped 2.3% to 27,122.09 — a record close and its 21st of 2026 — while the Dow gained 0.7% to 52,048.83. Meta surged 11% after early signs of success for its Muse AI agent, AMD climbed 10% crossing a $1 trillion market cap for the first time, Intel jumped 12%, and Akamai rose 12.3%. Energy was the standout decliner as oil prices fell. After hours, Vicor jumped 13% after raising Q3 revenue growth guidance to over 20% quarter-on-quarter, citing royalties from a new patent licence.
- EU — European equities rebounded sharply on Monday, with the Stoxx Europe 600 rising 1.0% to 641.93 — its biggest gain since 2 July — as cooling oil and gas prices eased inflation concerns and optimism around the US-China summit lifted risk appetite. The DAX gained 1.1% to 25,575.01, the FTSE 100 rose 0.7% to 10,739.01, the Euro Stoxx 50 climbed 1.3% to 6,318.20, and the SMI advanced 1.2% to 13,956.58. ASML led the Stoxx 600 higher, rising 2.5%, while Soitec surged 9.8%. Societe Generale gained as much as 4.9% after raising its 2029 return on tangible equity target to 13–14% and flagging up to €600 million in AI-driven cost savings. Novo Nordisk fell as much as 7.7% after its capital markets day disappointed investors seeking more concrete turnaround targets.
- Asia — Asian equities advanced broadly on Monday, led by chipmakers, as easing oil prices and Japan's markets were closed for a public holiday. Hang Seng Index rose 1.2% to 25,042.71, with Alibaba gaining 3.0% and Sino Biopharmaceutical surging 8.2%; mainland investors bought a net HK$4.07 billion via Stock Connect, the 11th consecutive day of net purchases. The Kospi surged 1.6% on Monday to 7,007.72, led by Samsung Electronics (+5.0%), and has extended gains at Tuesday's open, rising a further 2.2% to 7,161.61 as the SOX Index's 4.3% overnight gain fuels chip enthusiasm. The STI closed up 0.3% to 5,675.23. Tongcheng Travel fell as much as 7.1% in Hong Kong after a regulator opened a probe into its subsidiary over suspected unfair competition practices. Ligent Technologies, an AI optical transceiver maker, debuted in Hong Kong on Tuesday after raising HK$5.7 billion in its IPO, with shares rising as much as 8.9% in grey market trading.
Earnings this week:
- Tuesday: AutoZone (Q4 2026), KB Home (Q3 2026), Worthington Enterprises (Q1 2027)
- Wednesday: Cintas (Q1 2027), General Mills (Q1 2027)
- Thursday: Darden Restaurants (Q1 2027), Costco Wholesale (Q4 2026, after market), H&M, BlackBerry
Key Events:
- Thursday: Trump-Xi Summit
FX:
- Dollar broadly firm: The Bloomberg Dollar Spot Index edged higher on Monday, rising for a fifth time in six sessions, as Fed officials Goolsbee and Musalem both signalled further rate hikes are likely. Most G10 currencies declined against the dollar.
- Yen underperforms: USD/JPY held around 157.36, with the yen remaining vulnerable after the BOJ disappointed markets last Friday by not offering stronger guidance on the pace of future hikes. Thin liquidity due to Japan's public holiday on Monday amplified the yen's fragility.
- Korean won outperforms: USD/KRW fell as much as 1.2% to 1,370.50 on Monday — the biggest move since 7 September — as South Korea's early-September exports hit a record on semiconductor demand. The won was the best-performing major Asian currency on the day.
- EM currencies gain: Emerging market currencies rose broadly, supported by falling oil prices and positive US-China trade talk signals.
Commodities:
- Brent crude fell for a fourth consecutive day on Monday, dropping around 2% to approximately $101.80 per barrel, as signs emerged that Saudi Arabia is moving to restore capacity on its East-West pipeline following last week's drone strikes, and as diplomatic efforts to end the US-Iran war progressed. Brent is now sitting just above $100.34, on track for its longest losing streak since mid-June. WTI trades at $95.95.
- Gold futures trade at $4,370.60 per troy ounce, up approximately 0.5% on the session, as the metal continues to benefit from geopolitical uncertainty and elevated inflation concerns, despite a firmer dollar. Gold was down 0.9% on Monday's session per intraday data, reflecting some profit-taking as oil-driven risk appetite returned.
- Copper futures trade at 668.65 USd/lb (approximately $14,730/tonne), remaining elevated near multi-year highs driven by AI data centre buildout demand and ongoing tariff speculation. The metal has gained approximately 17% year-to-date, underpinned by structural supply-demand tightness.
Fixed income:
- US Treasuries rallied from the belly outward on Monday, with the 10-year yield falling approximately 4bps to 4.953% and the 30-year declining around 4bps to 5.286%, as lower oil prices eased inflation concerns. The move was supported by a simultaneous rally in European bonds, with German 10-year yields posting their biggest single-day drop in four months. The front end lagged, leaving the 2s10s spread at fresh lows since early March.
- The 2-year yield holds at 4.751%, near its highest level since 2023, as markets continue to price in additional Fed tightening — futures are pricing approximately 80bps of further hikes. Treasury trading volumes surged 14% in the week ending 18 September to $6.19 trillion, with 2-year note volume up 29%, reflecting intense positioning activity around the Fed's rate path.
- Scope Ratings downgraded France's credit score, with the government projecting debt rising to 121.7% of GDP in 2027. The French 10-year OAT yield stands at 4.56%, approximately 104 basis points over German Bunds, with the spread driven wider by concerns over France's ability to consolidate its budget deficit ahead of the presidential election cycle.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance. The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.