Quick Take Asia

Asia Market Quick Take – 22 September, 2026

Macro 6 minutes to read

Asia Market Quick Take – 22 September, 2026

Key points:

  • Macro: Trump to address UN and meet other world leaders including Xi
  • Equities: Nasdaq Composite +2.2% for a record close as chip stocks rally
  • FX: USD higher for the 5th straight session
  • Commodities: Oil down for 4th session. Copper nears record levels
  • Fixed income: Long end Treasury yields rally and yield curve flattens

------------------------------------------------------------------

 qt 2209

Disclaimer: Past performance does not indicate future performance.

Macro:

  • Trump will address the UN today and may meet Iran’s President Pezeshkian, other Gulf leaders, and China’s Xi, as the US proposes a $5bn Middle East reconstruction fund. Saudi crude flows through Hormuz have reached about 2.9mn bpd in the past six days, with tanker capacity at its Gulf terminals at the highest since at least June.
  • The Chicago Fed National Activity Index slipped to -0.04 in August 2026 from +0.08 in July, signaling slightly softer growth as production and sales/orders weakened, while employment, consumption, and housing improved modestly. The three-month average edged up to +0.01 from -0.01.

Equities:

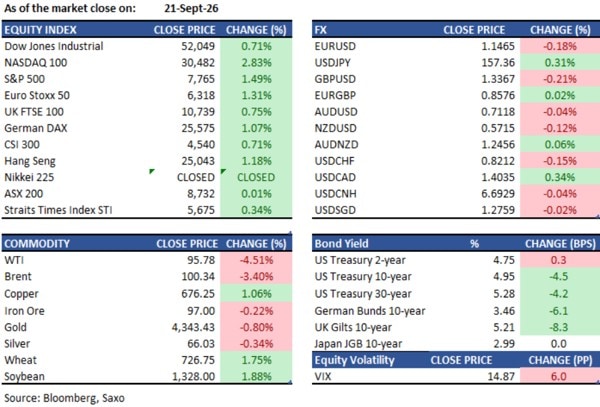
  • US — US equities posted their best session since early August on Monday, driven by a surge in AI-related technology stocks. S&P 500 rose 1.5% to 7,764.70, the Nasdaq Composite jumped 2.3% to 27,122.09 — a record close and its 21st of 2026 — while the Dow gained 0.7% to 52,048.83. Meta surged 11% after early signs of success for its Muse AI agent, AMD climbed 10% crossing a $1 trillion market cap for the first time, Intel jumped 12%, and Akamai rose 12.3%. Energy was the standout decliner as oil prices fell. After hours, Vicor jumped 13% after raising Q3 revenue growth guidance to over 20% quarter-on-quarter, citing royalties from a new patent licence.
  • EU — European equities rebounded sharply on Monday, with the Stoxx Europe 600 rising 1.0% to 641.93 — its biggest gain since 2 July — as cooling oil and gas prices eased inflation concerns and optimism around the US-China summit lifted risk appetite. The DAX gained 1.1% to 25,575.01, the FTSE 100 rose 0.7% to 10,739.01, the Euro Stoxx 50 climbed 1.3% to 6,318.20, and the SMI advanced 1.2% to 13,956.58. ASML led the Stoxx 600 higher, rising 2.5%, while Soitec surged 9.8%. Societe Generale gained as much as 4.9% after raising its 2029 return on tangible equity target to 13–14% and flagging up to €600 million in AI-driven cost savings. Novo Nordisk fell as much as 7.7% after its capital markets day disappointed investors seeking more concrete turnaround targets.
  • Asia — Asian equities advanced broadly on Monday, led by chipmakers, as easing oil prices and Japan's markets were closed for a public holiday. Hang Seng Index rose 1.2% to 25,042.71, with Alibaba gaining 3.0% and Sino Biopharmaceutical surging 8.2%; mainland investors bought a net HK$4.07 billion via Stock Connect, the 11th consecutive day of net purchases. The Kospi surged 1.6% on Monday to 7,007.72, led by Samsung Electronics (+5.0%), and has extended gains at Tuesday's open, rising a further 2.2% to 7,161.61 as the SOX Index's 4.3% overnight gain fuels chip enthusiasm. The STI closed up 0.3% to 5,675.23. Tongcheng Travel fell as much as 7.1% in Hong Kong after a regulator opened a probe into its subsidiary over suspected unfair competition practices. Ligent Technologies, an AI optical transceiver maker, debuted in Hong Kong on Tuesday after raising HK$5.7 billion in its IPO, with shares rising as much as 8.9% in grey market trading.

Earnings this week:

  • Tuesday: AutoZone (Q4 2026), KB Home (Q3 2026), Worthington Enterprises (Q1 2027)
  • Wednesday: Cintas (Q1 2027), General Mills (Q1 2027)
  • Thursday: Darden Restaurants (Q1 2027), Costco Wholesale (Q4 2026, after market), H&M, BlackBerry

Key Events:

  • Thursday: Trump-Xi Summit

FX:

  • Dollar broadly firm: The Bloomberg Dollar Spot Index edged higher on Monday, rising for a fifth time in six sessions, as Fed officials Goolsbee and Musalem both signalled further rate hikes are likely. Most G10 currencies declined against the dollar.
  • Yen underperforms: USD/JPY held around 157.36, with the yen remaining vulnerable after the BOJ disappointed markets last Friday by not offering stronger guidance on the pace of future hikes. Thin liquidity due to Japan's public holiday on Monday amplified the yen's fragility.
  • Korean won outperforms: USD/KRW fell as much as 1.2% to 1,370.50 on Monday — the biggest move since 7 September — as South Korea's early-September exports hit a record on semiconductor demand. The won was the best-performing major Asian currency on the day.
  • EM currencies gain: Emerging market currencies rose broadly, supported by falling oil prices and positive US-China trade talk signals.

Commodities:

  • Brent crude fell for a fourth consecutive day on Monday, dropping around 2% to approximately $101.80 per barrel, as signs emerged that Saudi Arabia is moving to restore capacity on its East-West pipeline following last week's drone strikes, and as diplomatic efforts to end the US-Iran war progressed. Brent is now sitting just above $100.34, on track for its longest losing streak since mid-June. WTI trades at $95.95.
  • Gold futures trade at $4,370.60 per troy ounce, up approximately 0.5% on the session, as the metal continues to benefit from geopolitical uncertainty and elevated inflation concerns, despite a firmer dollar. Gold was down 0.9% on Monday's session per intraday data, reflecting some profit-taking as oil-driven risk appetite returned.
  • Copper futures trade at 668.65 USd/lb (approximately $14,730/tonne), remaining elevated near multi-year highs driven by AI data centre buildout demand and ongoing tariff speculation. The metal has gained approximately 17% year-to-date, underpinned by structural supply-demand tightness.

Fixed income:

  • US Treasuries rallied from the belly outward on Monday, with the 10-year yield falling approximately 4bps to 4.953% and the 30-year declining around 4bps to 5.286%, as lower oil prices eased inflation concerns. The move was supported by a simultaneous rally in European bonds, with German 10-year yields posting their biggest single-day drop in four months. The front end lagged, leaving the 2s10s spread at fresh lows since early March.
  • The 2-year yield holds at 4.751%, near its highest level since 2023, as markets continue to price in additional Fed tightening — futures are pricing approximately 80bps of further hikes. Treasury trading volumes surged 14% in the week ending 18 September to $6.19 trillion, with 2-year note volume up 29%, reflecting intense positioning activity around the Fed's rate path.
  •  Scope Ratings downgraded France's credit score, with the government projecting debt rising to 121.7% of GDP in 2027. The French 10-year OAT yield stands at 4.56%, approximately 104 basis points over German Bunds, with the spread driven wider by concerns over France's ability to consolidate its budget deficit ahead of the presidential election cycle.

For a global look at markets – go to Inspiration.

This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance. The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.

Quarterly Outlook

01 /

  • Q1 Outlook for Traders: Five Big Questions and Three Grey Swans.

    Quarterly Outlook

    Q1 Outlook for Traders: Five Big Questions and Three Grey Swans.

    John J. Hardy

    Global Head of Macro Strategy

    Strap yourself in for key market questions that must be answered in 2026.
  • Q1 Outlook for Investors: “AI” party hangover needs discipline and diversification

    Quarterly Outlook

    Q1 Outlook for Investors: “AI” party hangover needs discipline and diversification

    Charu Chanana

    Chief Investment Strategist

    2026 is a high-valuation, high-dispersion year: the AI story matures, policy becomes less predictabl...
  • Q4 Outlook for Investors: Diversify like it’s 2025 – don’t fall for déjà vu

    Quarterly Outlook

    Q4 Outlook for Investors: Diversify like it’s 2025 – don’t fall for déjà vu

    Jacob Falkencrone

    Global Head of Investment Strategy

  • Q4 Outlook for Traders: The Fed is back in easing mode. Is this time different?

    Quarterly Outlook

    Q4 Outlook for Traders: The Fed is back in easing mode. Is this time different?

    John J. Hardy

    Global Head of Macro Strategy

    The Fed launched a new easing cycle in late Q3. Will this cycle now play out like 2000 or 2007?
  • Q3 Investor Outlook: Beyond American shores – why diversification is your strongest ally

    Quarterly Outlook

    Q3 Investor Outlook: Beyond American shores – why diversification is your strongest ally

    Jacob Falkencrone

    Global Head of Investment Strategy

  • Q3 Macro Outlook: Less chaos, and hopefully a bit more clarity

    Quarterly Outlook

    Q3 Macro Outlook: Less chaos, and hopefully a bit more clarity

    John J. Hardy

    Global Head of Macro Strategy

    After the chaos of Q2, the quarter ahead should get a bit more clarity on how Trump 2.0 is impacting...
  • Equity outlook: The high cost of global fragmentation for US portfolios

    Quarterly Outlook

    Equity outlook: The high cost of global fragmentation for US portfolios

    Charu Chanana

    Chief Investment Strategist

  • Commodity Outlook: Commodities rally despite global uncertainty

    Quarterly Outlook

    Commodity Outlook: Commodities rally despite global uncertainty

    Ole Hansen

    Head of Commodity Strategy

  • Upending the global order at blinding speed

    Quarterly Outlook

    Upending the global order at blinding speed

    John J. Hardy

    Global Head of Macro Strategy

    We are witnessing a once-in-a-lifetime shredding of the global order. As the new order takes shape, ...
  • Asset allocation outlook: From Magnificent 7 to Magnificent 2,645—diversification matters, now more than ever

    Quarterly Outlook

    Asset allocation outlook: From Magnificent 7 to Magnificent 2,645—diversification matters, now more than ever

    Jacob Falkencrone

    Global Head of Investment Strategy

Disclaimer

The Saxo Group entities each provide execution-only service and access to Analysis permitting a person to view and/or use content available on or via the website is not intended to and does not change or expand on this. Such access and use are at all times subject to (i) The Terms of Use; (ii) Full Disclaimer; (iii) The Risk Warning; (iv) the Rules of Engagement and (v) Notices applying to Saxo News & Research and/or its content in addition (where relevant) to the terms governing the use of hyperlinks on the website of a member of the Saxo Group by which access to Saxo News & Research is gained. Such content is therefore provided as no more than information. In particular no advice is intended to be provided or to be relied on as provided nor endorsed by any Saxo Group entity; nor is it to be construed as solicitation or an incentive provided to subscribe for or sell or purchase any financial instrument. All trading or investments you make must be pursuant to your own unprompted and informed self-directed decision. As such no Saxo Group entity will have or be liable for any losses that you may sustain as a result of any investment decision made in reliance on information which is available on Saxo News & Research or as a result of the use of the Saxo News & Research. Orders given and trades effected are deemed intended to be given or effected for the account of the customer with the Saxo Group entity operating in the jurisdiction in which the customer resides and/or with whom the customer opened and maintains his/her trading account. Saxo News & Research does not contain (and should not be construed as containing) financial, investment, tax or trading advice or advice of any sort offered, recommended or endorsed by Saxo Group and should not be construed as a record of our trading prices, or as an offer, incentive or solicitation for the subscription, sale or purchase in any financial instrument. To the extent that any content is construed as investment research, you must note and accept that the content was not intended to and has not been prepared in accordance with legal requirements designed to promote the independence of investment research and as such, would be considered as a marketing communication under relevant laws.

Please read our disclaimers:
- Notification on Non-Independent Investment Research (https://www.home.saxo/legal/niird/notification)
- Full disclaimer (https://www.home.saxo/en-hk/legal/disclaimer/saxo-disclaimer)

None of the information contained here constitutes an offer to purchase or sell a financial instrument, or to make any investments. Saxo does not take into account your personal investment objectives or financial situation and makes no representation and assumes no liability as to the accuracy or completeness of the information nor for any loss arising from any investment made in reliance of this presentation. Any opinions made are subject to change and may be personal to the author. These may not necessarily reflect the opinion of Saxo or its affiliates.


Hong Kong

Contact Saxo

Hong Kong S.A.R
Hong Kong S.A.R

Saxo Capital Markets HK Limited (“Saxo”) is a company authorised and regulated by the Securities and Futures Commission of Hong Kong. Saxo holds a Type 1 Regulated Activity (Dealing in Securities); Type 2 Regulated Activity (Dealing in Futures Contract); Type 3 Regulated Activity (Leveraged Foreign Exchange Trading); Type 4 Regulated Activity (Advising on Securities) and Type 9 Regulated Activity (Asset Management) licenses (CE No. AVD061). Registered address: 19th Floor, Shanghai Commercial Bank Tower, 12 Queen’s Road Central, Hong Kong.

Trading in financial instruments carries various risks, and is not suitable for all investors. Please seek expert advice, and always ensure that you fully understand these risks before trading. Trading in leveraged products may result in your losses exceeding your initial deposits. Saxo does not provide financial advice, any information available on this website is ‘general’ in nature and for informational purposes only. Saxo does not take into account an individual’s needs, objectives or financial situation. Please click here to view the relevant risk disclosure statements.

The Saxo trading platform has received numerous awards and recognition. For details of these awards and information on awards visit www.home.saxo/en-hk/about-us/awards.

The information or the products and services referred to on this site may be accessed worldwide, however is only intended for distribution to and use by recipients located in countries where such use does not constitute a violation of applicable legislation or regulations. Products and services offered on this website are not directed at, or intended for distribution to or use by, any person or entity residing in the United States and Japan. Please click here to view our full disclaimer.

Apple, iPad and iPhone are trademarks of Apple Inc., registered in the US and other countries. AppStore is a service mark of Apple Inc. Android is a trademark of Google Inc.