You can access all of our platforms from a single Saxo account.

Global Market Quick Take: Asia – July 15, 2024

Key points:
- Equities: US market rebound, closing week higher
- FX: USD boosted by rising Trump victory prospects following assassination attempt
- Commodities: Precious metals and oil fell
- Fixed income: Treasury yield remains under pressure
- Economic data: Republican convention, and China’s GDP (Q2) / Third Plenum
------------------------------------------------------------------
The Saxo Quick Take is a short, distilled opinion on financial markets with references to key news and events.
Disclaimer: Past performance does not indicate future performance.
In the news:
- US stock futures steady as markets digest Trump attack (Investing)
- 5 big analyst AI moves: Tesla and SMCI stocks downgraded (Investing)
- China's economy seen slowing in Q2 as stimulus calls grow (Investing)
- Japan data suggests possible yen intervention of around $22 billion (CNBC)
Macro:
- US PPI came in hotter than expected, but did not fully erase the optimism on rate cuts set in post-CPI given the details were soft. Headline came in at 0.2% MoM vs. 0.1% expected while the prior was revised up to 0.0% from -0.2%. The Y/Y also came in hot at 2.6%, above the 2.3% forecast, with the prior also seeing a revision higher from 2.2% to 2.4%. Core was also higher than expected on both fronts, with the M/M at 0.4% (exp. 0.2%, rev. 0.3%); Y/Y at 3% above the expected 2.5%, with revision upwards to the prior (prev. 2.3%, rev. 2.6%). Lastly, Supercore Y/Y again saw revisions upwards, printing 3.1% for June (prev. 3.2%, rev. 3.3%).
- The preliminary July University of Michigan survey was weak with headline sentiment falling to the lowest level since November 2023 at 66.0 from 68.2 in June, beneath the 68.5 consensus. The downside was met with a drop in both current conditions, falling to 64.1 from 65.9 (exp. 66.3), with the forward looking expectations dipping to 67.2 from 69.6. Meanwhile, year-ahead inflation expectations fell for the second consecutive month to 2.9% from 3% in June. The 5yr ahead forecasts also came in at 2.9%, down from 3.0% previously.
Macro events: Republican Convention, Eurogroup Meeting, Chinese GDP (Q2), Industrial Output/Retail Sales (Jun), Swiss PPI (Jun), US NY Fed Manufacturing (Jul), EZ Industrial Production (Jun); China's Third Plenum (15-18th July)
Earnings: Goldman Sachs, BlackRock, Guaranty, FirstBank, CrossFirst, Servis1st
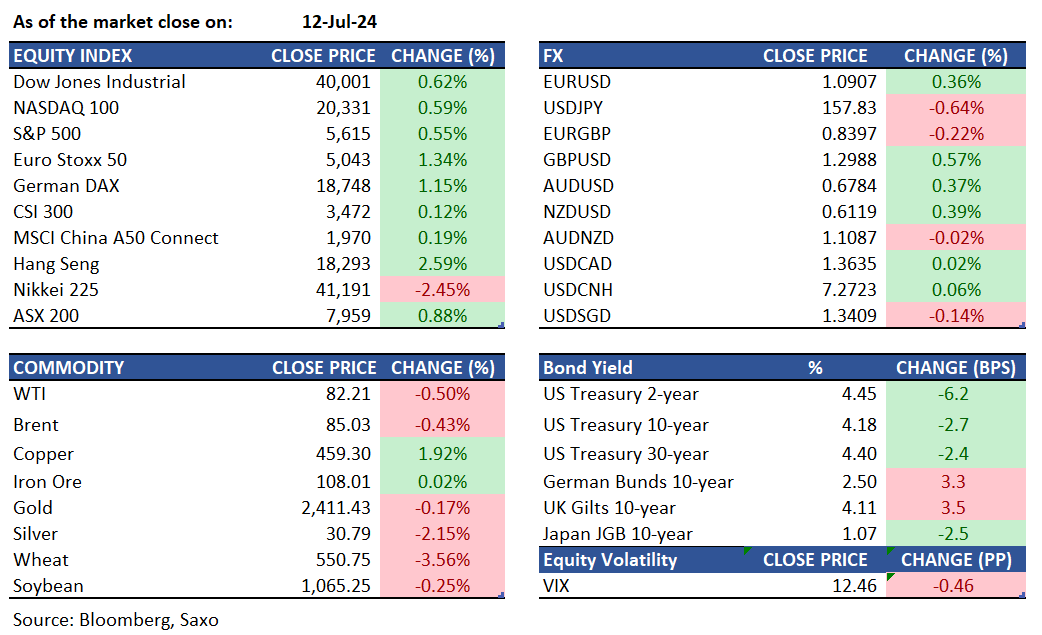
Equities: Equity markets demonstrated strong resilience on Friday, erasing most of Thursday's losses and closing the week higher. The Russell 2000 Smallcap Index, benefiting significantly from Thursday's tech selloff with a 3.5% rise, continued its upward trajectory, ending the week with a 5% gain. The S&P 500 and Nasdaq also showed sustained strength as investors capitalized on the brief decline in large-cap tech stocks. Geopolitical developments, particularly the attack on President Trump, may prompt safe-haven flows in Asian markets. Early indications show the USD slightly higher, while S&P 500 futures remain flat.
Fixed income: Treasuries advanced in the US afternoon session, reversing initial declines following the June PPI data. US 10-year note futures closed near the day's highs, while the yield curve steepened due to front-end gains, reinforcing expectations for at least two rate cuts this year. Increased activity in October fed funds futures indicated a potential half-point rate cut in September. Additionally, Treasury futures volumes surged 13% above the 20-day average, with 2-year notes trading 45% above typical levels.
Commodities: WTI crude oil futures declined by 0.5%, to close at $82.21 per barrel, ending a two-day winning streak and marking a 1.14% decrease for the week. Brent Crude futures also fell, settling at $85.03 per barrel, down 0.43%. Natural gas saw a late-week rebound, finishing up 0.43% for the week at $2.329. Gold prices slipped by 0.17% to $2,420.70 and silver price declined 2.15% to $30.79, achieving their third consecutive weekly gain as investor confidence grew regarding the U.S. Federal Reserve's potential interest rate cuts. Rice fell to a 12-month low of $14.57 per cwt. Over the past 4 weeks, it has declined by 21.32%.
FX: The US dollar opened higher following the assassination attempt on former President Donald Trump over the weekend as markets have increased the probability of a second Trump presidency. FX market liquidity was thin with Japan on holiday, but Mexican peso opened lower while the euro and Aussie slipped along with Chinese yuan amid risks of higher tariffs. China’s third plenum kicks off today, and focus would be on any reform announcements. The Swedish krona remained an underperformer in G10 as softer Sweden inflation supported the case for three rate cuts that Riksbank has guided for. British pound remained strong after hawkish BOE comments last week and UK CPI will be on the radar this week.
For all macro, earnings, and dividend events check Saxo’s calendar.
For a global look at markets – go to Inspiration.