
Access both platforms from your single Saxo account.

Bull vs Bear: Is it too late to short the AI trade?
Note: This is marketing material. This article is not investment advice, capital is at risk.
Source: Saxo UK
Is the AI trade over?
Investors keep asking whether that's it for the AI trade. The question should be: is the moment to short it over? Semiconductors and memory stocks peaked way back in June and have been on a steady decline through to last week's capitulation event on Thursday. That was either the clearing event required to kickstart rebuilding of positions, or it's a sign that the bottom has come out of the AI trade and confidence is shattered; cue rotation into defensive corners of the equity market, and even cash and bonds, supported by higher real rates.
The rally on Friday and Monday indicates investors are keen to buy the dip and it's easy to see when you look at the damage across a sector that still is a powerful engine of earnings growth.
Below are declines into last week's lows, rather than after this week’s rebounds.
Stock | AI exposure | Decline from June peaks to last week's lows |
IREN (IREN) | AI cloud/data centres | ~75% |
CoreWeave (CRWV) | GPU cloud | ~70% |
SanDisk (SNDK) | NAND flash/data-centre storage | ~66% |
Western Digital (WDC) | Data-centre storage | ~64% |
Intel (INTC) | Processors/foundry | ~63% |
Astera Labs (ALAB) | AI server connectivity | ~63% |
Arm (ARM) | Chip architecture/IP | ~62% |
Nebius (NBIS) | GPU cloud | ~62% |
Marvell (MRVL) | Custom AI chips/networking | ~58% |
Seagate (STX) | Data-centre storage | ~57% |
Lam Research (LRCX) | Chipmaking equipment | ~57% |
KLA (KLAC) | Chip manufacturing inspection | ~57% |
Applied Materials (AMAT) | Chipmaking equipment | ~55% |
Further up the market-cap scale, Micron was down roughly 47%, Broadcom 41% and AMD 38% from their respective intraday peaks to the 5 November close. The PHLX Semiconductor Index (SOXX) itself was down around 38% from June. Nvidia is down about 26% from its highs, though we might want to leave it to one side due the stock-specific issues related to its CEO.
Substantial parts of the AI infrastructure trade had already lost more than half their value before the latest leg lower. The damage spans the companies renting out computing capacity and the suppliers of connectivity, storage and manufacturing equipment—not just speculative AI software names.
As of 11 November: the bull case is that prices have fallen much faster than demand for AI or the fundamentals of the path of earnings growth; the bear case is that earnings and funding pressures are only beginning to catch up with an overleveraged sector that will not deliver what's promised.
Weighing it up
A lot of bad news is already priced in. Several infrastructure and semiconductor stocks have suffered 50–70% drawdowns. At the roughly 15× forward earnings Nvidia no longer requires an exuberant valuation to justify its price. Bears increasingly need earnings disappointments, rather than simply arguing that AI is expensive.
But just because bad news is priced in doesn't mean the market can't go lower. "Semiconductor earnings growth just hit 175% while stock prices collapsed from 130% gains to 9%. The gap between what companies are earning and what investors will pay has never been wider," notes Yardeni Research. "Historically, the y/y percent change in the Semiconductor stock price index has tended to peak before earnings growth peaked and bottom before it recovered. The latest divergence suggests that investors may already be anticipating a peak in earnings growth."
The earnings denominator could be next to fall. A low forward P/E depends on forecasts surviving. Slower deployments, weaker utilisation and monetisation, or falling computing prices could turn apparently cheap stocks into expensive ones.
Delayed investment could extend the cycle. UBS still sees strong cloud demand and computing-capacity orders. Morgan Stanley argues that construction constraints could shift projects from 2028 into 2029, stretching spending over a longer period and supporting pricing for existing capacity, which could favour established operators.
Rebounds can punish late shorts before fundamentals settle. IREN bounced 20% on Friday; AMD rose 11%, followed by another broader technology rally on Monday. With CoreWeavereporting strong numbers and Nvidia on 17 November, reassuring guidance could trigger further sharp recoveries. Nvidia, very much the poster child of the AI bet, has its own idiosyncratic risks in the wake of the China spygate story. Being bearish on the eventual outcome does not guarantee a profitable entry today.
Financing stress can become operational damage. CoreWeave’s borrowing costs have surged, with some bonds yielding 16% (it owes $47bn in debt), while SoftBank results include a roughly $7bn quarterly loss and data-centre-related write-downs of $3.7bn. Expensive refinancing, equity dilution and spending cuts could transmit weakness between developers, customers and chip suppliers. A large share-price decline does not repair a stretched balance sheet, nor does it mean it will stop falling.
A delay can still destroy equity value. Power, permitting and construction constraints may leave long-term AI demand intact while pushing revenue further away. Interest bills and infrastructure commitments remain. Microsoft’s tighter oversight of external cloud projects adds customer-concentration risk—particularly for leveraged providers that need rapid deployment to make their economics work.
Democrats will increase scrutiny of various aspects of the AI buildout, but it seems unlikely they will seek to cook the golden goose.Bears may be overdoing the impact of the midterms. CoreWeaveCEO Mike Intrator noted on the earnings call that the company does "not anticipate any impact from the seismic regulatory shift that’s occurred", though this is partly because almost all of CoreWeave’s power is online or is permitted and under construction.
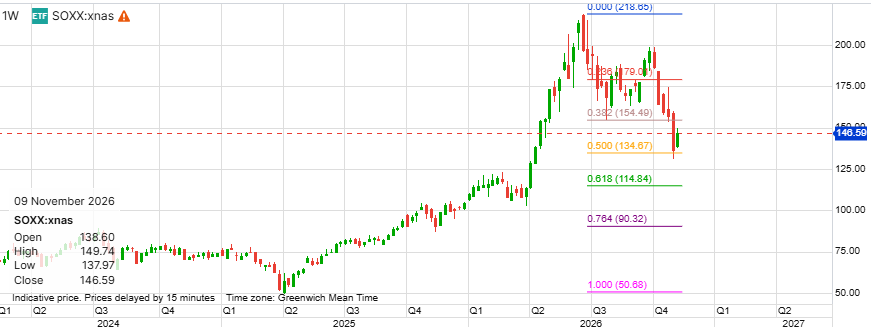
Looking at the charts – Semis have retraced half the rally off the Liberation Day lows made in April 2025.
Source: Saxo UK