
You can access both of our platforms from a single Saxo account.

Eight times the priced move - Options Brief - 6 November 2026
Summary: One-day volatility tripled on Thursday and now sits at the top of the whole curve, hours before payrolls. Is the market pricing one rough session, or the start of something longer?
One-day volatility tripled into payrolls, and the curve now falls from the nearest tenor to the furthest.
MARKET REGIME: HIGH VOL BEAR | VIX 28.18 | TERM STRUCTURE: BACKWARDATION | SKEW: ELEVATED (149.37) | FRONT-MONTH VIX FUTURES: 23.750
Today in brief
Thursday’s session ran far beyond what the options market had priced for it. US chip and AI stocks sold off hard, the S&P 500 fell 4.36% and the Nasdaq 100 6.36%, and the cost of protection jumped. The jump was biggest for the shortest horizon. The one-day volatility gauge, which measures what options charge for protection over the next session, rose 204.64% to 36.80, while the one-year gauge rose only 12.69%. Protection for a longer period normally costs more than protection for a shorter one. This morning it is the other way round, and in our view that may suggest the market sees most of the risk in the next few days rather than the next few months.
Same-day options are part of that story. These are options that expire at the close of the day they trade, and on Thursday morning they priced a move of about 0.55% for the S&P 500. The index fell 4.36%, roughly eight times as far. The market makers who sell these options usually protect themselves by trading the index itself. When the market falls much further than expected, that protection tends to mean selling as prices drop, which can push the market lower still. In our view that may have added to Thursday’s fall rather than softened it. The selloff started in chip and AI stocks: same-day options, in our view, may have made the move bigger rather than caused it, and the data we hold cannot measure by how much.
Today brings its own test. Options price about 110 points, 1.49%, for today’s S&P 500 expiry, which includes the US jobs report at 14:30 CET. A day earlier the same expiry priced 0.87%, and the passing of one day alone would have brought that down to about 0.61%. In our view the gap may show how much extra protection buyers added overnight. Implied correlation, a gauge of how closely stocks are expected to move together, rose 72.26% to 20.93, the highest in our 104-session history. That may suggest the market expects stocks to keep moving as one block.
One reading cuts the other way. SKEW, which tracks the price of protection against a very sharp fall, slipped 1.01% to 149.37 while the VIX rose almost 70%. In our view that may suggest buyers paid up for the next few sessions rather than for a crash.
The S&P 500 closed at 7,353.73, below the whole range options had priced for this week, having used 162% of it to the downside with one session left. The typical single stock’s volatility rank rose to 43.8 from 37.0, and Nvidia’s reached 97.8. Among the largest trades in index funds, put options outnumbered calls about four to one. Past performance is not indicative of future results.
That is the whole brief in one read. The sections below hold the detail behind each paragraph, with the charts, the full set of readings and the sources, for when you want to go deeper on one part.
Headline driver
A selloff in AI and chip stocks deepened on Thursday, which the Saxo Market Quick Take links to concern that a Democratic Congress could bring closer scrutiny of the AI industry and slow the data-centre buildout. The S&P 500 fell 4.36% and the Nasdaq 100 6.36%, the weakest US session since April 2025 by the same account. Nvidia lost 9.26%, AMD about 17.3% and Qualcomm about 9.5% after its guidance.
The selling reached Asia on Friday: the Kospi fell 4.89% by 05:00 CET after a trading halt, and the Nikkei dropped more than 6% intraday. Jobless claims fell to 189,000 and the Bank of England raised rates to 4%. Payrolls land at 14:30 CET.
Market snapshot
- US (Thursday 5 November close): S&P 500 7,353.73, down 4.36%. Nasdaq 100 26,629.81, down 6.36%. Dow Jones Industrial Average 51,528.16, down 3.44%. The equal-weighted S&P 500 fell 2.89%. The semiconductor fund dropped 11.21% and the technology fund 8.00%, while utilities fell 0.71% and communication services 0.59%.
- Europe: the Stoxx 600 fell 0.38% to 654.88 and the DAX 0.43% to 26,325.01, while the CAC 40 rose 0.34% to 8,205.37. Euro Stoxx 50 futures traded 0.95% below their settlement at 05:00 CET.
- Asia (Friday morning): the Kospi fell 4.89% to 5,120.69 by 05:00 CET, the Hang Seng 1.08% to 24,528.57 and the CSI 300 1.48%.
- Commodities and rates: Brent trades at 100.56 and WTI at 91.69. Gold futures trade at 4,055.10 and silver at 51.52. The two-year Treasury yield trades near 4.48% and the ten-year near 4.85%, the two-year lower on Thursday. Bitcoin trades near 75,800. S&P 500 futures sat 0.08% above their settlement and Nasdaq 100 futures 0.92% above.
- Market regime: high volatility bear, the VIX at 28.18, the curve in backwardation and SKEW elevated at 149.37.
Index levels and volatility readings from the watchlist export taken at 05:00 CET on 6 November 2026, which carries Thursday’s US closes and overnight futures; the Nikkei, single-stock moves and the policy context from the same-morning Saxo Market Quick Take. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
Volatility surface
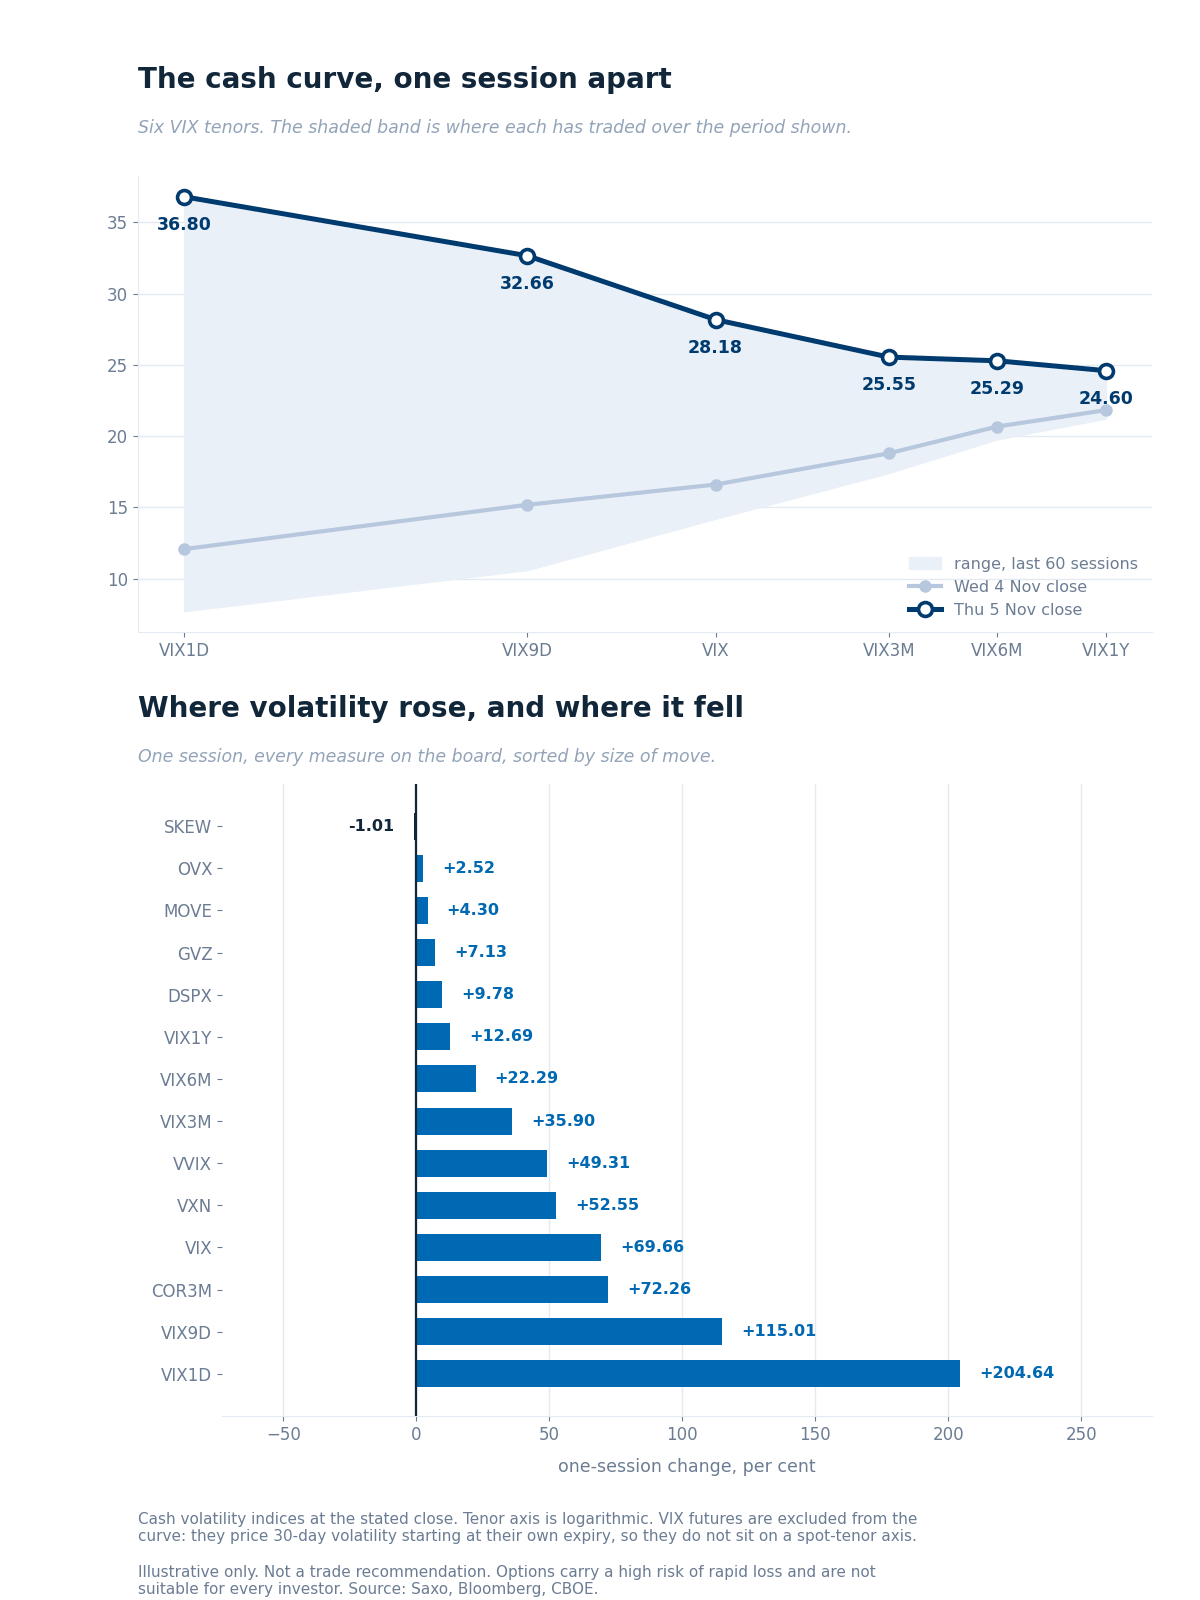
The cash curve at Thursday’s close against Wednesday’s, over each tenor’s 60-session range, with the one-session change across every measure. Illustrative only. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
The curve turned upside down: longer protection normally costs more, and now the nearer the tenor, the higher it sits. The one-day gauge rose 204.64% to 36.80, the nine-day 115.01% to 32.66 and the VIX 69.66% to 28.18, while the three-month rose 35.90% to 25.55, the six-month 22.29% to 25.29 and the one-year 12.69% to 24.60. Each tenor closed at a high in our 104-session store, after its largest one-session rise there. VIX futures stay off the chart, since each prices a month from its own expiry.
Ratios. The one-day gauge sits at 1.31 times the VIX, from 0.73 a day earlier. VIX3M/VIX fell to 0.91 from 1.13, and VXN/VIX to 1.36 from 1.51.
VIX futures. November trades at 23.75, 15.7% below spot and above December at 21.65. Put-call parity on the 18 November options returned 24.55, in line with Thursday’s settlement, which suggests the series has not rolled.
Tails and correlation. SKEW, which tracks the price of protection against a sharp fall, slipped 1.01% to 149.37, above its 146.04 median. Implied correlation, a gauge of how closely stocks are expected to move together, rose 72.26% to 20.93, a store high, while the dispersion index rose 9.78% to 41.31.
Single-name volatility
Single-name volatility rose, led by the index funds. On a common set of 522 underlyings the median implied-volatility rank rose to 43.8 from 37.0, and the mean to 46.3 from 40.0, with 385 names up and 129 down. Names at a rank of 80 or more rose to 55 from 29.
The index measures above moved most. The Nasdaq 100 fund’s rank rose to 100 from 52.0, the technology fund’s to 98.0 from 49.3 and the S&P 500 fund’s to 63.6 from 17.0. The semiconductor fund reached 93.8 from 47.3, Nvidia 97.8 from 65.9, at the 99.6th percentile of its year, and Tesla 82.0 from 29.7.
The split was regional. The US median rose to 57.1 from 42.0, the euro-zone median only to 36.7 from 34.5. Qualcomm, which reported, eased to 47.4 from 49.3, which may reflect its event premium coming out.
Implied-volatility rank and percentile from the Saxo screener, read overnight on 6 November 2026, carrying Thursday’s close. Source: Saxo.
Options flow sentiment
Based on end-of-day Thursday 5 November, yesterday’s positioning, not today’s price action.
- Single-name flow was dominated by deep in-the-money and negotiated packages with no readable direction; the few side-clean trades were small and mixed.
- Sector and ETF flow leaned to puts: among the largest index-fund prints, puts outnumbered calls about four to one, though most of the premium sat in deep in-the-money packages and same-day protection showed up only late in the session.
Same-day options. Options that expire on the day they trade priced a move of about 0.55% for the S&P 500 on Thursday morning; the index fell 4.36%, roughly eight times as far. Market makers who sell these options usually hedge by trading the index, and when prices fall well past what was priced, that hedging tends to mean selling into the decline. In our view that may have added to the fall rather than cushioned it, though the data we hold cannot measure how much.
Where the week's range sits
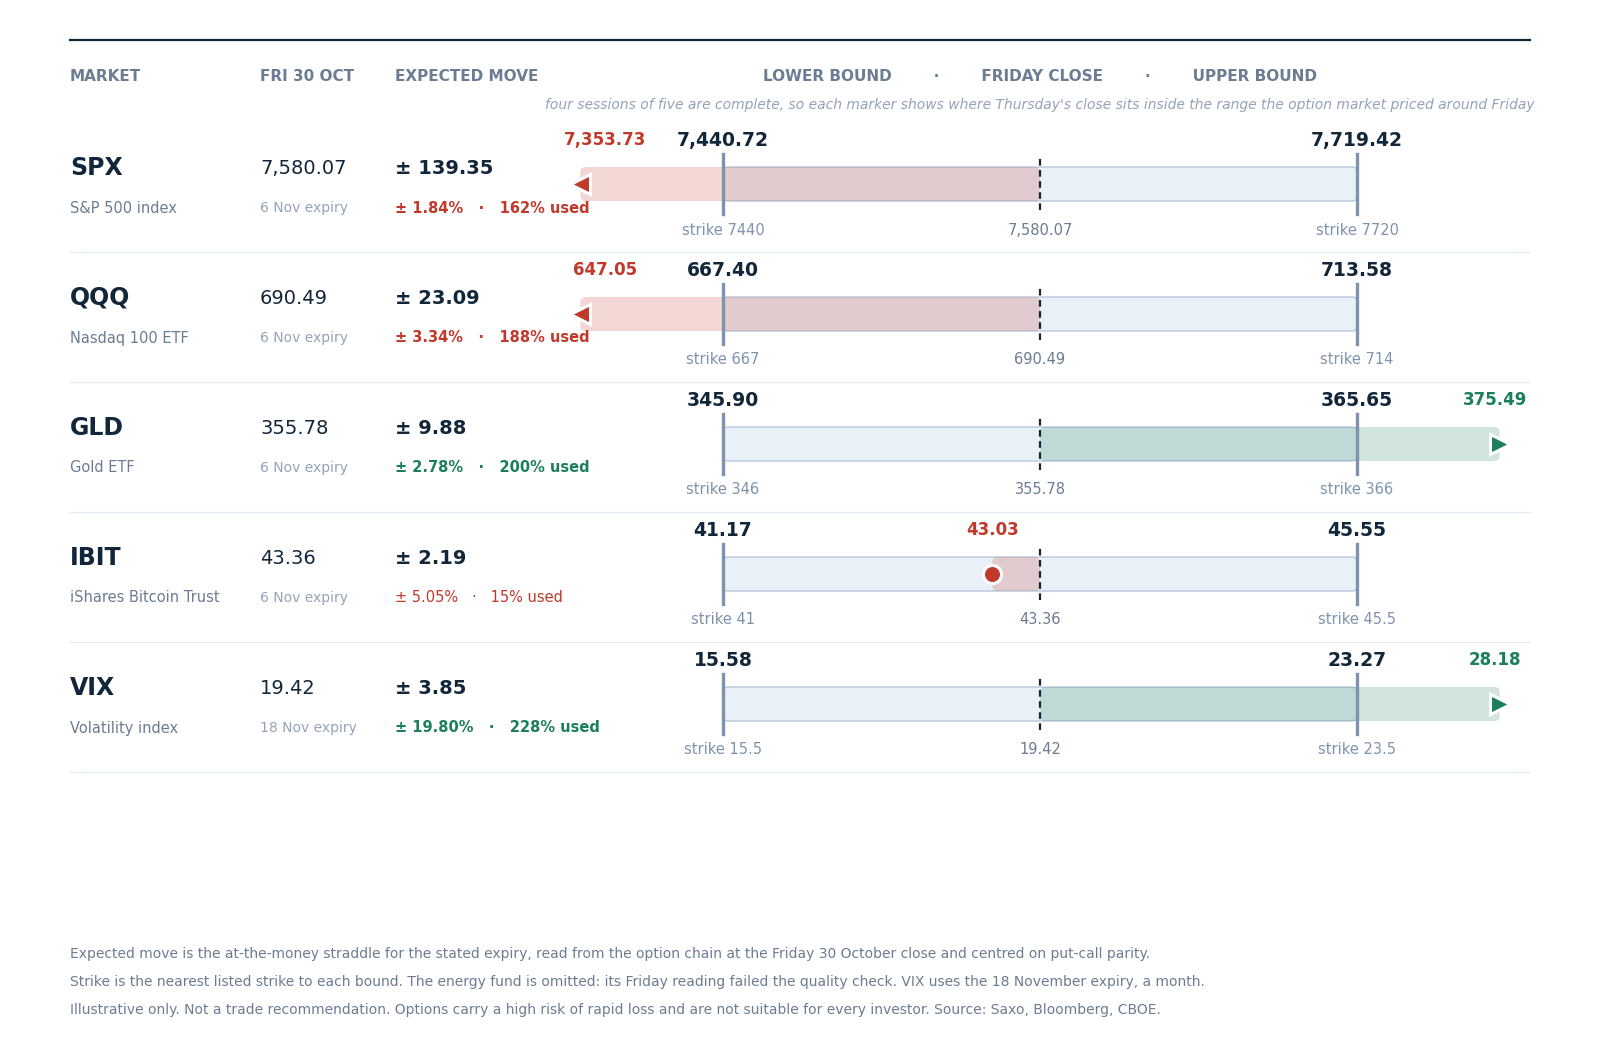
The range the option market priced for this week around Friday 30 October’s close, with each market’s Thursday close marked inside it. Illustrative only, not a trade recommendation. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
The S&P 500 began the week with 139.35 points priced around Friday’s 7,580.07 close, 1.84%, from 7,440.72 to 7,719.42. Thursday’s close at 7,353.73 has used 162% of that band to the downside, against 78% to the upside a day earlier, with one session left.
Four of the five rows sit outside their bands. The Nasdaq 100 fund has used 188% downward and the gold fund 200% upward, while the bitcoin fund has used only 15% downward. The volatility row uses the 18 November expiry, so it measures a month, not a week, and has used 228% of its band upward. The energy fund’s Friday reading failed our quality check and is left out.
Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply and vary by account and venue; check the rates applicable to you.
Today's catalysts
- 08:00 CET German industrial production for September.
- 14:30 CET US October payrolls, unemployment rate and average hourly earnings; 16:00 CET University of Michigan sentiment, preliminary for November.
- Earnings today: Enbridge and Moderna.
- Next week: Cisco and Applied Materials report on Thursday; the Fed decides on 9 December.
Earnings scorecard
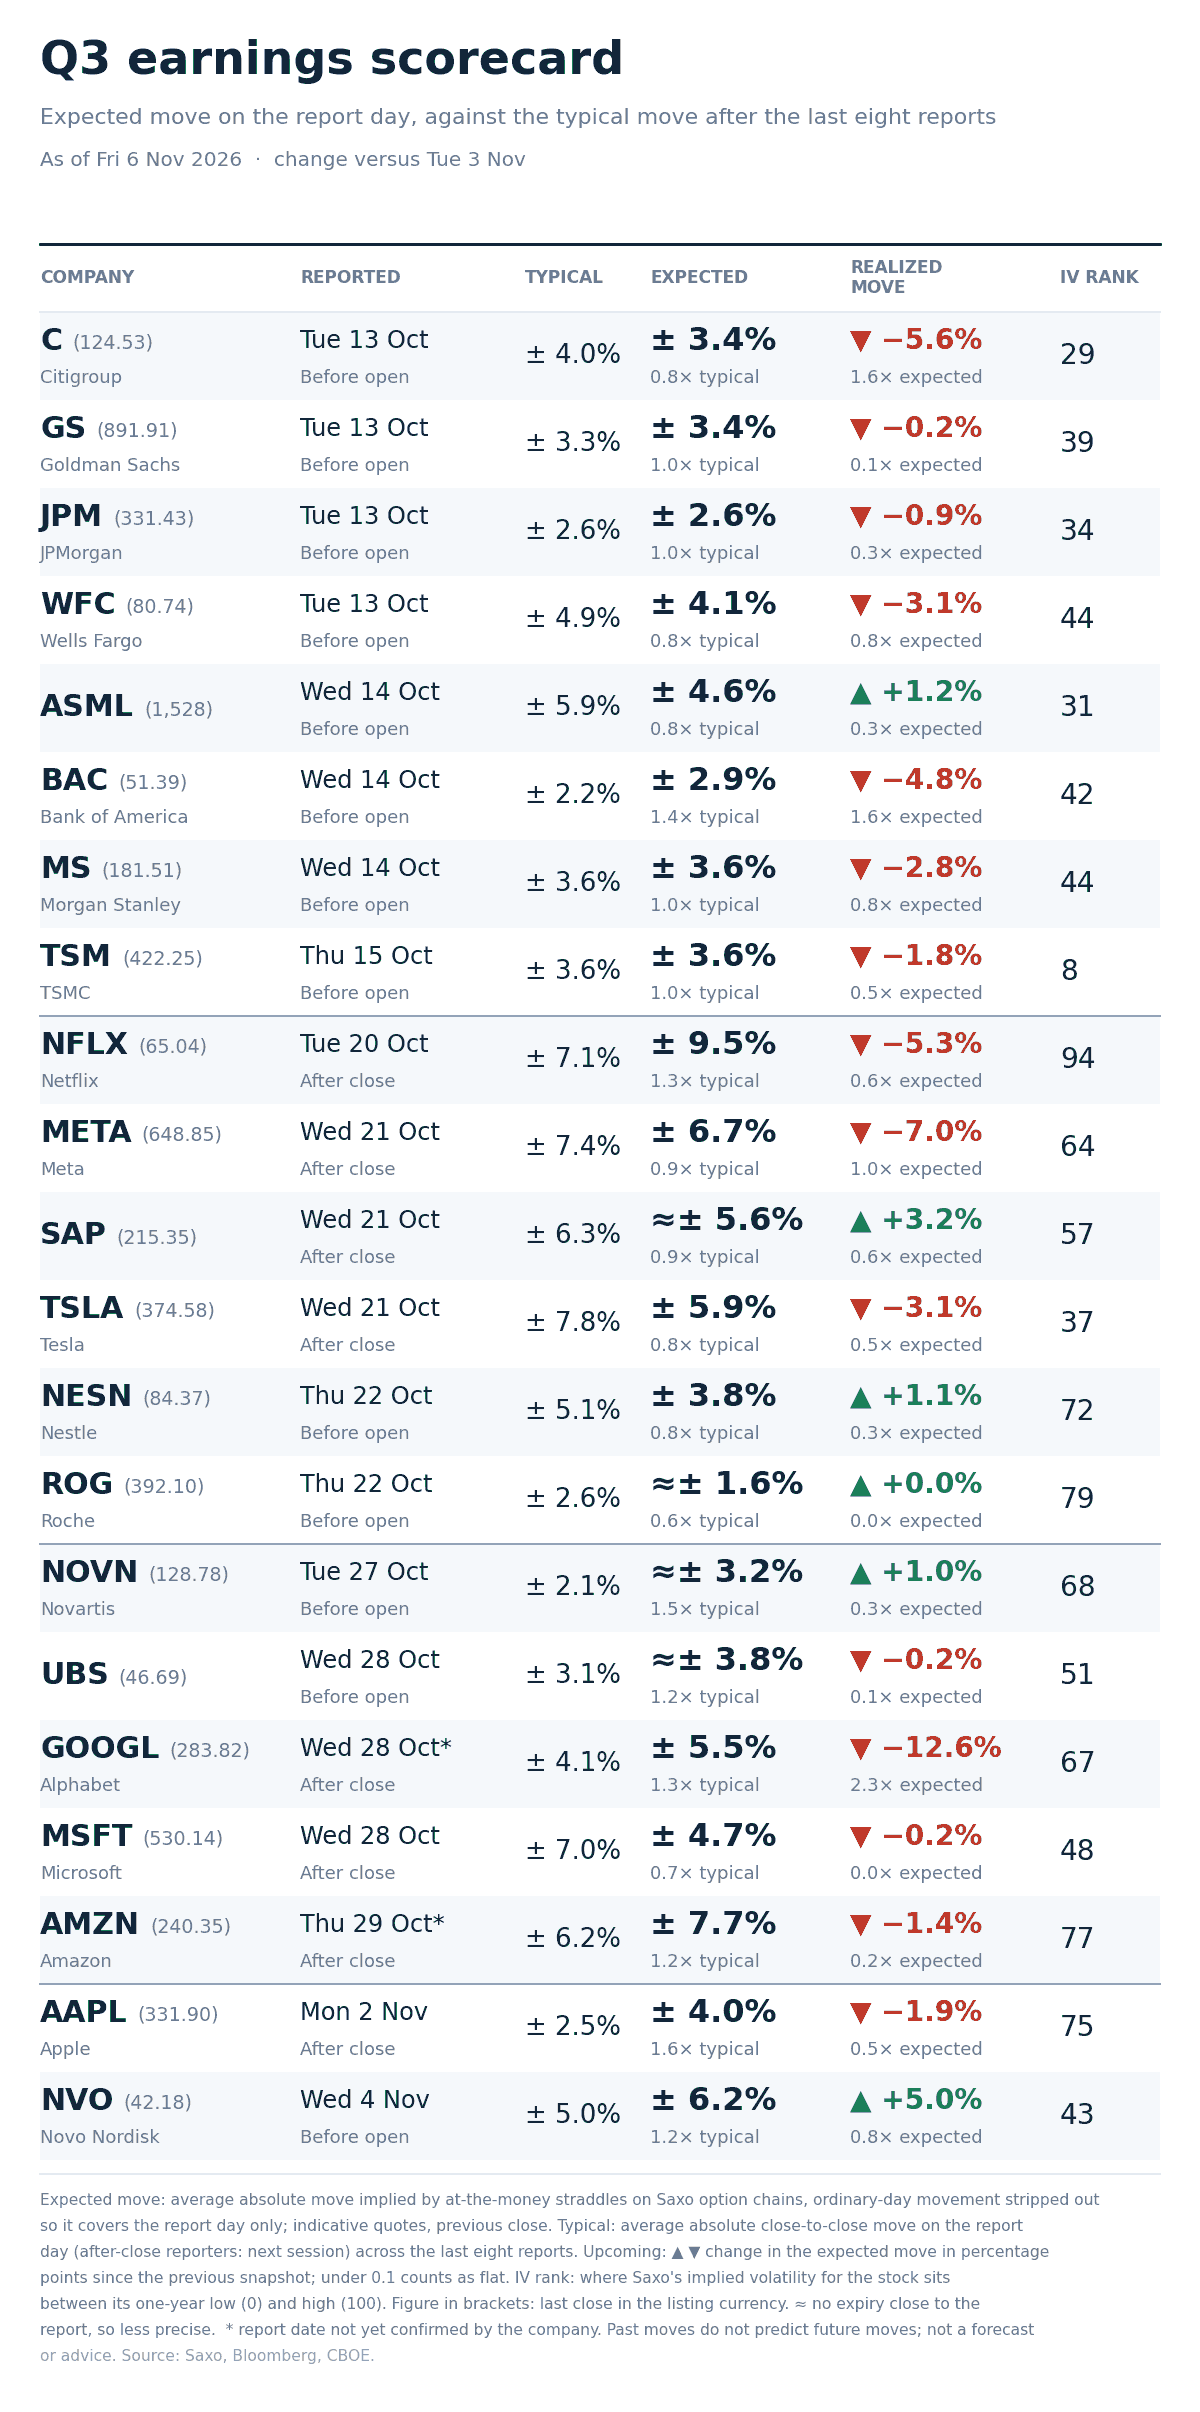
Option-implied expected move for each report day against the stock’s average move after its last eight reports, across the twenty-one names tracked this season. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
The board is closed and its figures are unchanged. Across the twenty-one names the median moved about 0.5 times what was priced, and four moved at least as much as priced: Citigroup, Bank of America, Meta and Alphabet.
In our view the season leaned toward report-day premium that was larger than the moves that followed. Thursday’s selloff arrived after the last report, so it does not change the tally.
Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply and vary by account and venue; check the rates applicable to you. Past performance is not indicative of future results.
What the market is pricing
- Session implied range: S&P 500 options price about 110 points, 1.49%, for today’s expiry, which holds payrolls. The quotes are indicative before the open, and S&P 500 futures sat 0.08% above their settlement at 05:00 CET. The one-day gauge at 36.80 implies about 2.32%, a one-sigma figure rather than an expected move.
- Event repricing: yesterday the 6 November expiry priced 0.87% with two sessions to run. Time decay alone would have left about 0.61%. Today it prices 1.49%, more than double the decay figure, so in our view the market may have added back far more than the election premium it took out on Wednesday.
- Curve read: the one-day gauge now sits 31% above the VIX, while the three-month sits 9% below it. In our view that leans toward a market that sees more risk in the next few sessions than further out.
- Tail read: SKEW slipped while the VIX rose almost 70%, and implied correlation reached a store high. In our view that may suggest a market paying for stocks to move together in the near term rather than for a sharp fall in the far tail.
In our view the next test may be whether the front of the curve gives back any of Thursday’s jump once payrolls are out at 14:30 CET, in a week whose index range is already 162% used to the downside. Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply and vary by account and venue; check the rates applicable to you. Past performance is not indicative of future results.
| More from the author |
|---|