
Un seul compte Saxo suffit pour accéder à nos plateformes.

Nvidia beats into an inverted volatility curve - Options Brief - 18 November 2026
Options
Résumé: Options charged more for the next session than for the next three months going into Nvidia’s results. Nvidia then beat, and its after-hours move stayed inside the price. What is the market paying for now?
Nvidia beat after the close, into a market that had just paid more for protection over the next session than over the next three months.
MARKET REGIME: HIGH VOL BEAR | VIX 25.46 | TERM STRUCTURE: BACKWARDATION (FRONT) | SKEW: ELEVATED (145.11) | FRONT-MONTH VIX FUTURES: 22.42
Today in brief
The option market went into Nvidia’s results paying more for the next session than for the next three months. The one-day volatility gauge, which measures what options charge for protection over the next session, jumped 35.69% to 26.84, above the VIX at 25.46 and the three-month gauge at 24.98. Today’s S&P 500 expiry prices about 1.25% and Friday’s about 2.04%, which leaves about 1.61% for Thursday and Friday. Time alone would have taken yesterday’s 1.98% for Friday down to about 1.71%, so in our view traders may have added premium for the week again.
Nvidia then beat. Revenue came in at USD 115.8 billion against a consensus near USD 109 billion, and the shares rose 4.8% after the close, according to the Saxo Market Quick Take. Its options had priced a report-day move of about 7.7%, nearly twice its own average, so the after-hours move sat inside that price, as it did for 17 of the other twenty-one reports tracked this season.
Two readings cut the other way. Implied correlation, a gauge of how closely stocks are expected to move together, jumped 17.64% to 18.74, while SKEW, a gauge of what crash protection on the index costs, eased. In our view that may suggest traders paid for wide moves in which stocks travel together rather than for a crash, and yesterday’s sector and fund options flow showed no demand for near-term or tail protection.
Backdrop: the S&P 500 fell 1.03% to 7,340.53 on Tuesday, a fourth straight loss, and sits below the range priced for the week, using 164% of it. The typical single name’s volatility rank rose to 40.0 from 36.1, and today’s session carries the first cash reaction to Nvidia and the Fed minutes at 20:00 CET.
That is the whole brief in one read. The sections below hold the detail behind each paragraph, with the charts, the full set of readings and the sources, for when you want to go deeper on one part.
Headline driver
Nvidia reported fiscal third-quarter revenue of USD 115.8 billion after Tuesday’s close, above a consensus near USD 109 billion, and guided the fourth quarter to about USD 130 billion against expectations near USD 125 billion, according to the Saxo Market Quick Take. Its shares rose 4.8% after the close, and this morning S&P 500 futures are up about 0.8% and Nasdaq 100 futures about 1.4%.
The beat lands on a market that had sold off into it. US stocks fell for a fourth straight session on Tuesday, with all eleven sectors lower, and Europe had its worst day since March. US retail sales rose 0.2% in October against 0.1% expected, and St. Louis Fed President Musalem said several rate increases are likely to be needed before spring 2027. The Fed minutes follow tonight.
Market snapshot
- US (Tuesday 17 November close): S&P 500 7,340.53, down 1.03%, its lowest close since July according to the Quick Take. Nasdaq 100 27,001.78, down 0.72%. The Dow fell 1.65% to 50,764.09 and the equal-weighted S&P 500 1.45%. Small caps fell 1.43%, Microsoft 2.27% and the software fund 3.29%, while the semiconductor fund slipped 0.39% and Nvidia 0.44% to 155.46 before its results.
- Europe (Tuesday close): the Stoxx 600 fell 1.75% to 650.73, the Euro Stoxx 50 2.15% to 6,212.12 and the DAX 2.08% to 26,045.37. SAP lost 5.6%, ASML 5.3% and Deutsche Bank 6%.
- Asia (Wednesday, 05:00 CET): the Kospi was up 0.98%, after rising as much as 3.1% early, while the Hang Seng was down 1.13% and China’s CSI 300 0.49%.
- Commodities and rates: Brent traded near 92.10 on the January contract and gold fell to a 14-month low near 3,780, according to the Quick Take, with silver futures at 45.83. The ten-year Treasury yield eased to 5.08% from 5.13% and the two-year to 4.79% from 4.82%.
- Market regime: high volatility bear, with the VIX at 25.46 and the S&P 500 4.11% below its 50-day average.
Index levels and volatility readings from the watchlist export taken at 05:00 CET on 18 November 2026, which carries Tuesday’s US and European closes and early Asian trading; Nvidia’s results, sector breadth, European single names, Brent and gold from the same-morning Saxo Market Quick Take. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
Volatility surface
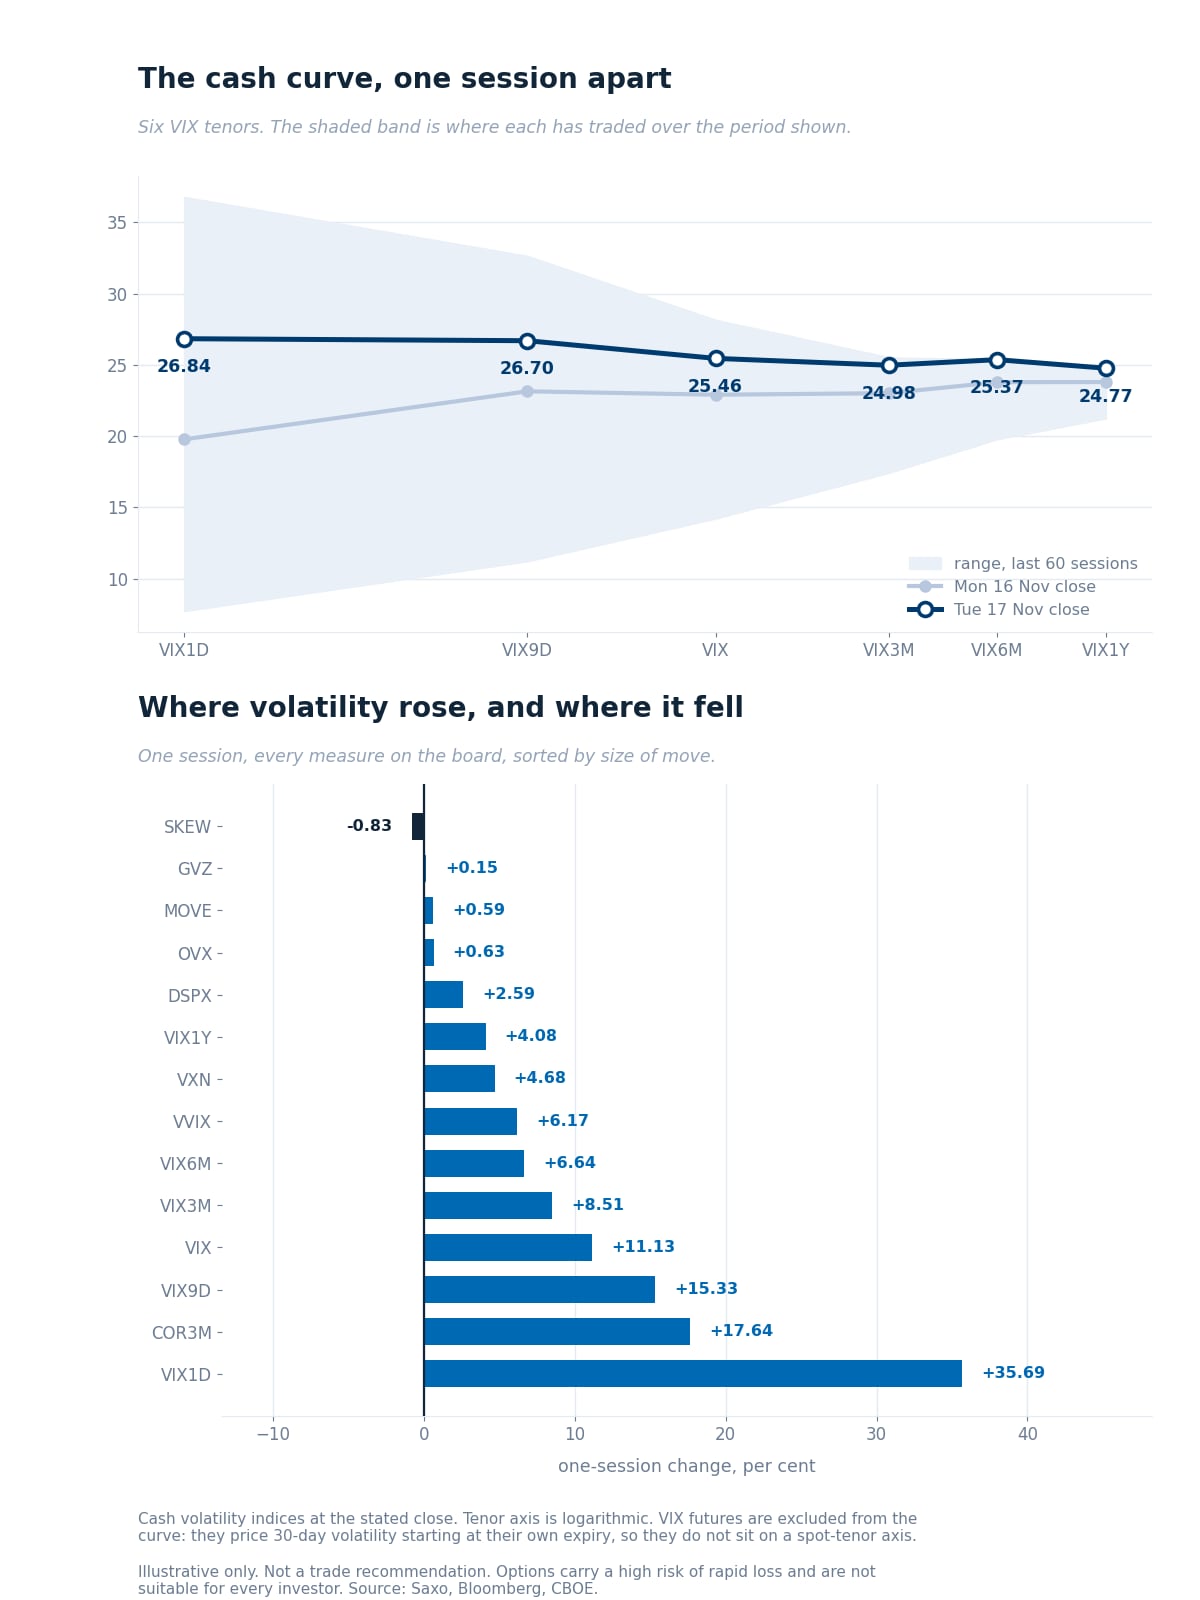
The cash curve at Tuesday’s close against Monday’s, over each tenor’s 60-session range, with the one-session change across every measure. Illustrative only. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
The front of the curve now sits above the back. The one-day gauge jumped 35.69% to 26.84, above the nine-day at 26.70, the VIX at 25.46 and the three-month at 24.98, so the next session costs more than the next three months. The year-ahead gauge rose only 4.08% to 24.77. VVIX, the volatility of the VIX, rose 6.17% to 121.28, while MOVE, the Treasury volatility gauge, barely moved at 101.89. VIX futures stay off the chart, since each prices a month from its own expiry.
Ratios. VIX3M/VIX fell to 0.98 from 1.00. VXN/VIX eased to 1.35 from 1.44.
VIX futures. The November contract settles this morning. A parity check on the December options puts that contract at about 22.42, up from 20.98 on the same check a session earlier, and January at about 22.45, so the two sit level, about 3 points below spot.
Tails and correlation. SKEW eased 0.83% to 145.11, below its 60-session median of 149.22. Implied correlation, a gauge of how closely stocks are expected to move together, jumped 17.64% to 18.74, against a 60-session median of 11.73, and the dispersion index rose 2.59% to 41.24, close to its 60-session high.
Single-name volatility
Single-name volatility rose again. On a common set of 520 underlyings the median implied-volatility rank rose to 40.0 from 36.1, with 439 names up and 74 down, and the count at a rank of 80 or more rose to 44 from 28. The US median rose to 54.5 from 49.3 and the euro-zone median to 31.5 from 26.8.
The index funds kept climbing. The Nasdaq 100 fund’s rank rose to 93.9 from 81.5, the S&P 500 fund’s to 64.8 from 53.1 and the small-cap fund’s to 48.1 from 37.9. The semiconductor fund rose to 90.8 and Broadcom reached 100.0, with Nvidia still at 100.0 into its report. Financials joined in: the financials fund rose to 52.6 from 41.2 and the regional bank fund to 44.8 from 25.1. Microsoft rose to 55.7 from 43.7.
Reporting cuts the other way. Disney’s rank fell to 37.8 from 79.6 and Home Depot’s to 48.3 from 72.6, once their results were out.
Implied-volatility rank from the Saxo screener, read at about 03:00 CET on 18 November 2026, carrying Tuesday’s close, against the reading carrying Monday’s close. Source: Saxo.
Options flow sentiment
Based on end-of-day Tuesday 17 November, yesterday’s positioning, not today’s price action.
- Single-name flow had no readable direction overall, with most large positions crossed at mid-market. Upside positions in Nvidia into its results were bought, and crypto-linked names were the one clearly bearish area.
- Sector and ETF flow leaned to puts on the index, but mostly long-dated, with no demand for near-term or tail protection. Financials protection moved further out in time, and the one clear directional lean was in positions that gain if long-dated Treasury yields fall.
Where the week's range sits
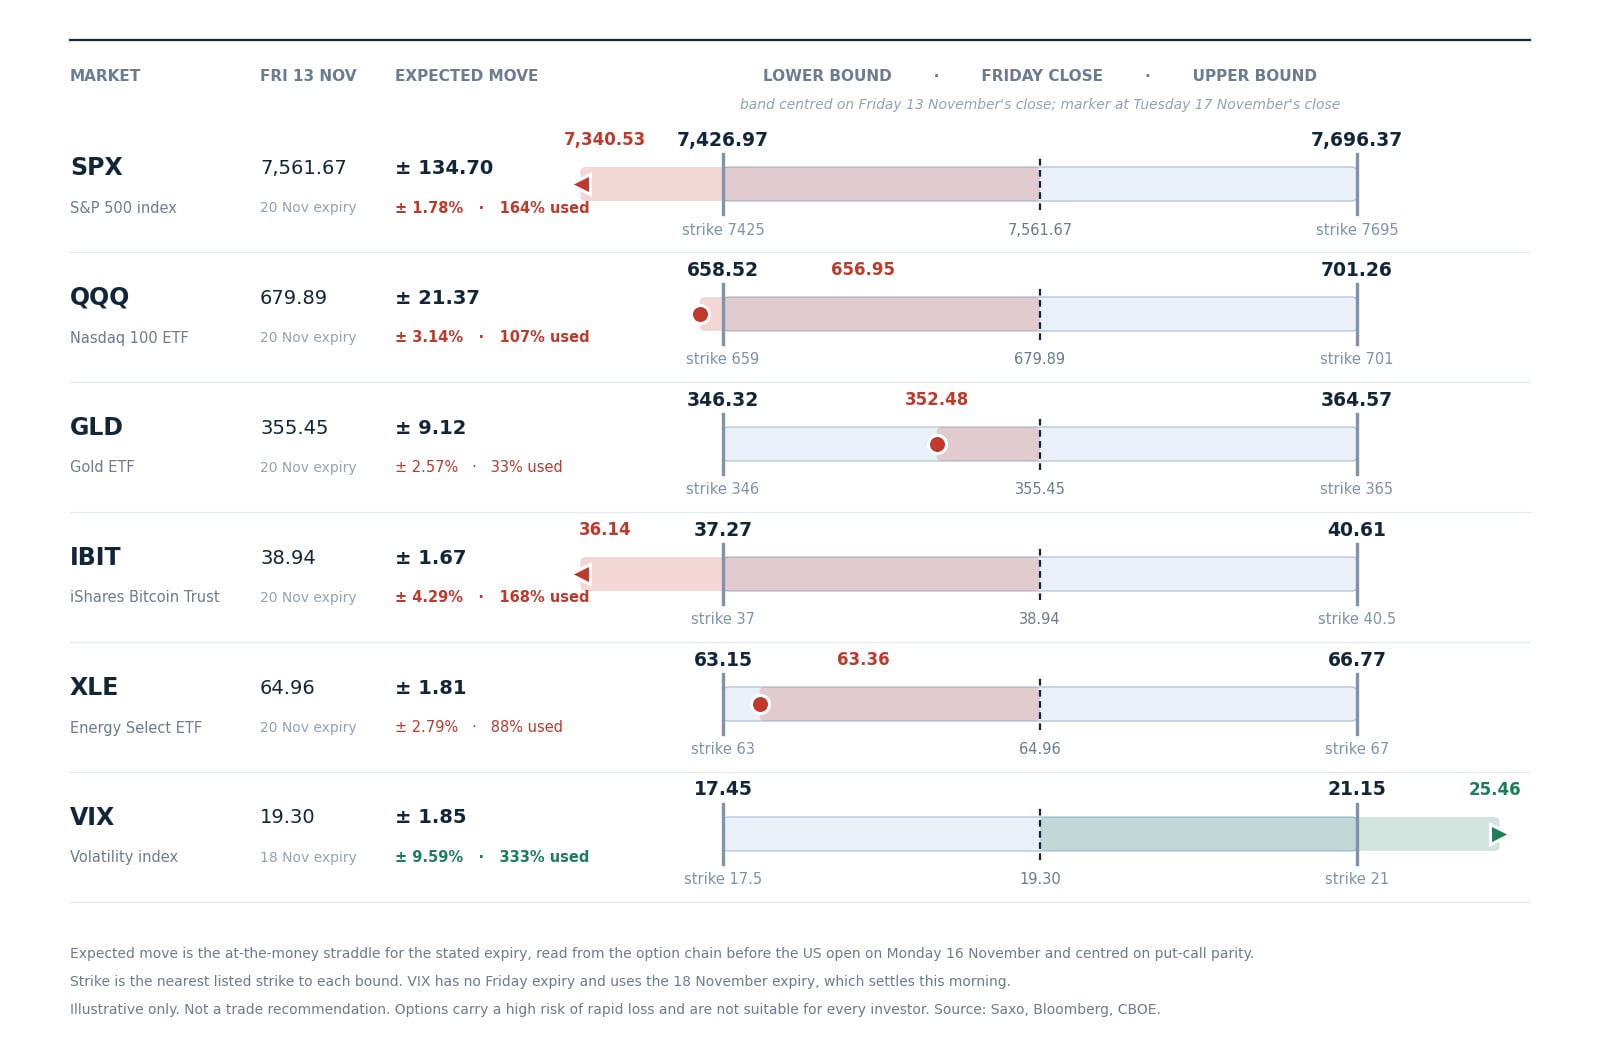
The range the option market priced for this week around Friday 13 November’s close, with each marker at Tuesday 17 November’s close. Illustrative only, not a trade recommendation. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
The S&P 500 is now well outside the week’s range. The option market priced 134.70 points around Friday’s 7,561.67 close, 1.78%, from 7,426.97 to 7,696.37, and Tuesday’s close at 7,340.53 sits below the lower bound, using 164% of the range. The bitcoin fund used 168%, and the VIX finished far above its own band, at 333%.
The Nasdaq 100 fund slipped just below its band at 107%, and the energy fund used 88%, both on the downside, while the gold fund used only 33%. The Friday-close reading was missing, so the bands come from Monday’s pre-open chain, five sessions to expiry. The VIX row uses the 18 November expiry, which settles this morning.
Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply and vary by account and venue; check the rates applicable to you.
Today's catalysts
- Today: 08:00 CET UK inflation for October; 14:30 CET US housing starts and building permits; 15:25 CET ECB President Lagarde; 16:00 CET Bank of England Governor Bailey; 16:30 CET US crude inventories; 19:00 CET a 20-year Treasury auction; 20:00 CET the Fed minutes, two hours before the 22:00 CET US cash close. TJX, Lowe’s and Target report before the US open, Palo Alto Networks after the close, and Tencent reports today.
- This week: Walmart and Intuit report on Thursday.
Earnings scorecard
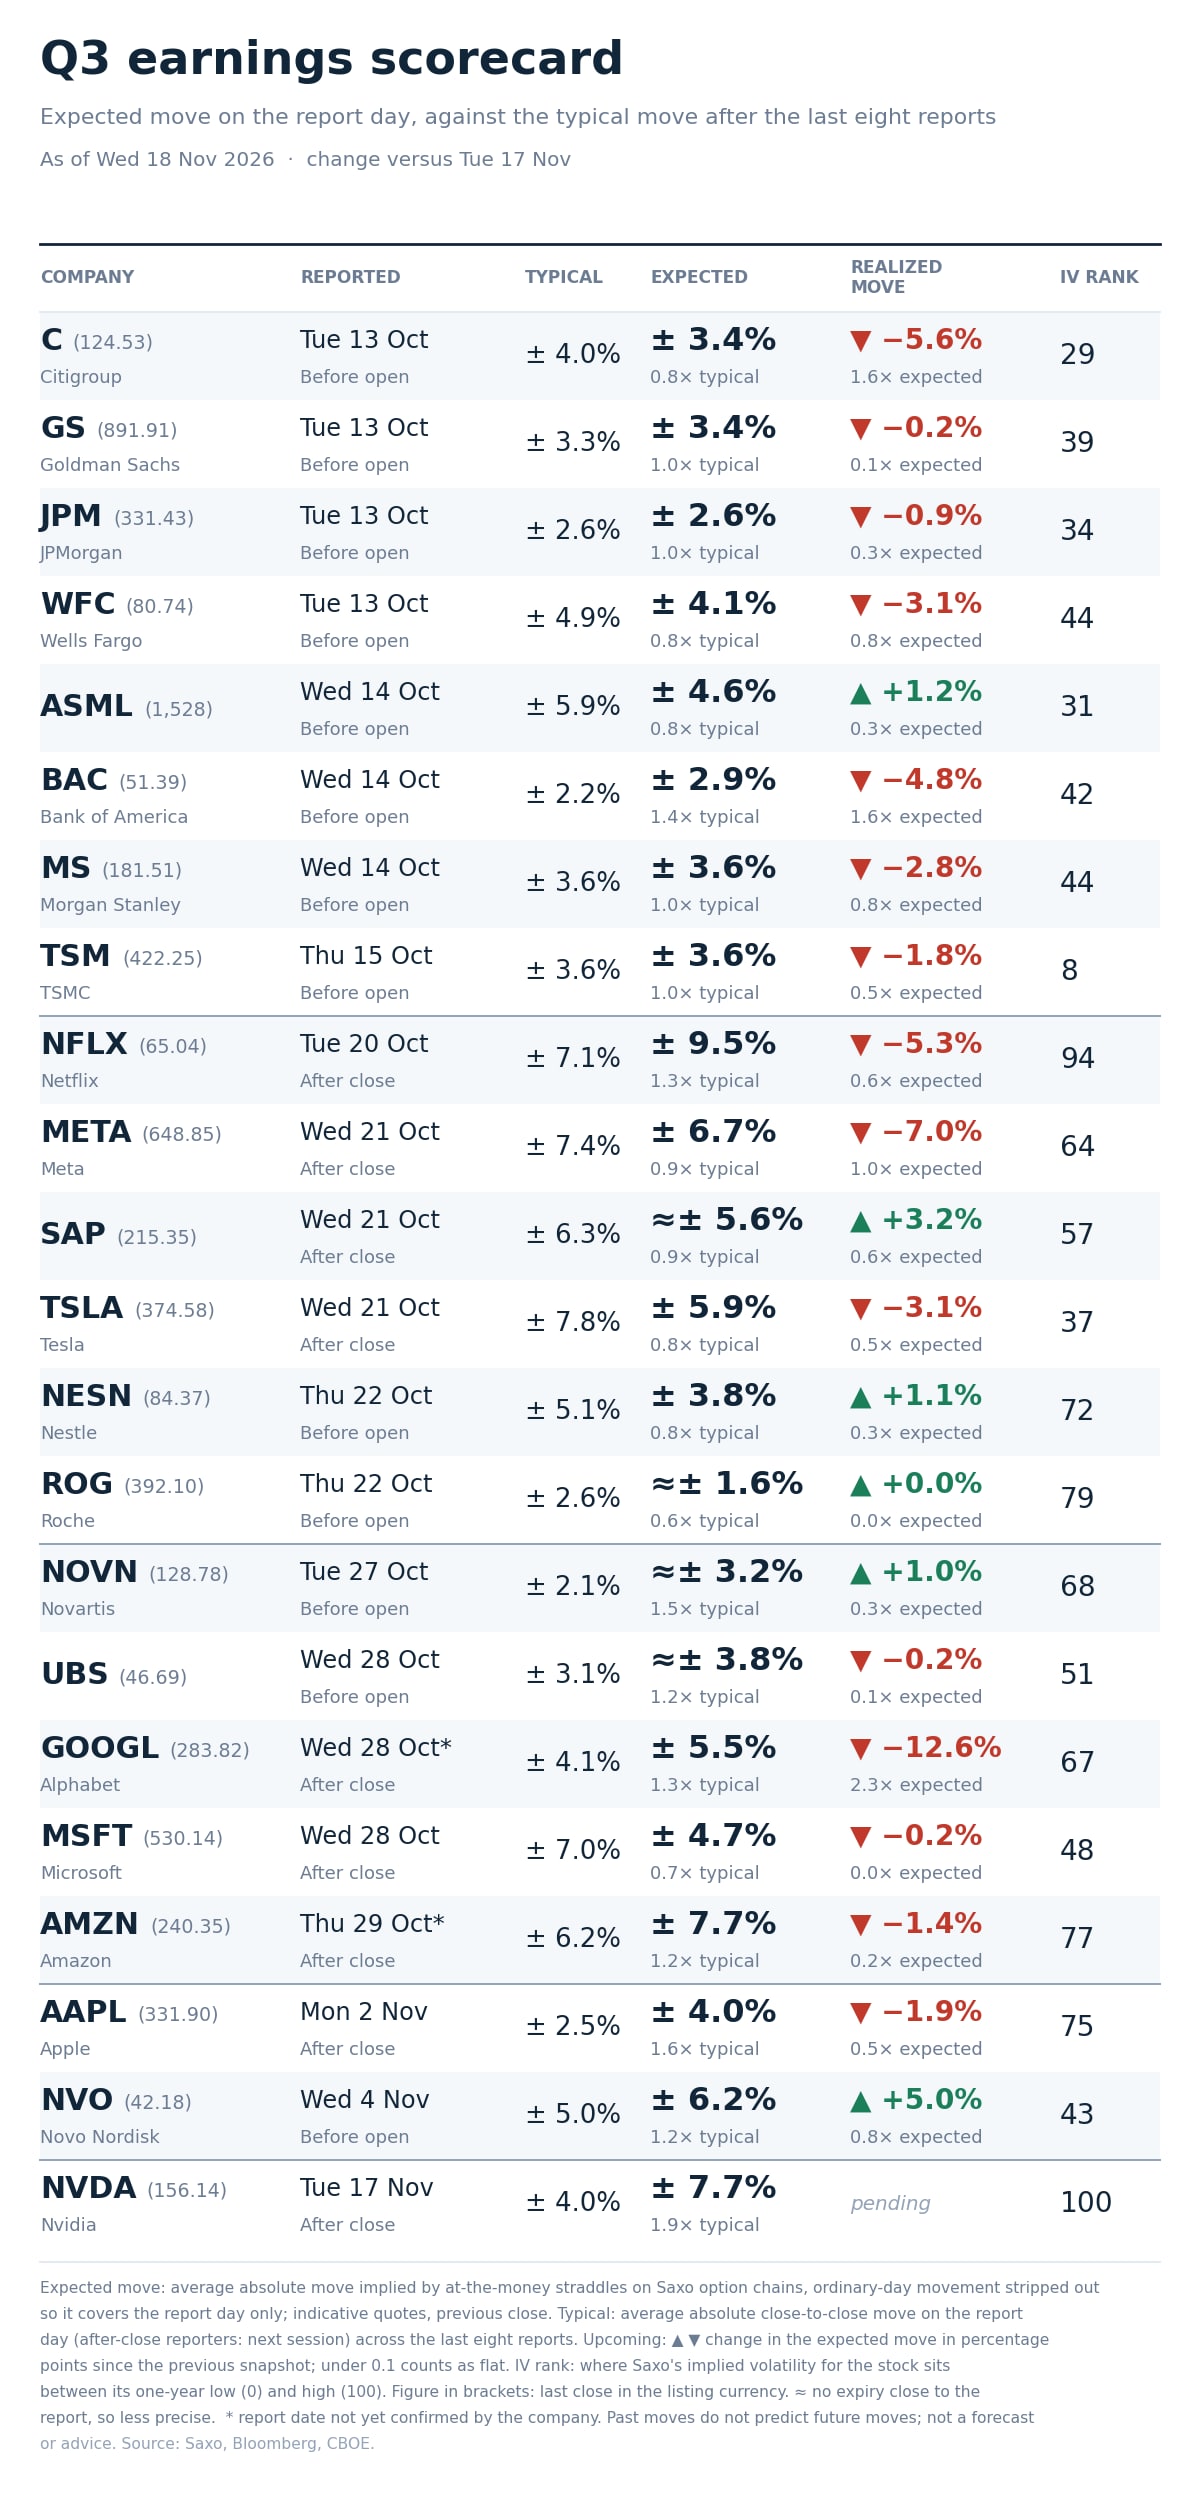
Option-implied expected move for each report day against the stock’s average move after its last eight reports, across the twenty-two names tracked this season. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
Nvidia was the last of the twenty-two names to report. Its options priced a report-day move of about 7.7%, 1.9 times the 4.0% it has moved on average after its last eight reports. The shares rose 4.8% after the close, according to the Quick Take; the board records the realised move once today’s session is complete.
Across the other twenty-one, 17 moved less than priced and 4 moved more, with a median realised move of about 0.5 times the expected move. Alphabet’s fall of 12.6% against 5.5% priced remains the largest miss, and Microsoft’s 0.2% against 4.7% the smallest move against its price.
In our view the season may show that option prices on report days were mostly generous, with a few large exceptions that carried the risk.
Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply and vary by account and venue; check the rates applicable to you. Past performance is not indicative of future results.
What the market is pricing
- Session implied range: S&P 500 options price about 1.25%, roughly 92 points, for today’s expiry, from indicative quotes read before the US open. The session holds the first cash reaction to Nvidia and the Fed minutes. The one-day gauge at 26.84 implies about 1.69%, a one-standard-deviation figure, a different measure from the expected move.
- Clock against price: yesterday’s edition quoted 146.90 points, 1.98%, for the 20 November expiry with four sessions left. Time alone would have left about 127 points, roughly 1.71%, and it now prices 149.75 points, 2.04%, so in our view the market may have added premium for the rest of the week again.
- Week ahead: netting out today leaves about 1.61% for Thursday and Friday together.
- Correlation read: implied correlation rose 17.64% and the dispersion index sits close to its 60-session high, while SKEW eased. In our view that may suggest the market is paying for wide moves in which stocks travel together, rather than for a crash in the index.
In our view the inverted front of the curve may say less about the next three months than about the next session, which now carries Nvidia’s first cash reaction and the Fed minutes before the close. Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply and vary by account and venue; check the rates applicable to you. Past performance is not indicative of future results.
| More from the author |
|---|