
Un seul compte Saxo suffit pour accéder à nos plateformes.

Chips break, software catches - Options Brief - 15 September 2026
Options 10 minutes to read
Résumé: The chip complex lost 5.9% and the index lost half a percent. The interesting part is what the option market did about Friday overnight.
MARKET REGIME: TRANSITIONING | VIX 17.10 | TERM STRUCTURE: CONTANGO | SKEW: ELEVATED (152.09) | FRONT-MONTH VIX FUTURES: 16.89
- Friday’s expiry refused to decay. The 18 September contract prices 100.90 points, or 1.32%, against 101.65 quoted yesterday morning. One session has come off the clock, so time alone would have left roughly 91. About 10 points of volatility premium went in overnight.
- The selling was narrow, not broad. A semiconductor gauge fell 5.9% and Nvidia 3.4%, while software rose 5.04% and healthcare 1.45%. The S&P 500 gave up 0.48% and its equal-weighted version added 0.04%.
- One session has used the week’s volatility budget. The VIX closed 17.10, above the 16.96 that Friday’s option chain set as the top of its range for the whole week.
Vol surface data: Saxo, Bloomberg, CBOE, as of 15 September 2026, approx. 07:18 CET. Past performance is not indicative of future results.
Headline driver
A weekend essay from the head of Anthropic urging a slower pace of frontier artificial intelligence work, backed publicly by the heads of OpenAI and xAI, hit chipmakers on Monday while the US 10-year Treasury yield cleared 5.02% for its highest reading since 2007. Full macro rundown in Saxo’s Market Quick Take – AI warning hits chips as ten-year tops 5% before Fed, 15 September 2026, and more in Saxo’s macro coverage.
Market snapshot, Monday 14 September 2026 close
- US (Monday 14 September close): S&P 500 7,619.98, down 0.48%. Nasdaq 100 29,127.16, down 0.82%. Dow 52,426.25, down 0.29%. Corning fell 13.7% on artificial intelligence concerns and a USD 2bn share sale, and Bank of America 5.1% after warning on trading revenue, while CrowdStrike gained 13.8%.
- Europe (Monday 14 September close): Stoxx 600 636.00, down 0.49%, with its technology group 2.1% lower. Soitec lost 12.6% and Infineon 7.7%. Capgemini rose 6.6% and GSK 4.7% after lung cancer trial results.
- Asia (Tuesday 15 September session): the Nikkei 225 slipped 0.1%, the Kospi fell 1.2% and the Hang Seng 0.4%. SoftBank rebounded almost 8.0% after Monday’s 10.7% fall.
- Commodities and rates: Brent trades near USD 107.50 after spiking towards USD 110 on Monday, with the Saudi East-West pipeline expected to stay shut for weeks. Gold sits near USD 4,300 after touching USD 4,252, and copper near USD 6.36. The US 2-year yield trades near 4.68%. EURUSD 1.1535, USDJPY 154.79. Costs and charges apply to exchange-traded fund trades; see Saxo pricing for costs and applicable charges.
- Market regime (rules based read): Transitioning, VIX 17.10, with the S&P 500 sitting 0.13% from its 50-day moving average and 20-day realised volatility at 8.9% and falling.
Source: Saxo, Bloomberg, CBOE, 15 September 2026. Past performance is not indicative of future results.
Options flow sentiment
Based on end-of-day 14 September, yesterday’s positioning and not today’s price action.
- Single-name flow: confirmed-opening premium across the tape reached USD 2.79bn and split 75.3% to calls, but twenty-eight of the thirty largest lines crossed at mid in deep in-the-money or paired form. That is rolling and financing rather than a view. The one clean purchase of the session was long-dated downside in a single carmaker at USD 21.6m, lifted on the offer. In our view the size says institutions were repositioning before the decision rather than choosing a side.
- Sector and ETF flow: semiconductor names carried USD 319.1m with 57.2% in calls, and the composition matters more than the split. The upside went into the leaders as matched November strike pairs, while the downside went into the sector basket rather than the single names. Named funds are market context only. Costs and charges apply to exchange-traded fund trades; see Saxo pricing for costs and applicable charges.
Volatility surface – 15 September 2026, approx. 07:18 CET
VIX term structure
- VIX spot 17.10 (up 7.95%)
- VIX1D 12.02 (down 7.40%) · VIX9D 16.91 (up 16.86%), the move sits in the event window rather than in today
- VIX3M 19.28 (up 3.66%) · VIX6M 20.71 (up 1.57%) · VIX1Y 21.97 (up 1.01%), the cash curve holds contango across its length
VIX futures
- Front-month VIX futures 16.89 by put-call parity on the 16 September expiry, a 0.21 point discount to spot against a 0.82 point premium yesterday. The continuous series reads 18.550, a level belonging to the October contract after the roll, so no session comparison is drawn from it
- Second-month VIX futures 18.505 by the same method, front-to-second ratio at 0.913 against 0.906 yesterday
Skew and correlation
- CBOE SKEW 152.09 (down 1.55%), still far above the 100 to 120 neutral zone
- COR3M 12.03 (up 7.31%), implied correlation rose on a session of violent single-name moves
- DSPX 31.69 (up 3.63%), the S&P 500 dispersion index. Equity put/call ratio 0.839, index put/call 0.948. The tail index rose 13.24% to 17.05
Cross-asset volatility
- OVX 59.46 (up 0.92%), oil volatility barely moved while crude held its gains
- GVZ 26.54 (up 3.35%) · VXSLV 46.25 (up 3.33%) · MOVE 83.90 (up 2.06%)
- VXN 22.05 (up 4.90%) · RVX 20.95 (up 4.85%) · VXD 15.30 (up 4.94%) · VVIX 94.89 (up 3.95%). Bond fund volatility rose 10.22% to 13.48
Source: Saxo, Bloomberg, CBOE, 15 September 2026. Past performance is not indicative of future results.
Where the week’s range sits
What the option market priced for this week around Friday’s close, and how much of it Monday used.
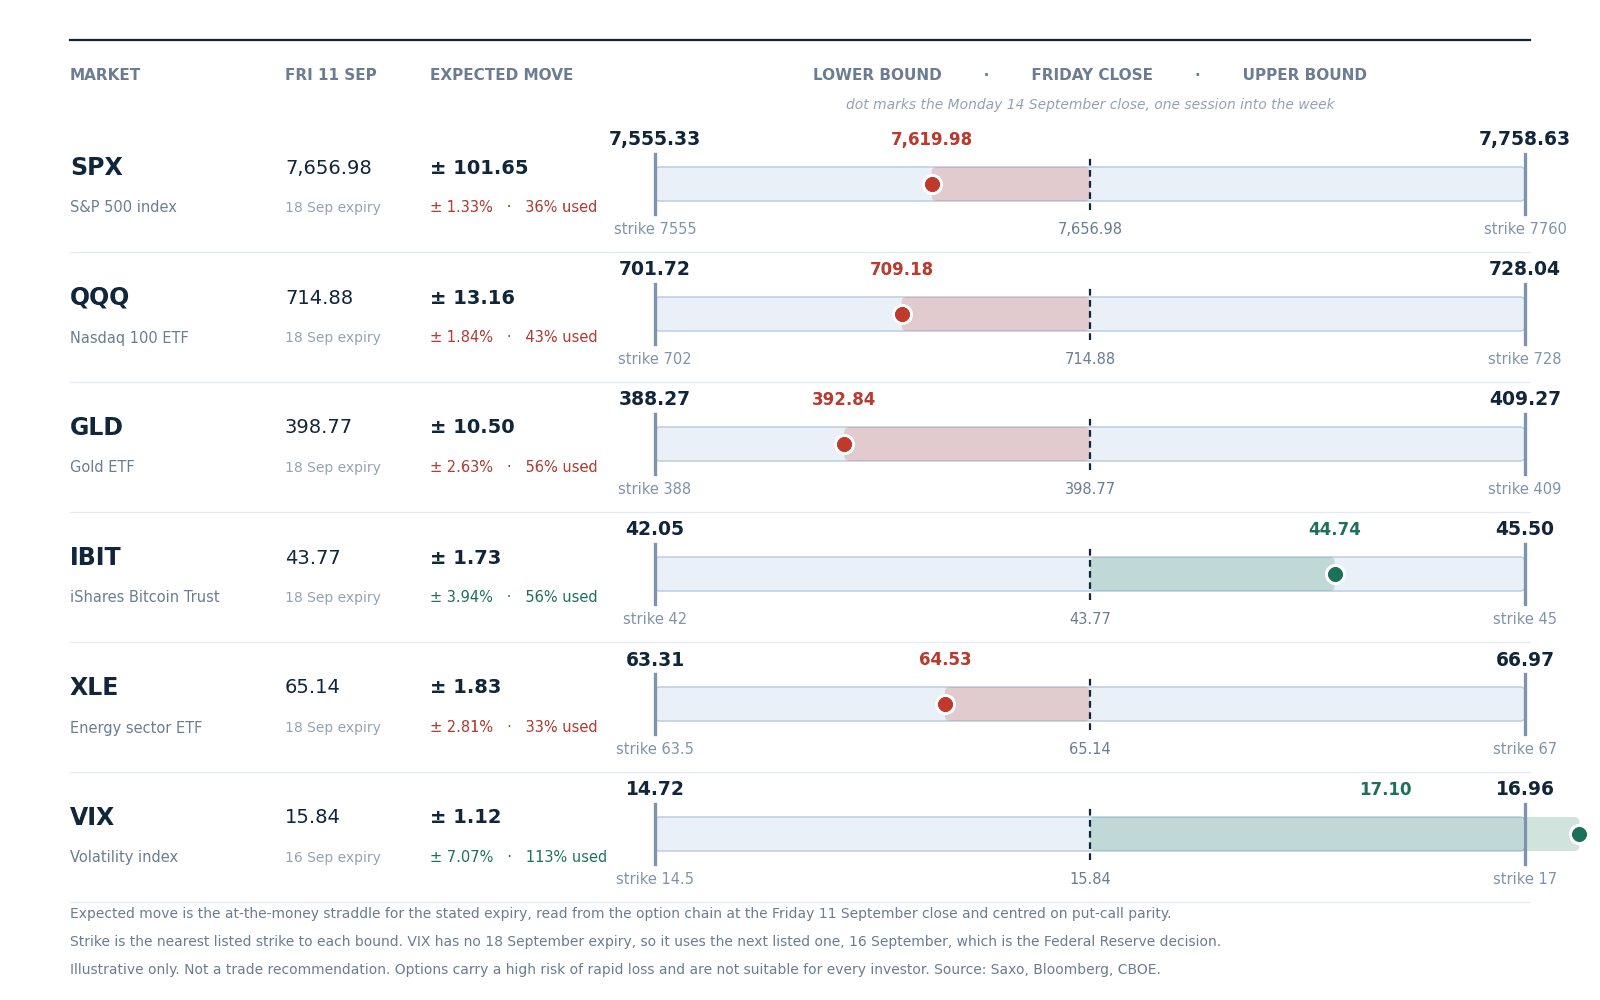
Expected move to the 18 September expiry, drawn around the Friday 11 September close, with the nearest listed strike at each bound. Volatility uses the 16 September expiry, the next one listed. Read from the option chain at Friday’s close and centred on put-call parity, not a forecast. Past performance is not indicative of future results.
- Equities spent about a third of their band, volatility spent all of it. The S&P 500 used 36% of its 101.65 point range in one session and the Nasdaq 100 fund 43%, while the VIX has already travelled 113% of the 1.12 point move the chain priced for the full week. Gold used 57% and the bitcoin fund 56%, both wider bands to begin with.
- Three sessions remain and the equity band is still mostly unspent. In our view a market that has kept two thirds of its S&P 500 range intact through a 5.9% semiconductor drawdown may be saying the damage stayed inside the index rather than moving it. Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply to exchange-traded fund trades; see Saxo pricing for costs and applicable charges.
What the market is pricing
- Session implied move. Today’s expiry prices 38.65 points, or 0.51%, derived from at-the-money option pricing rather than a forecast, with the German ZEW survey the only scheduled release inside the window and the Federal Reserve one session away. Options carry a high risk of rapid loss and are not suitable for every investor. See Saxo pricing for costs and applicable charges.
- Event implied range. The 18 September expiry carried 101.65 points yesterday morning and prices 100.90 now, where flat volatility and one fewer session would have left about 91. In our assessment paying to hold a window flat while the clock runs against it appears to be the clearest statement the option market made overnight.
- Term-structure read. Spot volatility rose 1.26 points while the contract expiring tomorrow rose 0.23, turning a 0.82 point premium into a 0.21 point discount. In our view a front contract that declines to follow spot upward may point to a market treating Monday’s move as concentrated damage rather than the start of something broader.
- Correlation and dispersion read. Implied dispersion rose 3.63% to 31.69 and three-month implied correlation 7.31% to 12.03, which is unusual company for the two measures. In our assessment paying up for both at once may reflect a session where single names moved violently and moved together, one sector against another, rather than scattering.
Options carry a high risk of rapid loss and are not suitable for every investor. Past performance is not indicative of future results.
Today’s catalysts
Germany publishes the September ZEW survey at 11:00 CET. G20 energy ministers continue in Houston through Wednesday. The US Senate holds a cloture vote on digital asset market structure legislation. The Federal Reserve decides tomorrow, with rate markets pricing roughly a 92% chance of a 25 basis point increase, and quad witching falls on Friday inside the same expiry. Future outcomes are uncertain and may result in losses.
Conclusion
In our assessment, Monday moved a great deal of money without moving the index much, and the option market answered by paying up for the rest of the week rather than for today. The pairing of a 0.51% same-day range with a Friday window that held 100.90 points through a full session of decay suggests the market may have decided the risk sits at the Wednesday decision and the Friday expiry, not in the hours in front of it, though that reading could change on a single headline and options carry a high risk of rapid loss that is not suitable for every investor. Past performance is not indicative of future results.
Important note: The strategies and examples provided in this article are purely for educational purposes. They are intended to assist in shaping your thought process and should not be replicated or implemented without careful consideration. Every investor or trader must conduct their own due diligence and take into account their unique financial situation, risk tolerance, and investment objectives before making any decisions. Remember, investing in the stock market carries risk, and it’s crucial to make informed decisions.
| More from the author |
|---|