
You can access both of our platforms from a single Saxo account.

AMD after a ten percent day: taking something off the table without selling the shares
Summary: AMD added almost 10% in a single session and crossed a trillion dollars in market value. For an investor who already owns the shares, there is a way to bank part of that move without selling a single one. The question is what it costs.
A large one-day gain leaves a long-term holder with a pleasant problem, and options offer a middle path between holding everything and selling out.
Advanced Micro Devices closed at USD 615.52 on 21 September 2026, up 9.95% on the session from USD 559.82 (Source: Saxo, as of 22 September 2026), carrying the company past a USD 1 trillion market value for the first time. The trigger was not a company announcement. Meta's AI agent app Muse reached the top of Apple's free app chart, and agent workloads lean heavily on server processors, a segment AMD's management has pointed to as its fastest-growing (Source: The Motley Fool, 21 September 2026). Past performance is not indicative of future results.
A day like that changes an investor's arithmetic more than it changes the business. The shares now trade at roughly 158 times trailing earnings against a five-year median near 102 times (Source: GuruFocus, 21 September 2026). None of that says the run is over, but an investor sitting on a large unrealised gain may want to bank part of it, and selling stock is not the only way.
A covered call is the alternative. An investor holding at least 100 shares can sell one call option against every 100 held, receiving cash today in exchange for agreeing to sell those shares at the strike price if the stock is above that level at expiry. The premium is kept either way. What is given up is the gain above the strike.
Important note: The strategies and examples provided in this article are purely for educational purposes. They are intended to assist in shaping your thought process and should not be replicated or implemented without careful consideration. Every investor or trader must conduct their own due diligence and take into account their unique financial situation, risk tolerance, and investment objectives before making any decisions. Remember, investing in the stock market carries risk, and it’s crucial to make informed decisions.
Selling a call against part of the position
The thesis here is modest, and it should be. An investor doing this is not calling the top. The view is that the shares have moved a long way in a short time, and that selling higher would be an acceptable outcome if the market gets there.
One thing changed alongside the price: the options became more expensive. Implied volatility, which is the market's estimate of how much the shares may move, rose from roughly 49% on 19 September to roughly 55% on 22 September (Source: Saxo, as of 22 September 2026), and a seller receives more premium when implied volatility is higher. At roughly 55% it appears to sit nearer the middle of AMD's own range over the past year than the top, which in our view makes this a modest repricing of the options rather than an exceptional one.
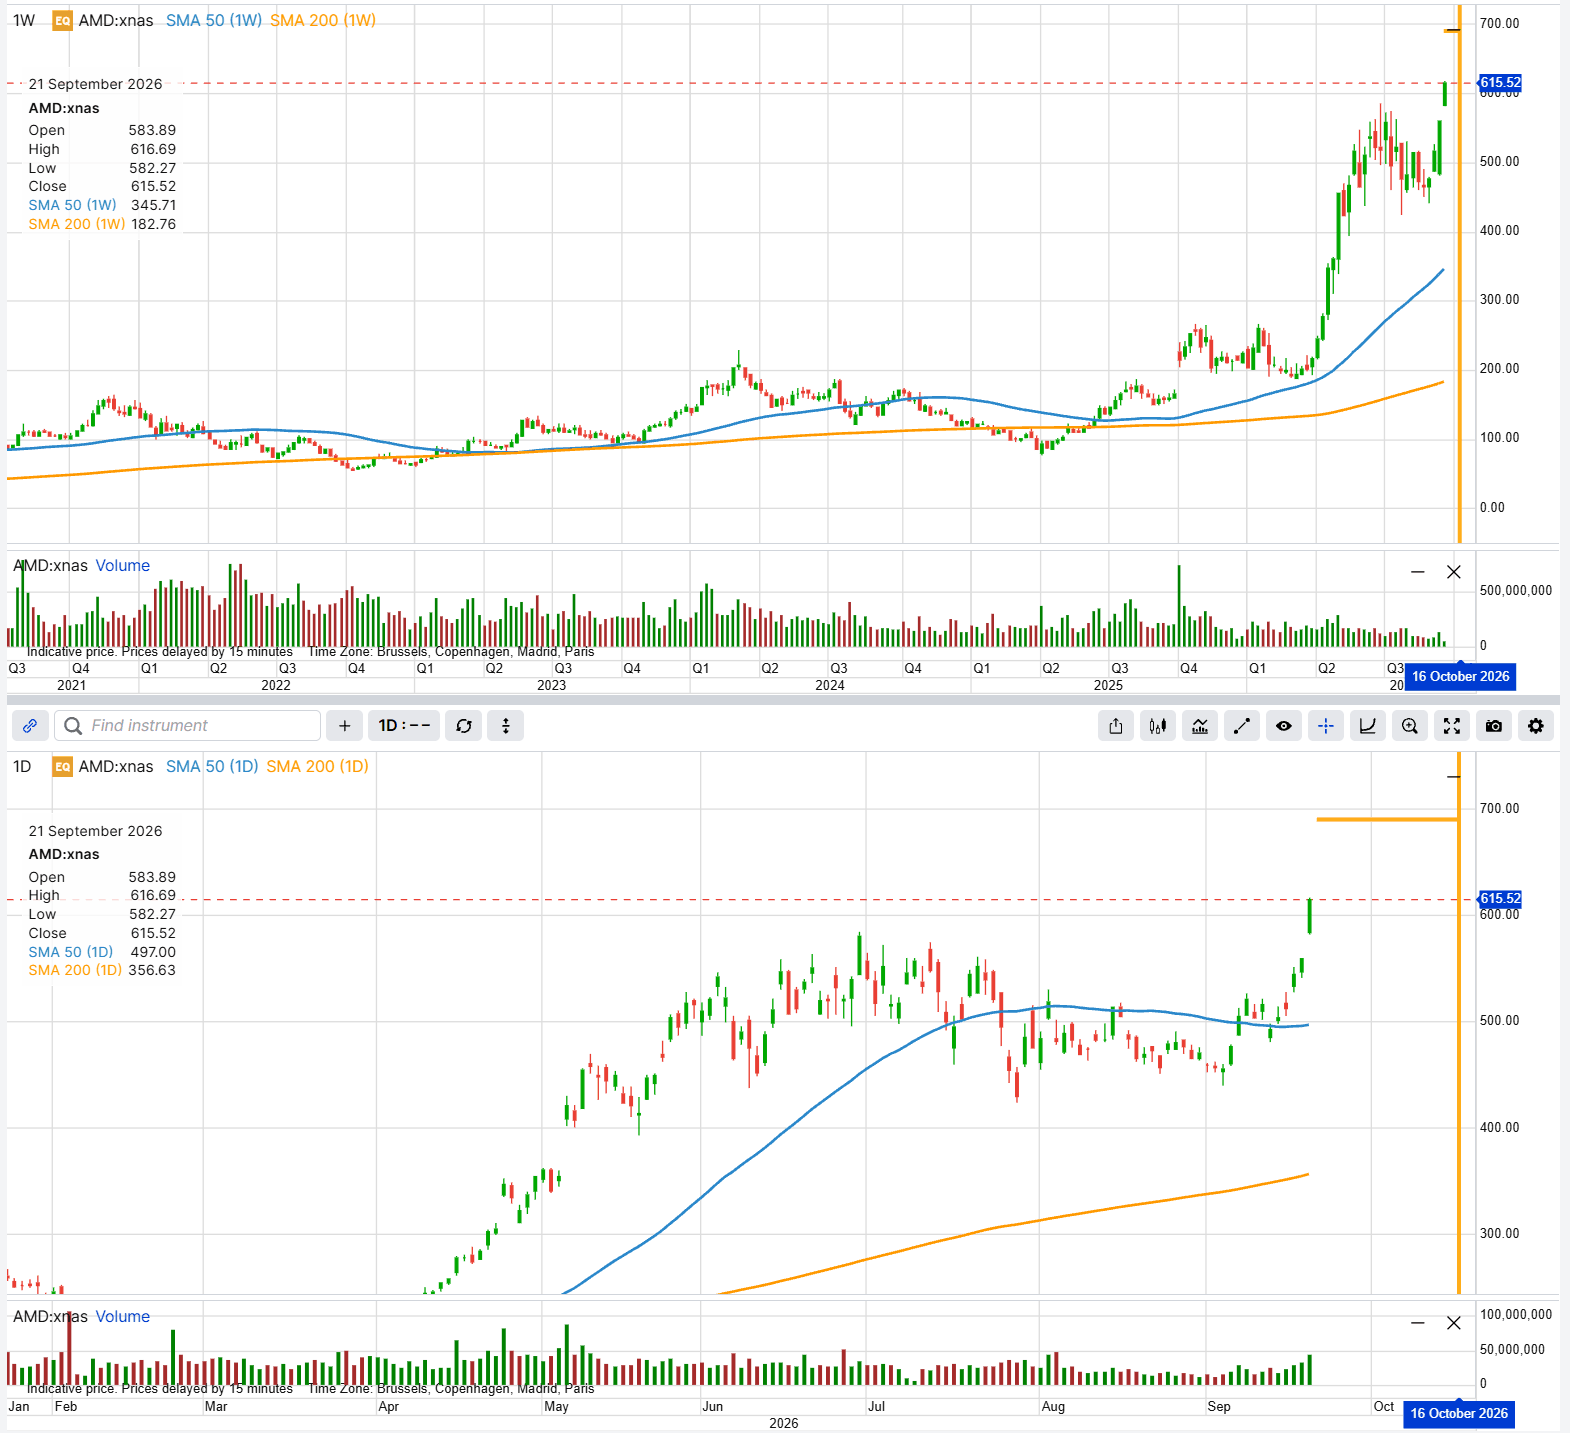 AMD to the 21 September 2026 close at USD 615.52, with the 16 October option strikes marked. This chart is illustrative and for educational purposes only; it is not predictive. Past performance is not indicative of future results. Source: SaxoTrader.
The following examples are hypothetical and for educational use only; they are not advice or trade recommendations.
Example structure (illustrative only – not a trade recommendation)
- Existing holding: 100 AMD shares, reference price USD 615.52
- Sell 1 AMD 16 October 2026 690 call at approximately USD 12.80 (bid USD 12.65, ask USD 12.95)
- Premium received: approximately USD 1,280 per contract, around 2.08% of the share price
- Effective sale price if assigned: USD 702.80, about 14.2% above the 21 September close
- Break-even on the shares: approximately USD 602.72
- Maximum gain from the 21 September close if assigned: approximately USD 8,728 per contract, against maximum risk of the full downside of holding 100 shares, reduced only by the USD 1,280 received
Risk: the seller retains the entire downside of the shares and forgoes all gains above USD 690; the short call carries early-assignment risk. Costs and charges apply to each leg; see Saxo pricing for full details. Hypothetical and for education only, not advice or a trade recommendation. Saxo indicative quotes, 22 September 2026, taken outside US market hours; verify in the live chain before use.
The USD 1,280 lands in the account when the trade is done and is not repayable, but the investor retains the full downside risk of holding the shares: the premium provides a partial offset, it does not protect against a significant decline in the stock price. The obligation runs the other way too. Above USD 690 the shares are likely to be called away, so a move to USD 800 would be capped at an effective USD 702.80, with roughly USD 97 per share of upside sold.
Time is the seller's ally here, but only while the strike holds. Theta measures time decay, the small amount of value an option loses each day, and for the seller that works in the position's favour. The same 24 days that erode the option's value are 24 days in which AMD could run past USD 690 and take the shares with it, or fall far enough that the premium looks like small consolation. Illustrative only – not a trade recommendation.
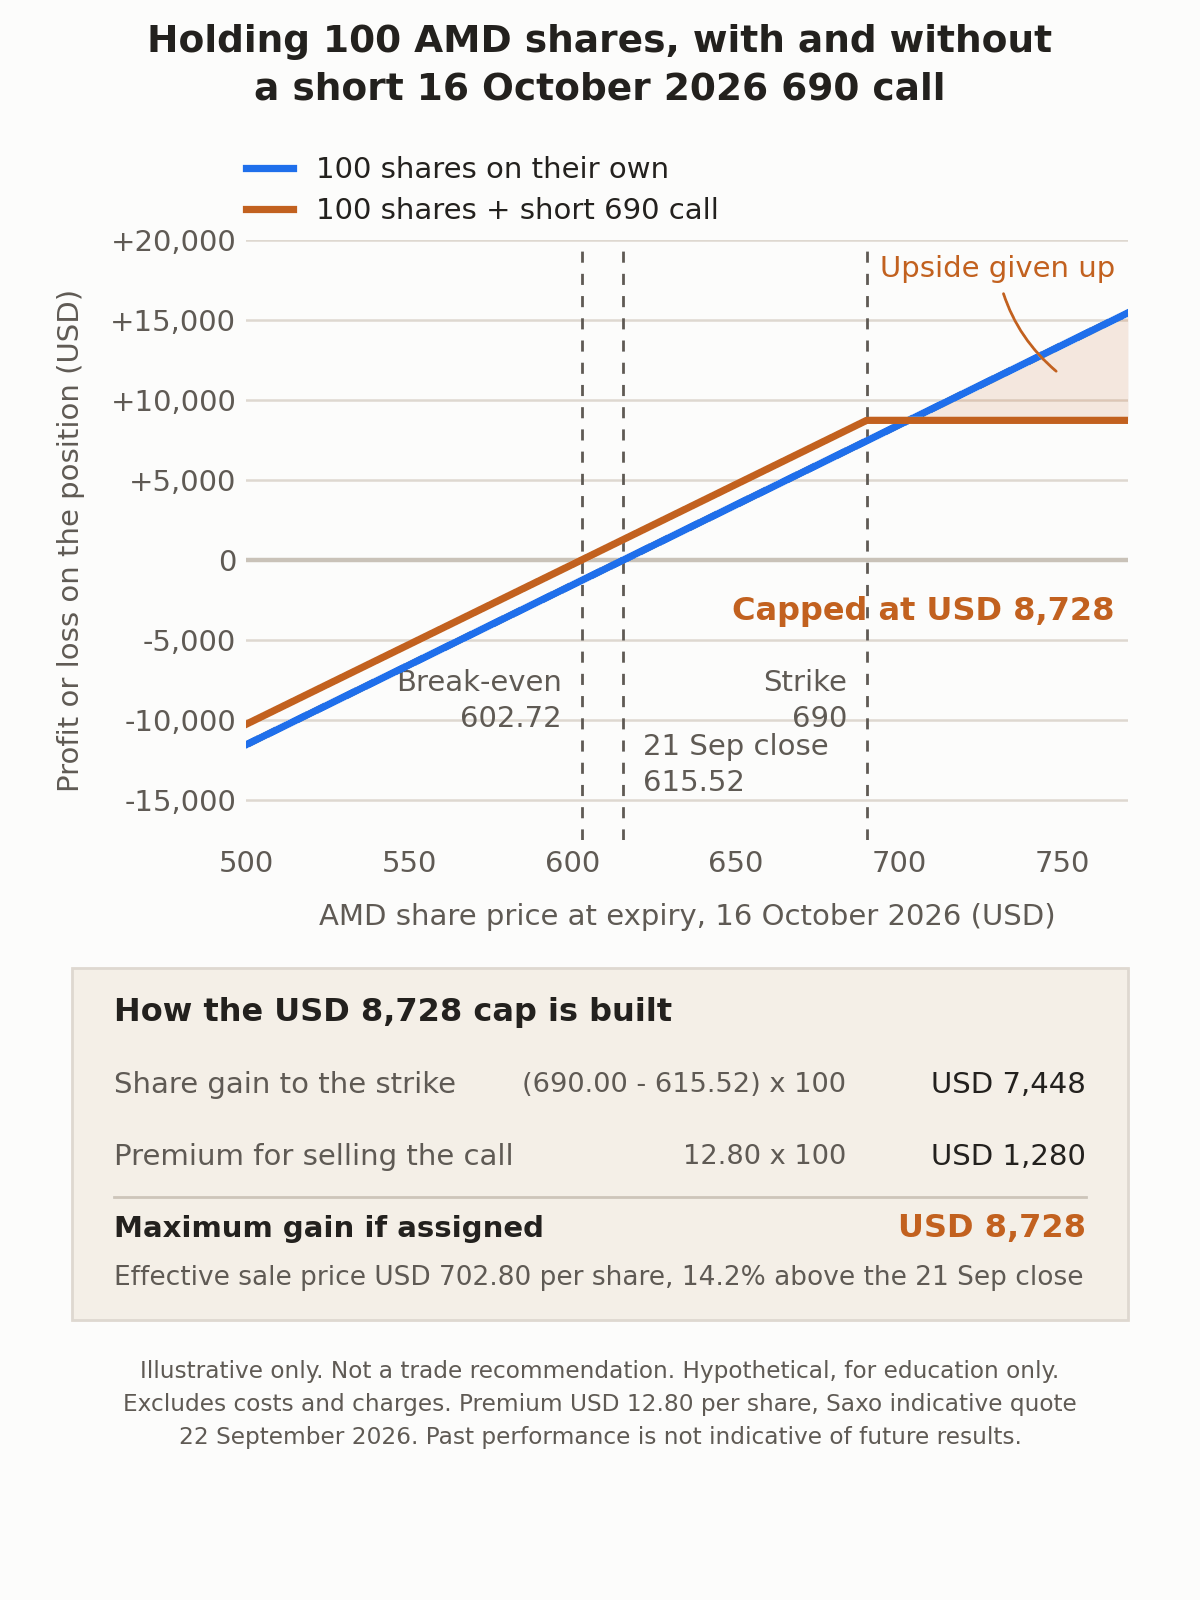 Result at the 16 October 2026 expiry for 100 AMD shares on their own against the same shares plus one short 690 call, with the USD 8,728 cap broken into its two parts. Illustrative only. Not a trade recommendation. This diagram is illustrative and for educational purposes only; it is not predictive. Past performance is not indicative of future results. Source: Saxo.
What the market says about that strike
There is a straightforward way to judge whether a strike is ambitious or timid. Add the at-the-money call to the at-the-money put for the same expiry, and the total roughly estimates the move the options market is pricing. For 16 October 2026 the 615 call was quoted near USD 36.75 and the 615 put near USD 34.48, a combined USD 71.23, about 11.6% of the share price (Source: Saxo, as of 22 September 2026).
That may temper any comfort about the 690 strike, which sits 12.1% above the close, barely outside a move the market currently appears to treat as ordinary for the next 24 days. The obligation is not parked somewhere remote, which is why it pays what it pays. AMD's next results are estimated for 3 November 2026, though unconfirmed by the company (Source: MarketBeat, as of 22 September 2026), so the 16 October expiry falls before the report. Future outcomes are uncertain and may result in losses.
If the premise is wrong
An investor who believes AMD's agent-driven CPU demand is at the start of a multi-year expansion should probably do nothing. Selling a call caps exactly the outcome that thesis is built on, and 2.08% is thin compensation for surrendering an open-ended move.
The bearish reader should not mistake this for a hedge. If the move looks like an overreaction, a covered call protects almost nothing, since the premium absorbs only about 2% of a decline. Selling shares, or buying a put, addresses that view more directly.
The neutral case is where this sits: an investor who wants to keep the position, accepts the shares may drift after a sharp move, and would be content to sell at USD 702.80. If any part of that does not describe the holder, the structure is not the right one. Options carry a high risk of rapid loss and are not suitable for every investor. See Saxo pricing for costs and applicable charges.
Before placing the trade, check
- Bid and ask spreads, since a wide spread can remove the edge at entry
- Volume and open interest at the chosen strike and expiry
- That the expiry is the intended one, since AMD lists weeklies alongside the monthly
- An exit plan, decided before entry rather than after a surprise
Assignment risk note: AMD options are American-style, so a short call can be assigned before expiry if it moves into the money, particularly close to expiration. AMD pays no dividend (Source: stockanalysis.com, as of 22 September 2026), which removes the ex-dividend assignment pressure affecting dividend-paying shares. Only the seller faces assignment risk.
Final thoughts
A covered call offers a long-term holder a third option between two blunt ones. Selling the shares ends the thesis; holding everything realises nothing. Writing a call against part of the position takes a defined amount of cash now, in exchange for a defined limit on one outcome, and leaves the rest of the holding alone. Options carry a high risk of rapid loss and are not suitable for every investor.
Nor does it have to be held to expiry, since a short call can usually be bought back before 16 October 2026 at whatever it costs then, which may be more than was received. In our view the useful discipline is to size the trade so that assignment would be an acceptable outcome rather than a disappointing one. Past performance is not indicative of future results.
Sources: Saxo, as of 22 September 2026; The Motley Fool; GuruFocus; MarketBeat; stockanalysis.com.
The author does not hold positions in any of the instruments mentioned in this article. The Author is permitted to wait at least 24 hours from the time of the publication before they trade the instruments themselves.
| More from the author |
|---|